


Can Golar LNG (GLNG) Justify Its Valuation On Sanctions Driven LNG Rerouting?
Sanctions, rerouted gas flows, and why Golar LNG matters now
Sanctions on Russia and Iran are reshaping global trade routes for oil, metals, and grains. This is increasing demand for flexible LNG infrastructure. Golar LNG (GLNG) sits in the middle of that reshuffling.
Golar LNG’s share price has climbed to US$51.79, with a 1-day share price return of 1.97% and a year to date share price return of 36.47%. The 5-year total shareholder return of 397.80% indicates long-running momentum that frames current moves as part of a broader rerating linked to its role in rerouted gas flows.
Compare how Golar LNG stacks up against other rerouting winners by scanning our hand picked list of list of solid balance sheet and fundamentals (23 results) that are positioned for shifting energy trade flows.
Golar LNG now trades at US$51.79 while analyst targets cluster near US$65, and one intrinsic value estimate implies a far steeper gap. So where does a plain vanilla fair value case really land?
Most Popular Narrative: 19% Undervalued
Against Golar LNG’s last close at $51.79, the most widely followed narrative points to a fair value of $63.94, framing today’s price as a discount that hinges on how its floating LNG backlog and growth projects play out.
The company has secured long-term (20-year) charters for its existing FLNG units, providing $17 billion in contracted EBITDA backlog and 20 years of cash flow visibility. This is expected to drive a significant (4x) increase in EBITDA and contracted free cash flow by 2028, indicating the market may be undervaluing its forward earnings stability and revenue growth.
See why 22 investors see Golar LNG as 19% undervalued.
Result: Fair Value of $63.94 (UNDERVALUED)
Still, Golar LNG’s story can shift quickly if the fourth FLNG project faces cost or timing issues, or if LNG demand or pricing weakens materially.
Find out about the key risks to this Golar LNG narrative.
Another View: What Golar LNG’s P/E Is Telling You
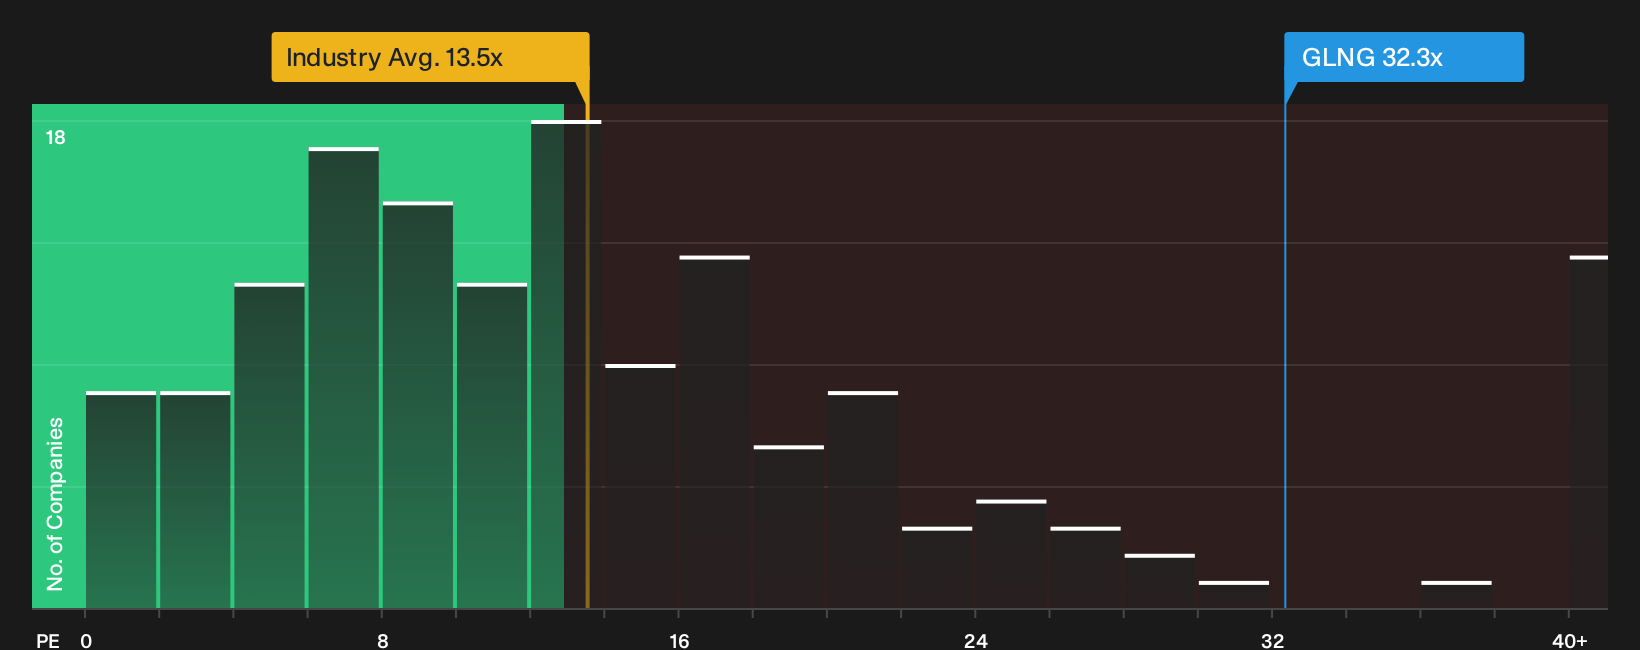
On a simple earnings multiple, Golar LNG looks far less cheap than the 19% undervaluation story suggests. The stock trades on a P/E of 32.3x, while the US Oil and Gas industry sits at 13.5x and close peers average 13x.
The fair ratio for Golar LNG is estimated at 32.7x, which is almost identical to the current 32.3x. That points to pricing that is already in line with where the market could move the multiple, so any upside case leans heavily on future earnings growth playing out as expected. Is that a margin of safety you are comfortable with?
For a deeper look at how this earnings multiple stacks up against the wider market and what that means for potential upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the bullish tone around Golar LNG matches your own risk appetite? Move fast, review both sides of the story, and weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Golar LNG?
If Golar LNG has sharpened your focus on opportunity and risk, do not stop here. Broaden your watchlist and give yourself more options to compare.
- Target quality at a discount by scanning 35 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- Strengthen your income plan by reviewing 7 dividend fortresses that combine higher yields with an emphasis on payout resilience.
- Steady your portfolio foundation by filtering for 30 resilient stocks with low risk scores that aim to keep volatility and financial fragility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com