


Is Ultragenyx Pharmaceutical (RARE) Cheap On FAYUVI FDA Approval?
Ultragenyx Pharmaceutical (RARE) is back in focus after the U.S. Food and Drug Administration granted standard full approval for FAYUVI, a gene therapy for children with Sanfilippo syndrome Type A.
Despite the positive headline, Ultragenyx Pharmaceutical’s recent trading tells a more complicated story. The share price is around US$14.51 after a sharp 30 day decline of about 44% and a 90 day slide of roughly 50%, while the 1 year total shareholder return is down about 48%. Short term traders have seen only modest share price gains around the FAYUVI approval, which suggests the news is being weighed against longer running concerns about risk, execution and the broader rare disease pipeline.
Spot opportunities around Ultragenyx Pharmaceutical by scanning our hand picked 16 high quality undiscovered gems with strong fundamentals that are still flying under most investors’ radar.Bulls point to Ultragenyx Pharmaceutical’s new FAYUVI approval and rare disease portfolio, while bears focus on the sharp share price slide and ongoing losses. Which side does the current valuation evidence support?
Most Popular Narrative: 44% Undervalued
Ultragenyx Pharmaceutical’s most followed narrative pegs fair value at $26 per share, compared to the recent $14.51 close, which implies a wide valuation gap based on that framework and a discount rate of 7.82%.
The "Ultragenyx Turnaround Thesis" is trapped in a commercial illusion, mistaking a multi-product portfolio for financial stability while ignoring deep-rooted structural inefficiencies. Here is why the market is mispricing the friction inside RARE’s operational engine:
See why 1 investors see Ultragenyx Pharmaceutical as 44% undervalued.
Result: Fair Value of $26 (UNDERVALUED)
Still, two things could challenge that bearish Ultragenyx Pharmaceutical storyline: cleaner visibility on FAYUVI economics and any clear progress shrinking the current US$586 million annual loss.
Find out about the key risks to this Ultragenyx Pharmaceutical narrative.
Another View on Ultragenyx Pharmaceutical’s Valuation
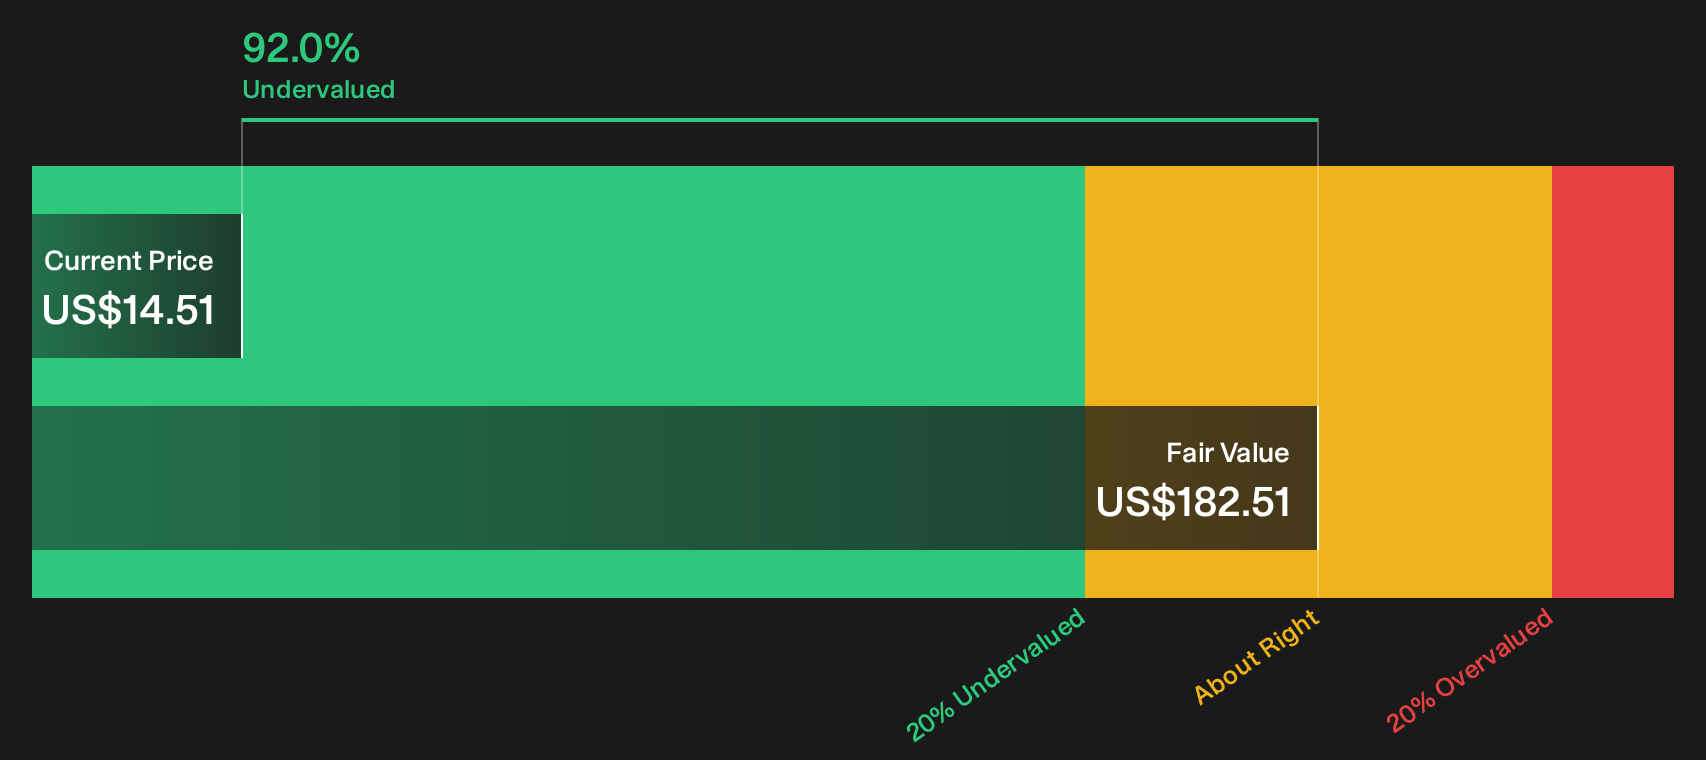
There is a sharp twist when the conversation shifts to the SWS DCF model. On that framework, Ultragenyx Pharmaceutical at $14.51 is set against an estimated future cash flow value of $182.51 per share, which flags the stock as very undervalued. Does that kind of gap signal opportunity or simply very optimistic assumptions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Ultragenyx Pharmaceutical is clearly split, with meaningful risks and real upside both on the table. Consider moving quickly and pressure test the numbers yourself using 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Ultragenyx Pharmaceutical?
Do not stop your research with Ultragenyx Pharmaceutical. Use the Simply Wall Street Screener to uncover other opportunities that fit your risk, income and value goals.
- Target resilient cash generators and filter for sturdier balance sheets by running a quick scan through our list of solid balance sheet and fundamentals (23 results).
- Hunt for potential value opportunities trading below their assessed worth by checking the 35 high quality undervalued stocks.
- Prioritize stability and capital preservation by focusing on companies that score well on our 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com