


Magnite (MGNI), What Is Behind The Fresh Attention?
Magnite (MGNI) is trying to reset how ad buying works. The latest updates to its Orchestration platform link AI agents across TV, audio, display, and video, while fresh partnerships test that pitch in real campaigns.
These product moves are landing against a busy tape for Magnite. The share price has climbed 44.13% over the past 90 days and 56.60% year to date, yet the 1 year total shareholder return is still down 2.97%. Momentum has picked up recently, but the longer record remains mixed.
Scan how Magnite’s AI-centric push compares with other hand-picked ad tech and media platforms by jumping into the 16 high quality undiscovered gems shaping the next wave of programmatic workflows.
Magnite is pitching real progress on AI driven ad buying, and the share price has reacted quickly. The harder question is whether that recent run leaves the stock expensive or still reasonable on fundamentals.
Most Popular Narrative: 9% Undervalued
Magnite last closed at $25.15, compared with a widely followed fair value estimate of about $27.67 that uses a 9.67% discount rate. As a result, the current narrative framing leans toward modest undervaluation rather than euphoria.
Magnite is positioned to benefit from the accelerating shift of ad spend from traditional TV to digital and connected TV (CTV) platforms, as evidenced by deepened partnerships with top streamers (Roku, Netflix, LG, Warner Bros. Discovery, Paramount) and expanding SMB participation in CTV, which is expected to drive sustained revenue growth and a higher-margin business mix.
See why 12 investors see Magnite as 9% undervalued.
Result: Fair Value of $27.67 (UNDERVALUED)
Still, Magnite’s heavy reliance on large CTV streamers, along with the risk that regulatory outcomes or live streaming demand do not translate into expected revenues, could challenge that undervaluation story.
Find out about the key risks to this Magnite narrative.
Another View: Magnite Through The Earnings Lens
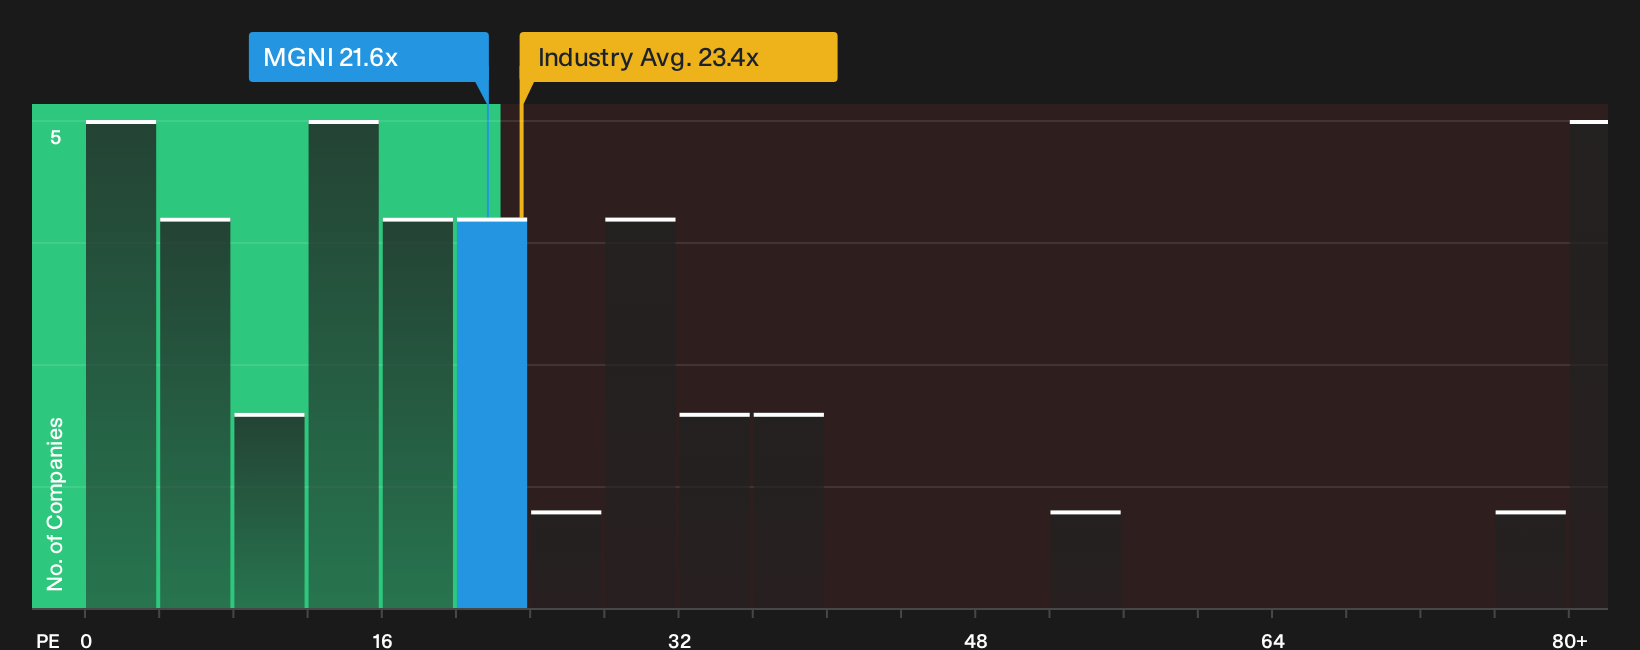
On earnings, Magnite looks less clear cut. The stock trades on a P/E of 21.6x, above an estimated fair ratio of 15x, yet still below the US Media group at 23.4x and well under a 63x peer average. That mix points to valuation risk if enthusiasm cools, but room if peers stay richly priced.
For a closer look at how that P/E gap could close in either direction, including what the fair ratio implies for future pricing power, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on whether Magnite’s recent surge is justified or simply a case of sentiment running hot. Move quickly, review the full data set, weigh the potential upside against the red flags, and base your own view on the balance of 2 key rewards and 1 important warning sign.
Looking for more Magnite sized opportunities?
Magnite is only one piece of the puzzle, and broadening your watchlist with fresh ideas can help you spot mispriced opportunities before the crowd.
- Target quality at a discount by scanning the market for companies that combine strong fundamentals with room for re rating using the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with robust finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for dependable income ideas that could complement growth holdings by reviewing the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com