


New Estates Gallery Might Change The Case For Investing In RH (RH)
- RH has opened RH Estates, The Gallery on Greenwich Avenue, its first freestanding RH Estates Gallery in North America, expanding the new concept beyond prior previews in Milan and London.
- The debut of RH Estates as a standalone destination signals a push into higher touch experiential retail. This could influence store economics, capital needs, and how RH monetizes its design and real estate platform over time.
- We will now look at how RH's first freestanding Estates Gallery could reshape the company’s broader investment narrative and long-term positioning.
Scan how RH's move into immersive galleries compares with other high-end retailers repositioning for experience driven spending through a curated set of 16 high quality undiscovered gems
RH Investment Narrative Recap
To own RH, you need to believe its high touch gallery and design model can support healthy pricing and steady demand even as housing and high end spending stay choppy. The Greenwich RH Estates launch fits that story by pushing deeper into experiential showrooms. The near term catalyst still looks operational, and management needs to prove these immersive formats can drive profitable traffic without stretching the balance sheet.
The biggest risk remains execution in a tougher housing backdrop while carrying meaningful debt and interest costs that are not comfortably covered by earnings. New galleries and global expansions add upfront costs and complexity. Based on the latest news, the Greenwich opening feels directionally important but not yet financially material on its own.
The second quarter report in early September is the clearest companion to the Estates news. RH posted sales of US$922.15 million and net income of US$60.17 million, with both basic and diluted EPS from continuing operations higher than a year ago. That indicates an operation that is still generating profits while it experiments with new gallery formats.
Management also guided to revenue growth of 5% to 6% for the third quarter, 16.1% to 21.2% for the fourth quarter, and 5.5% to 7% for the full year 2026. The Greenwich RH Estates opening now sits alongside that guidance as a visible test of the gallery expansion catalyst. Your focus as a shareholder is whether execution on these openings lines up with those revenue goals without putting added strain on margins or interest coverage.
RH's current analyst narrative points to revenues of US$4.4b and earnings of US$260.4 million by 2029, based on an 8.9% yearly revenue growth rate and an earnings increase of about US$157 million from US$103.1 million today.
Uncover why RH's fair value indicates a 38% potential upside to its current price that may not last much longer.
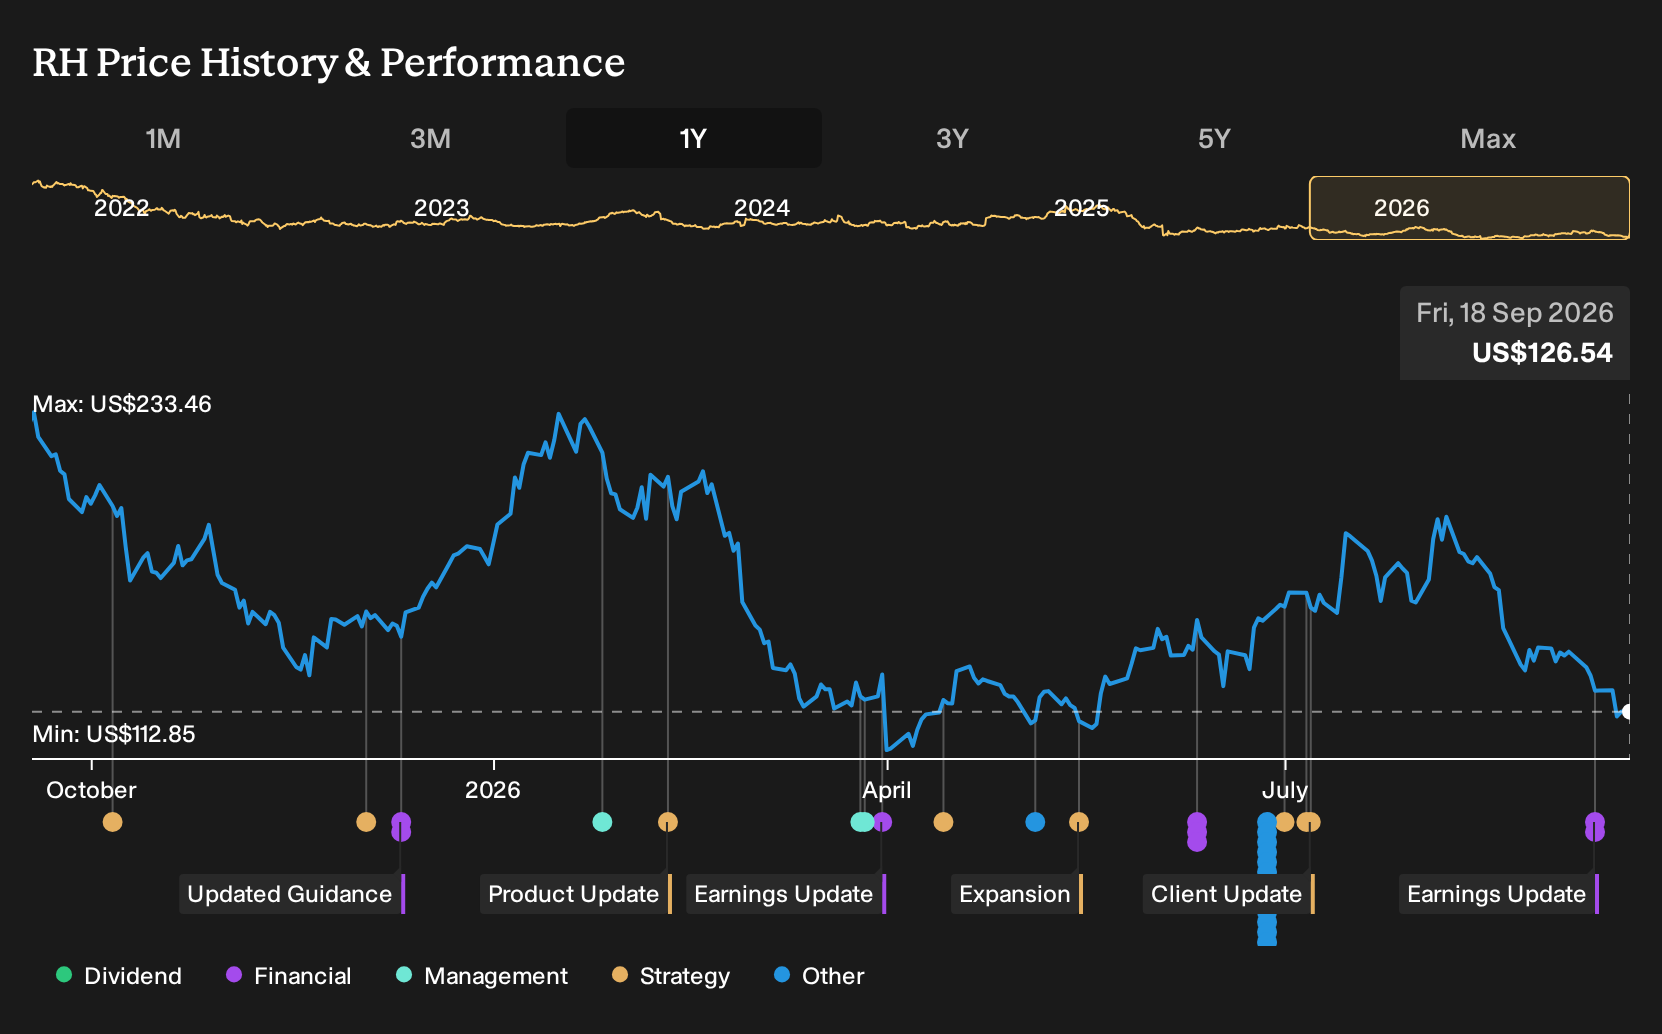
Exploring Other Perspectives
One alternate angle on RH focuses less on gallery excitement and more on earnings pressure from its US$2.2b debt load. The most pessimistic analysts were modeling only 8.0% yearly revenue growth to about US$4.3b and earnings of roughly US$115.4 million by 2029. Those pre news estimates show how far opinions can diverge, so it helps to compare several views before deciding how Greenwich Estates might reshape your own expectations.
Explore 4 other RH fair value estimates, including one that suggests as much as 34% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? You may want to consider forming your own view instead of simply following the herd.
- A great starting point for your RH research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for RH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RH's overall financial health at a glance.
Looking For More Investment Ideas Beyond RH?
After forming a view on RH, it often helps to compare it with other opportunities that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener can surface a wide range of stocks that fit the kind of portfolio you want to build.
- For investors who want potential upside without stretching quality too far, there is a curated set of 35 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If capital preservation and resilience matter most to you, focus on companies highlighted in our 30 resilient stocks with low risk scores that score well on stability factors.
- For readers who care about financial strength first and returns second, start with the list of solid balance sheet and fundamentals (23 results) to see businesses backed by sturdier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com