


monday.com (MNDY) Stock Could Be Undervalued On Its 77% Five Year Fall
monday.com has seen its share price fall hard in recent years, and that slide now puts a spotlight on a simple question for investors who still follow the stock. Is the current valuation backed up by the earnings the business is producing today and is expected to generate over time.
- The share price has declined 76.8% over the past 5 years, which puts a lot of pressure on the case that monday.com's earnings profile can still support the current market value.
- The business model is built around recurring software subscriptions and high upfront product investment, which can shape how efficiently revenue turns into profit and how long it takes for earnings to catch up with past spending.
- The analysts covering monday.com have run their own numbers. See what analysts think monday.com's shares could be worth.
The stock's next move may depend on whether monday.com's earnings are strong and reliable enough to justify where the share price sits today.
You can explore this same earnings question across a broader range of companies by scanning 35 high quality undervalued stocks.
Does monday.com Look Undervalued on Earnings?
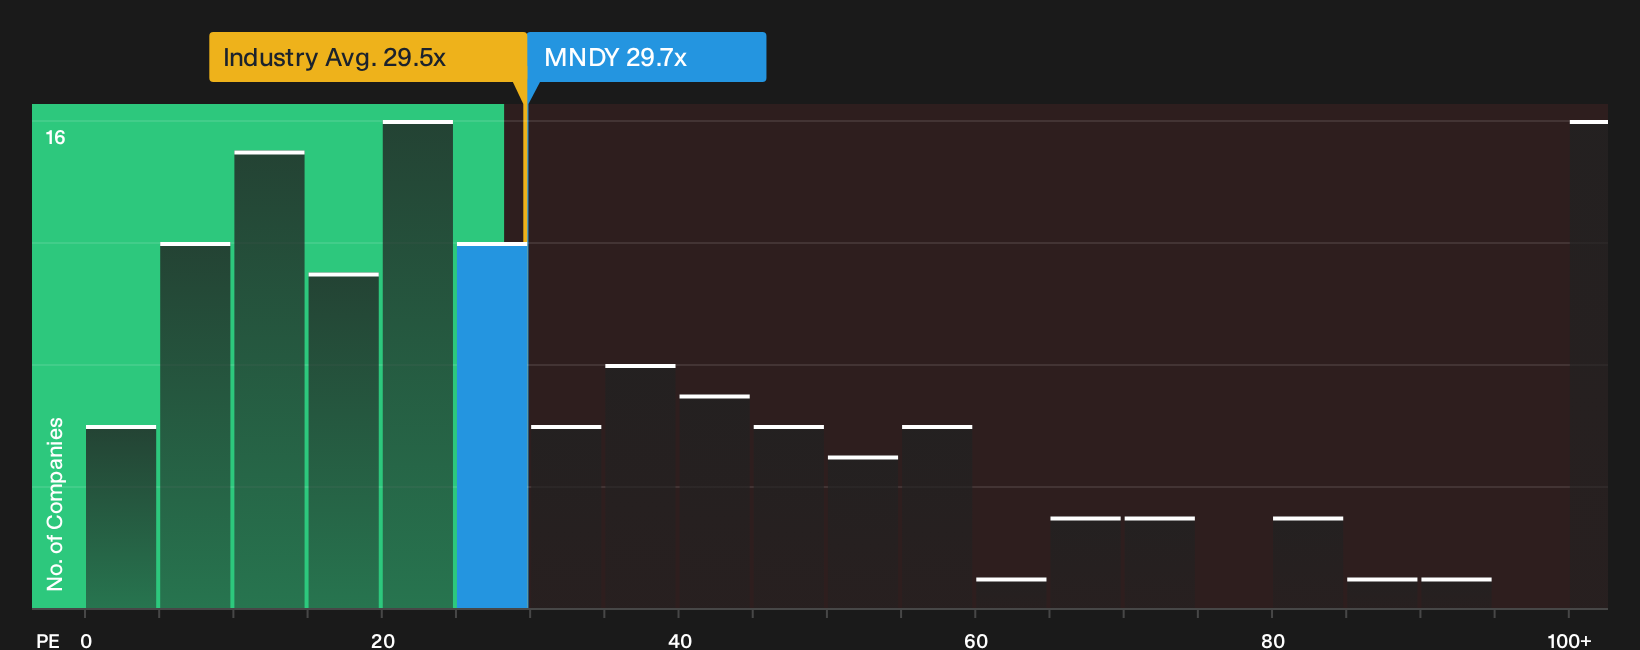
The P/E ratio can be a useful shorthand for monday.com because the business is already producing positive earnings. On this measure, the stock trades on roughly 29.7x, which is very close to the wider Software sector average of about 29.5x. Against a typical peer basket on roughly 40.8x, that level looks more restrained than some of the faster priced software names.
The Fair Ratio model, which adjusts the expected P/E for monday.com's growth profile, margins, risk and size, suggests investors might usually expect a higher multiple than where the shares currently trade. That puts the stock at a discount on this earnings yardstick rather than screening as aggressively priced. For anyone weighing the recent share price slide against current profitability, the question is whether the business fundamentals justify that lower P/E or whether the gap to this tailored benchmark points to some degree of undervaluation on current earnings power. Explore the numbers behind monday.com's P/E valuation.
The monday.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for monday.com pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today’s price. Each narrative links its number to a specific view on how monday.com's expansion, profitability and risk profile could evolve, giving you something concrete to revisit as new information comes through.
One of the top community narratives on monday.com: 21% undervalued
"Rapid integration of generative AI and low-code or no-code capabilities enable broader automation and workflow customization, strengthening platform differentiation and stickiness..."
Discover why this Narrative puts monday.com at 21% undervalued.
One more angle on monday.com that could change the story
Before you form a view on monday.com, it is worth asking who is steering the ship and how their rewards line up with your interests. See who runs monday.com and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com