


UK Luxury Stocks With ESG Strength After The Harrods Fallout
Allegations around Harrods and the potential for up to £150m in compensation claims have put a harsh spotlight on how luxury brands handle historic misconduct. For investors, that opens a window to reassess which UK consumer stocks treat governance and social risk as more than a press release. This article walks through three ESG screened luxury and consumer leaders exposed to the same headlines, and explains why their responses might matter for your portfolio decisions.
The three UK stocks below are a starting sample, and the full ESG screen on Simply Wall St surfaced 7 more luxury and consumer companies with equally compelling narratives that are not covered here. To identify and analyze the highest conviction opportunities in this theme, head straight into the ESG Leaders in Global Luxury and Consumer Brands screener.
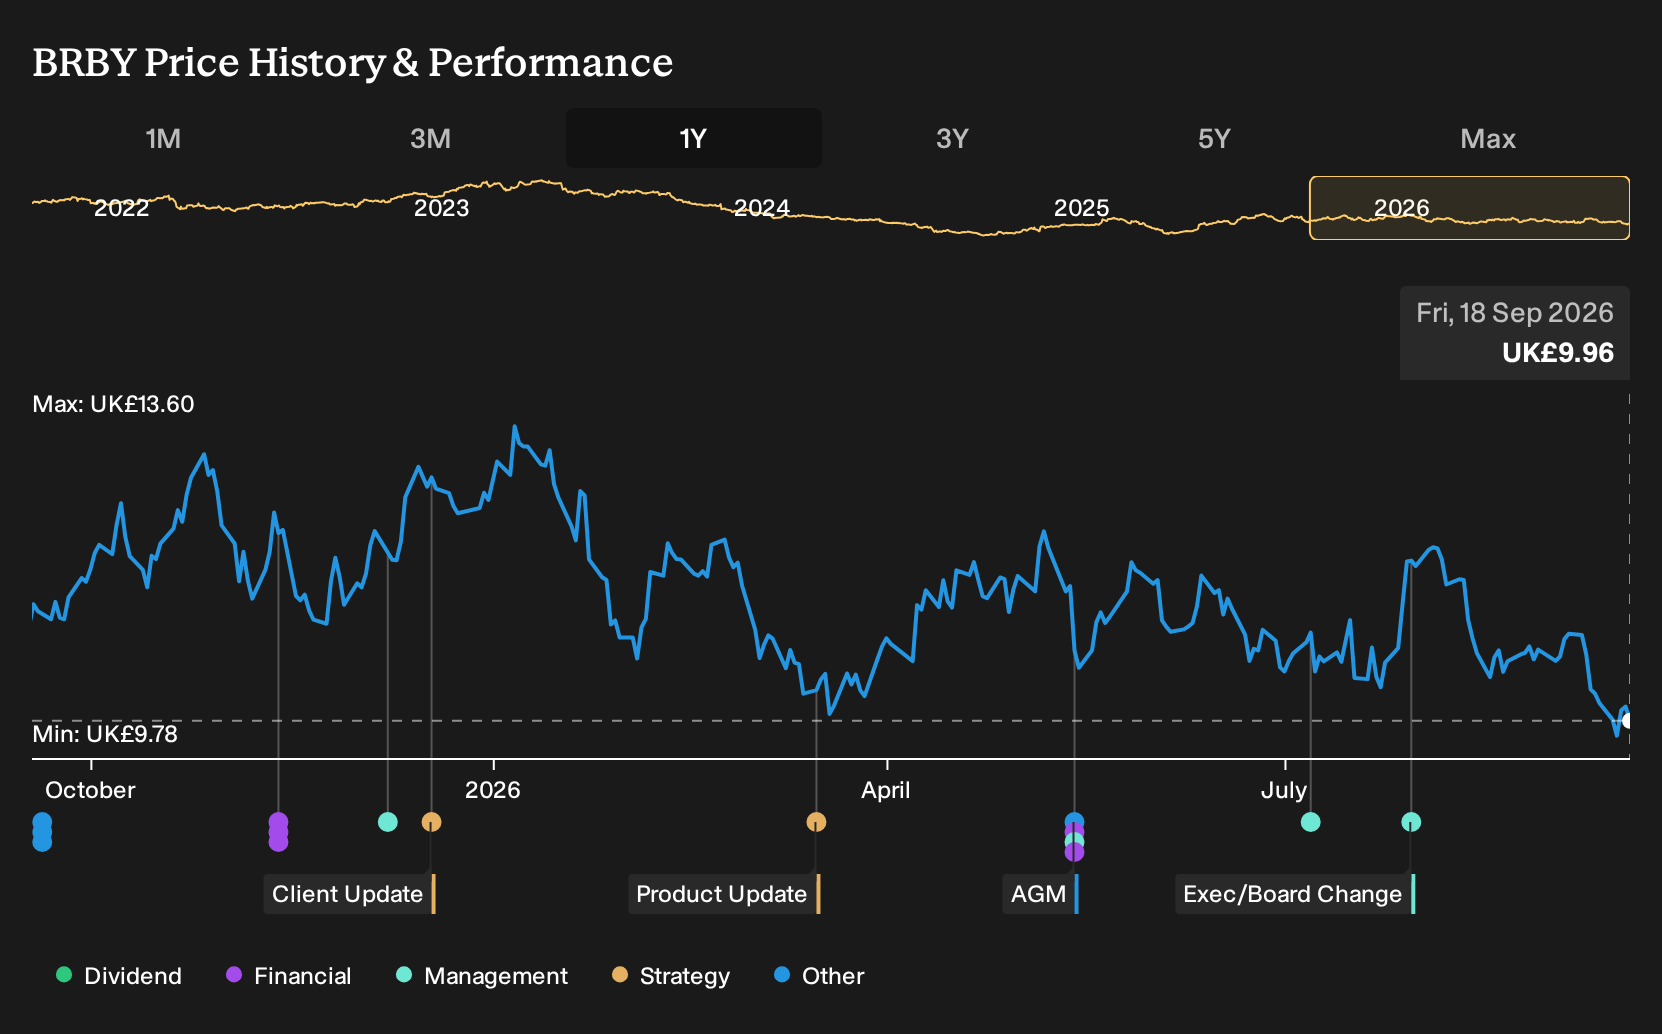
Burberry Group (LSE:BRBY)
Overview: Burberry Group is a London based luxury fashion house selling high end clothing, accessories and beauty products worldwide, with brand reputation central.
Operations: Burberry generates about £2.4b from Retail/Wholesale and £62 million from Licensing, with Mainland China and the United States key regional contributors.
Market Cap: £3.6b
Burberry Group fits this ESG luxury theme as a listed British heritage brand where board oversight, workforce culture, and reputational safeguards are business critical in light of the scrutiny triggered by cases like Harrods.
"Burberry is positioned to monetize consumer demand for ethical and sustainable luxury, with scalable in-store circularity initiatives and a deepened commitment to UK manufacturing that may support pricing, help attract ESG-oriented customers, and contribute to both gross margin and brand goodwill over time."
What really decides the punchline for Burberry is how one unresolved pressure feeds through to future pricing power and margin resilience.
That pricing question is exactly what runs through the full narrative for Burberry Group, revealing where Burberry Group’s brand strength may be masking risk and accelerating upside potential.
Watches of Switzerland Group (LSE:WOSG)
Overview: Watches of Switzerland Group is a luxury retailer selling high end watches and jewelry in the UK and US, fitting the ESG luxury theme.
Operations: The group reports £900.7 million from UK and Europe retail, £810.5 million from US retail, and £126.9 million from US wholesale.
Market Cap: £1.5b
Watches of Switzerland Group matters here because it connects ESG screened governance with front line client service in some of the most sensitive corners of luxury retail, where reputational slip ups can quickly undermine years of work building trusted relationships.
"Primary risk, Rolex vertical integration. Despite the geographical hypothesis outlined above, this remains the key binary risk."
What really moves the dial for Watches of Switzerland Group is how one quiet shift in its partner relationships ultimately filters into long term margins.
That inflection point on margins is exactly what the full narrative for Watches of Switzerland Group untangles, showing where Rolex risk might be masking accelerating opportunity in Watches of Switzerland Group.

PZ Cussons (LSE:PZC)
Overview: PZ Cussons is a Manchester based consumer goods group selling baby, beauty and hygiene brands to households across Europe, Africa and Asia Pacific.
Operations: The group earns about £176 million from Asia Pacific, £202 million from Europe and the Americas, and £168 million from Africa.
Market Cap: £407 million
PZ Cussons matters for this ESG luxury and consumer screen because its baby and beauty labels put brand trust, governance and workforce culture directly in the spotlight when investors are weighing reputational risk after the Harrods headlines.
"Accelerating e-commerce and digital engagement in Indonesia and other core markets, including live streaming and platform partnerships, is expected to support sustained volume growth and premiumisation in baby and personal care, which in turn may lift group revenue and gross margin over time."
What could really reshape the PZ Cussons story is how one hard to see shift in pricing power ultimately flows through to profit quality.
If that pricing shift is what interests you, the full narrative for PZ Cussons explains how e-commerce momentum, brand trust and ESG pressures could be subtly influencing PZ Cussons’ potential upside profile.

Seeking Alternatives Before The Crowd Moves
Fresh breakout themes move quickly and the best ideas rarely stay under the radar for long. Before momentum really starts flying and entry points get caught, act now.
- Catch early strength in cash rich compounders by scanning a curated 10 high quality undervalued stocks while valuations and balance sheets still look compelling enough to build a watchlist.
- Ride the next wave of machine learning infrastructure demand by tracking curated 88 AI infrastructure stocks before capital floods in and crowds the opportunity set.
- Target resilient yield while prices are still dropping into attractive ranges by reviewing hand picked 1 dividend fortresses built for investors who want income with defense.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com