


Martin Marietta Materials (MLM) Could Be 26% Below Fair Value After Record Q2
What Triggered the Latest Move in Martin Marietta Materials?
Martin Marietta Materials (MLM) reported record Q2 revenue and Adjusted EBITDA and raised full year revenue guidance, yet the share price has retreated since that earnings release.
Over the past few months, Martin Marietta Materials has seen momentum cool, with the share price down 8.28% over 30 days and 22.67% year to date. However, the 5 year total shareholder return of 44.14% still reflects a much stronger longer term journey.
Scan beyond Martin Marietta Materials and see how other building and infrastructure suppliers are priced right now with our curated 39 power grid technology and infrastructure stocks
Bulls point to record Q2 figures and raised guidance. Bears focus on the sharp pullback in Martin Marietta Materials despite that strength. Which side does the valuation now support?
Most Popular Narrative: 26% Undervalued
Martin Marietta Materials last closed at $490.64, while the most followed narrative anchors fair value at $662.65 using an 8.34% discount rate. That gap sits alongside a story built around infrastructure demand, acquisitions and margin assumptions.
Ongoing adoption of advanced cost management, digital tools, and operational efficiency measures, evidenced by record improvements in gross and EBITDA margins, are likely to deliver sustained net margin expansion and higher profitability, even through cyclical slowdowns. The acquisition of Premier Magnesia broadens Martin Marietta's magnesia product platform, providing higher-margin, cycle-resilient cash flows and new revenue streams that complement the core aggregates business, supporting greater earnings resilience and long-term EPS growth.
See why 10 investors see Martin Marietta Materials as 26% undervalued.
Result: Fair Value of $662.65 (UNDERVALUED)
Still, if government infrastructure budgets tighten or construction demand weakens for longer, the upbeat Martin Marietta Materials narrative could unravel quickly.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: Multiples Paint a Pricier Picture for Martin Marietta Materials
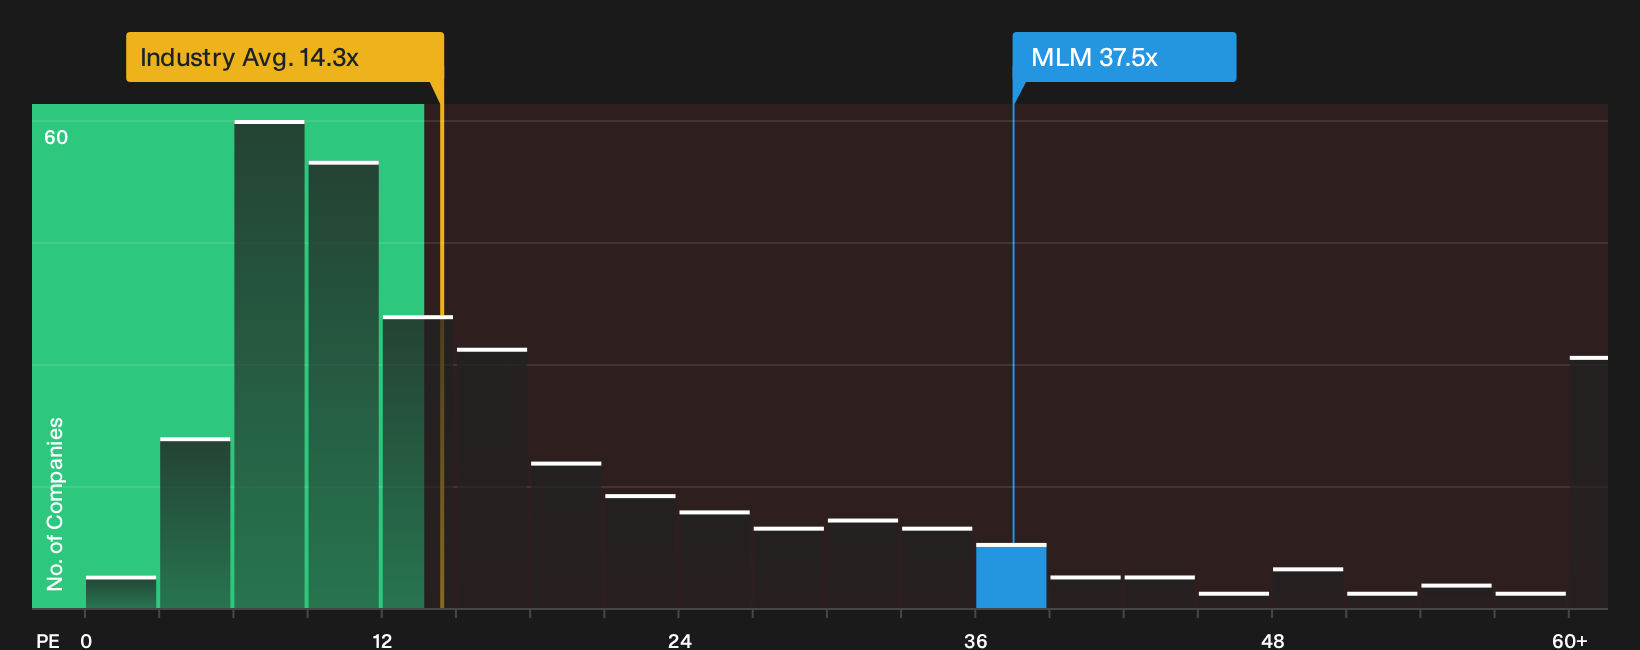
The crowd narrative pegs Martin Marietta Materials as undervalued, yet the P/E story cuts the other way. The stock trades on 37.5x earnings, while the global Basic Materials group averages 14.3x and the fair ratio sits at 27x. That rich gap suggests valuation risk if expectations cool, so which signal do you trust more right now?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Martin Marietta Materials is split, with confident bulls on one side and cautious skeptics on the other. Review the numbers, assess the moving parts, and weigh both downside threats and upside potential with the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Martin Marietta Materials?
If Martin Marietta Materials has your attention, do not stop there. Fresh opportunities often sit one click away when you widen the search across quality watchlist candidates.
- Target potential mispricings early and scan for quality companies trading at compressed valuations through the Simply Wall St screener built around 33 high quality undervalued stocks.
- Strengthen your defensive side by reviewing a curated 30 resilient stocks with low risk scores that aims to highlight businesses with more resilient profiles.
- Hunt for future leaders before the crowd by checking a hand picked 16 high quality undiscovered gems that filters for strong fundamentals hiding in plain sight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com