


ExxonMobil Holdings (XOM) Valuation In Focus After Morgan Stanley Conference Commentary
ExxonMobil Holdings (XOM) is back in the spotlight after management appeared at Morgan Stanley's 14th Annual Laguna Conference on 15 September, giving investors fresh commentary on refining, supply chains and capital returns.
Viewed against that backdrop, ExxonMobil Holdings’ recent share price has cooled a little in the very short term, with a 7 day share price return of 1.48% lower and a 30 day share price return of 0.95% lower. However, the 90 day share price return of 18.11% and year to date share price return of 33.34% point to strong upward momentum that aligns with refining tightness, capital returns and the company’s prominence in recent sector commentary. A 1 year total shareholder return of 49.16% and 5 year total shareholder return of 238.37% underline how income and buybacks have amplified gains for long term holders.
Scan ExxonMobil Holdings alongside other income-focused energy plays that show strong cash generation and balance sheet support with a curated list of 6 dividend fortresses.
The latest swing in ExxonMobil Holdings highlights a tension between real cash generation from refining and the mood music around energy risk. To weigh those forces properly, the next step is to test the valuation.
Most Popular Narrative: 4% Undervalued
Against ExxonMobil Holdings’ last close of $163.54, the most followed narrative anchors fair value at $169.91, so the market is pricing in a modest discount that still needs the underlying cash story to hold up.
Industry-wide underinvestment in new hydrocarbon production is tightening supply. This, combined with Exxon's scale and execution of high-return projects, positions the company to benefit from higher sustained oil and gas prices, supporting earnings and cash flow. Ongoing operational efficiency initiatives and digital transformation, including advanced use of AI, automation, and a unified ERP, are lowering structural operating expenses. This supports net margins and enhances earnings stability through commodity cycles.
See why 333 investors see ExxonMobil Holdings as 4% undervalued.
Result: Fair Value of $169.91 (UNDERVALUED)
Still, the ExxonMobil Holdings story could change if decarbonization policies affect long term oil demand faster than expected or if low carbon projects fail to gain traction.
Find out about the key risks to this ExxonMobil Holdings narrative.
Another View On ExxonMobil Holdings Valuation
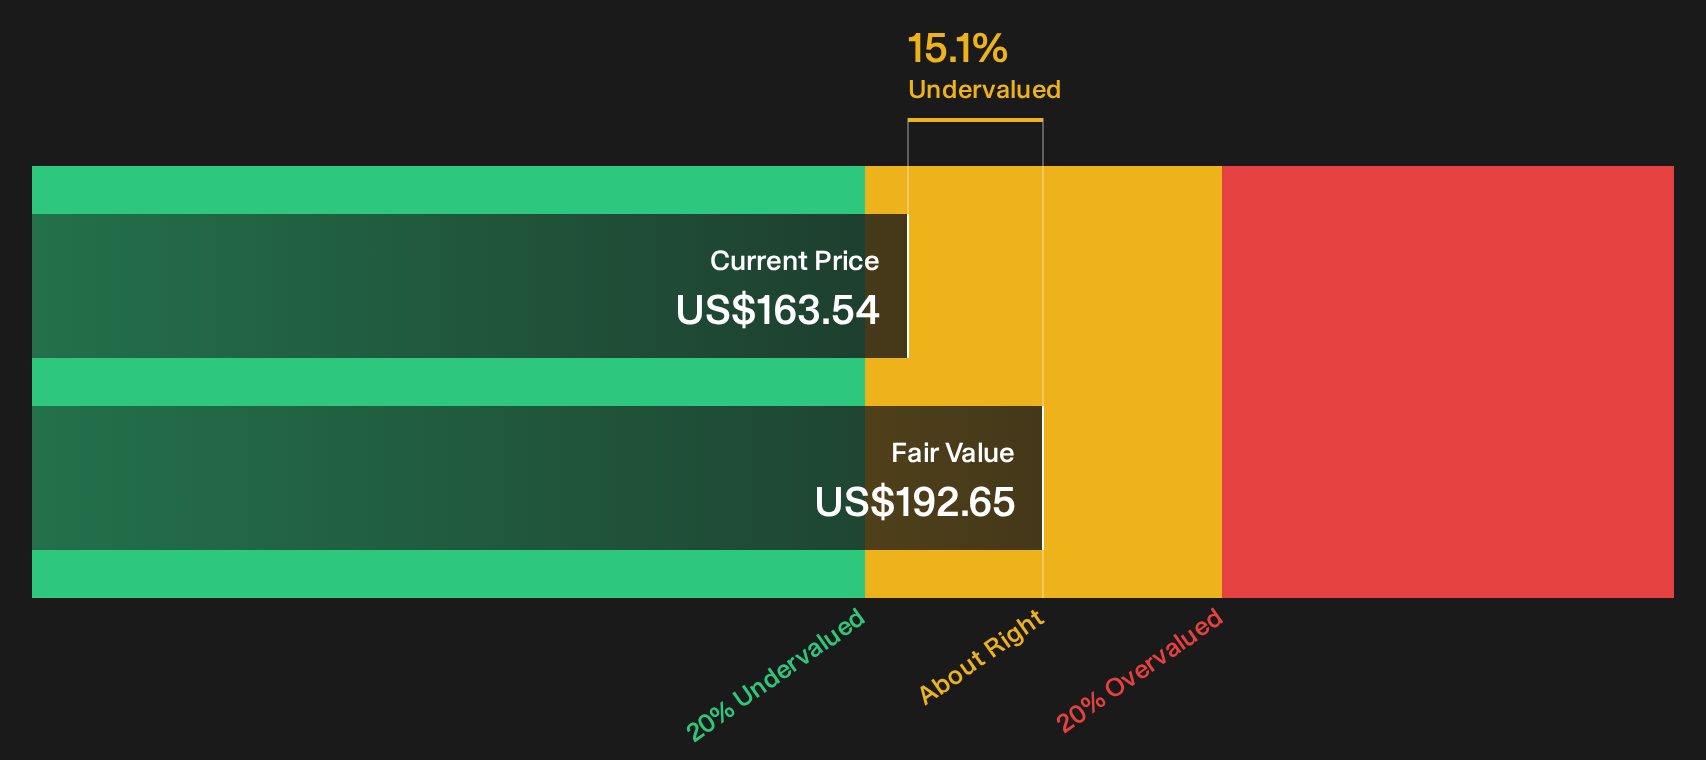
Our DCF model presents a different perspective on ExxonMobil Holdings. The narrative fair value sits at $169.91 and implies modest undervaluation. The future cash flow estimate comes in higher at $192.65, which frames the current $163.54 price as a deeper discount. Which version of value do you trust more when real cash flows are on the line?
For investors who want to see how this cash flow view is built step by step, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If you feel the ExxonMobil Holdings story is tilting in one direction but want to test the optimism yourself before it changes again, take a closer look at the full breakdown of 4 key rewards
Looking for more investment ideas beyond ExxonMobil Holdings?
If ExxonMobil Holdings has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not chasing the next move after it has already played out.
- Target resilient potential with a 30 resilient stocks with low risk scores that focuses on businesses aiming to keep drawdowns and financial stress in check.
- Hunt for possible bargains through a 33 high quality undervalued stocks that filters for solid cash generation, reasonable balance sheets and prices that lag underlying fundamentals.
- Spot early movers using a 8 elite penny stocks with strong financials that isolates smaller, higher risk companies where even modest fundamental shifts can matter a lot.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com