


Is Borr Drilling (BORR) Fully Valued After Its Latest Contract Wins?
Borr Drilling (BORR) is back in focus after a cluster of contract wins and extensions, including fresh work for the Odin in the US, Idun in Vietnam, and Bestla in Europe.
Recent contract wins appear to be feeding into sentiment, with Borr Drilling’s 1-day share price return of 2.29% and 7-day share price return of 4.45% pointing to building short-term momentum. At the same time, the 1-year total shareholder return of 51.19% contrasts with a declining 3-year total shareholder return of 31.19% and a very large 5-year total shareholder return that sits near 3x. This suggests investors are reassessing both growth prospects and risk after the Odin, Idun and Bestla updates.
Spot similar contract driven momentum beyond Borr Drilling by scanning our hand picked 39 power grid technology and infrastructure stocks, which is poised to benefit from heavy energy and infrastructure demand.Fresh contracts, a mixed return record, and Borr Drilling sitting near analysts’ targets all pull in different directions. Does it make more sense to step in after this latest move or wait for a cleaner entry on valuation?
Most Popular Narrative: 6% Undervalued
Borr Drilling last closed at $4.46, while the most followed narrative anchors fair value at $4.76. This frames the recent contract momentum as only a modest discount rather than a deep value gap.
The valuation seems to price in that Borr Drilling's strong recent contract momentum, particularly in Mexico, the Middle East, and Southeast Asia, will translate into persistently high day rates and utilization. This view may underestimate the lingering risks from oversupply in the jack up market and the increased volume of transitional or short duration contracts, which could compress both future revenues and margins if the anticipated demand does not fully materialize.
See why 8 investors see Borr Drilling as 6% undervalued.
Result: Fair Value of $4.76 (UNDERVALUED)
Still, analyst assumptions around steady jack up demand and higher future profit margins could be tested if oversupply persists or if environmental rules tighten faster than expected.
Find out about the key risks to this Borr Drilling narrative.
Another Take On Borr Drilling’s Valuation
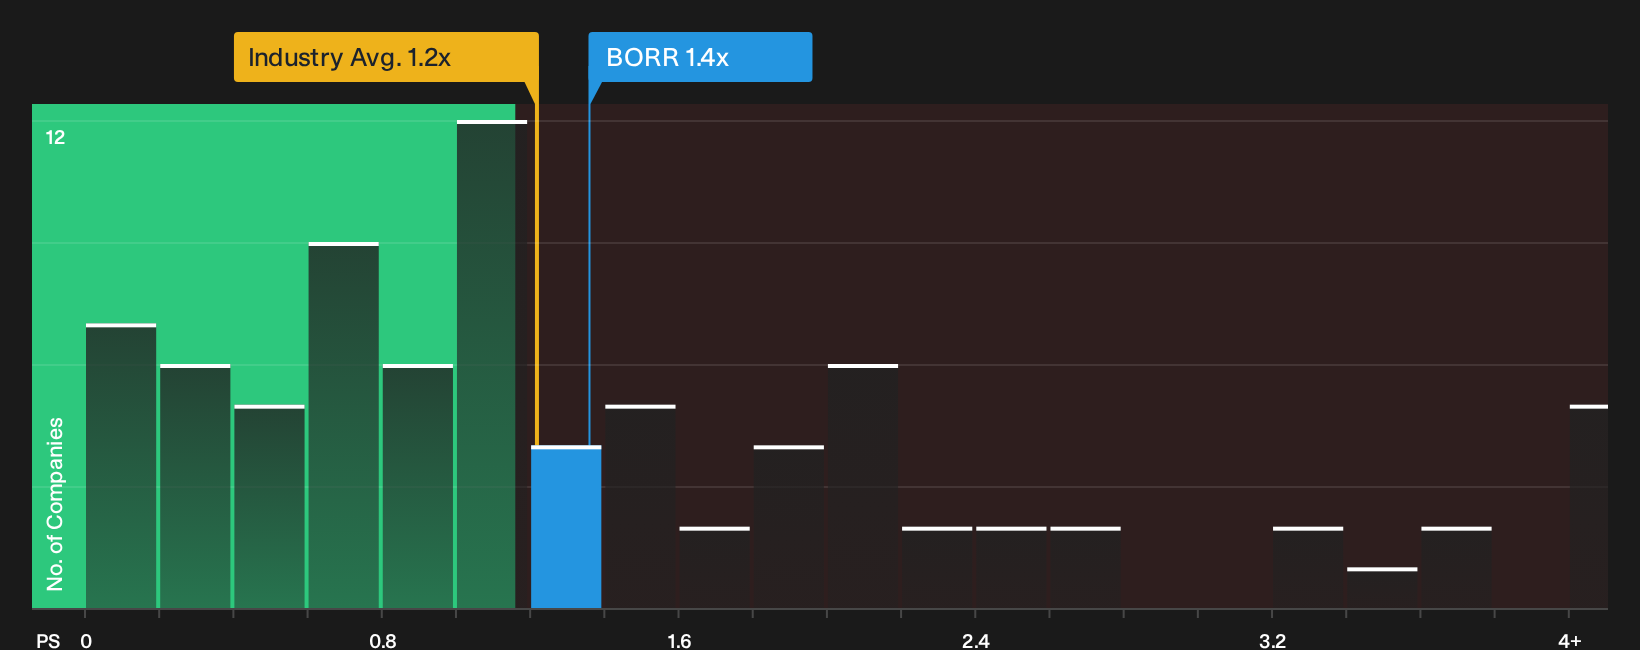
The earlier view framed Borr Drilling as modestly undervalued using analyst targets and earnings assumptions. Using a simpler sales based yardstick tells a different story. At a P/S of 1.4x versus 1.2x for the US Energy Services group and 1.1x for peers, the stock looks comparatively expensive despite matching its 1.4x fair ratio. That mix points to limited margin of safety if sentiment cools, so how comfortable are you paying a premium for a business that is still loss making today?
For a plain language breakdown of what this pricing gap might mean in practice, including how that P/S premium could evolve if sector conditions change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment on Borr Drilling feels mixed after these contracts and valuation checks, consider taking action quickly and stress testing the upside drivers yourself with the 2 key rewards
Looking for more Borr Drilling style investment ideas?
Do not let your research stop with Borr Drilling. Broaden your watchlist now using these focused screens so you do not miss the next opportunity.
- Target deep value potential by scanning companies that currently screen as 33 high quality undervalued stocks.
- Strengthen your defense by focusing on businesses with resilient finances using the list of solid balance sheet and fundamentals (23 results).
- Hunt for earlier stage opportunities by reviewing a curated set of 8 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com