


3 Stocks to Watch as US China Tariffs Shift Global Manufacturing
Tariffs between the US and China are quietly rewiring global supply chains, and upstream industrial suppliers are sitting close to the action. These businesses feed the factories that feed the world, so even subtle shifts in trade policy can redirect big flows of orders and capital. If you care about where production might move next, this is where to look. This article discusses three stocks exposed to these tariff shocks and explains how each one could matter for your portfolio decisions.
The stocks covered below are just a sample from this tariff exposed theme, and the full screen surfaced 64 more global upstream industrial suppliers with equally compelling stories that are not included here. To identify, compare, and analyze the highest conviction ideas in this niche, head straight into the Global Upstream Industrial Suppliers to US and Chinese Manufacturers screener.
Elite Material (TWSE:2383)
Overview: Elite Material produces copper clad laminates and related electronic materials for printed circuit boards used across global electronics manufacturing.
Operations: Elite Material reports about NT$135.7b from foreign departments and NT$23.1b domestically, with China contributing NT$104.4b of revenue.
Market Cap: NT$1,752.2b
Elite Material fits directly into the screener theme as a large upstream supplier of PCB substrates feeding electronics production in Taiwan, China, and other regions. Tariff shifts are pushing some orders toward alternative hubs, and this upstream heavyweight already has a diversified footprint across those supply chains. This positioning makes margins and pricing especially sensitive to changes in pressures on input demand.
This sensitivity to demand is exactly why it helps to see the full picture through the 4 key rewards and 2 important warning signs (1 is major!), before tariff pressure resets Elite Material's pricing power.

Cabot (CBT)
Overview: Cabot is a specialty chemicals business that supplies reinforcing carbons and performance additives used as upstream inputs across global manufacturing.
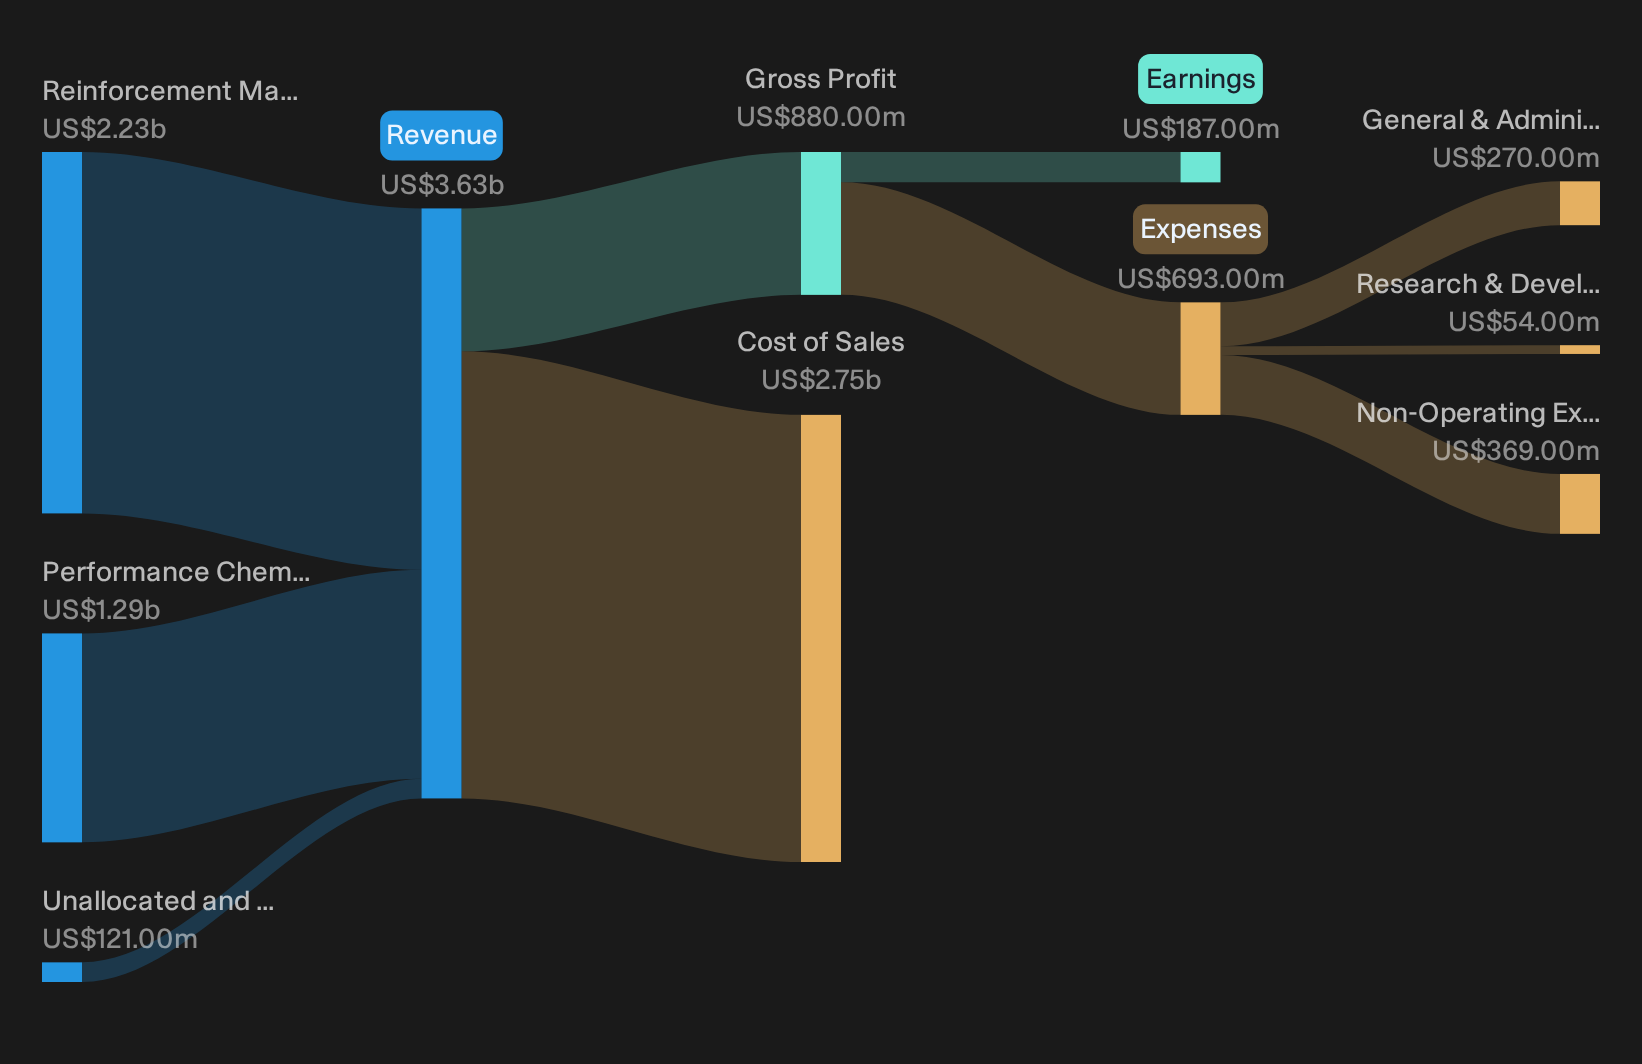
Operations: Cabot generates US$2.2b from Reinforcement Materials and US$1.3b from Performance Chemicals, with revenue diversified across the Americas, Asia Pacific, and EMEA.
Market Cap: US$4.0b
Cabot matters for this upstream suppliers theme because its reinforcing carbons and specialty additives sit at the point where tariffs and manufacturing shifts can quietly reshape demand patterns.
"The rapid build-out of global battery capacity and data center related battery energy storage systems is heavily concentrated in China and other highly competitive regions, which could pressure pricing for Cabot's conductive additives and reduce future revenue growth and EBITDA contribution from Battery Materials."
What really moves the needle for Cabot now is how a single unresolved pressure on its pricing power filters through to margins.
That pricing squeeze is only part of the story, and the full narrative for Cabot shows how Cabot could still accelerate if pricing and demand eventually decouple.
Yageo (TWSE:2327)
Overview: Yageo manufactures passive electronic components and related parts that feed into electronics, industrial equipment, autos, and communications gear worldwide.
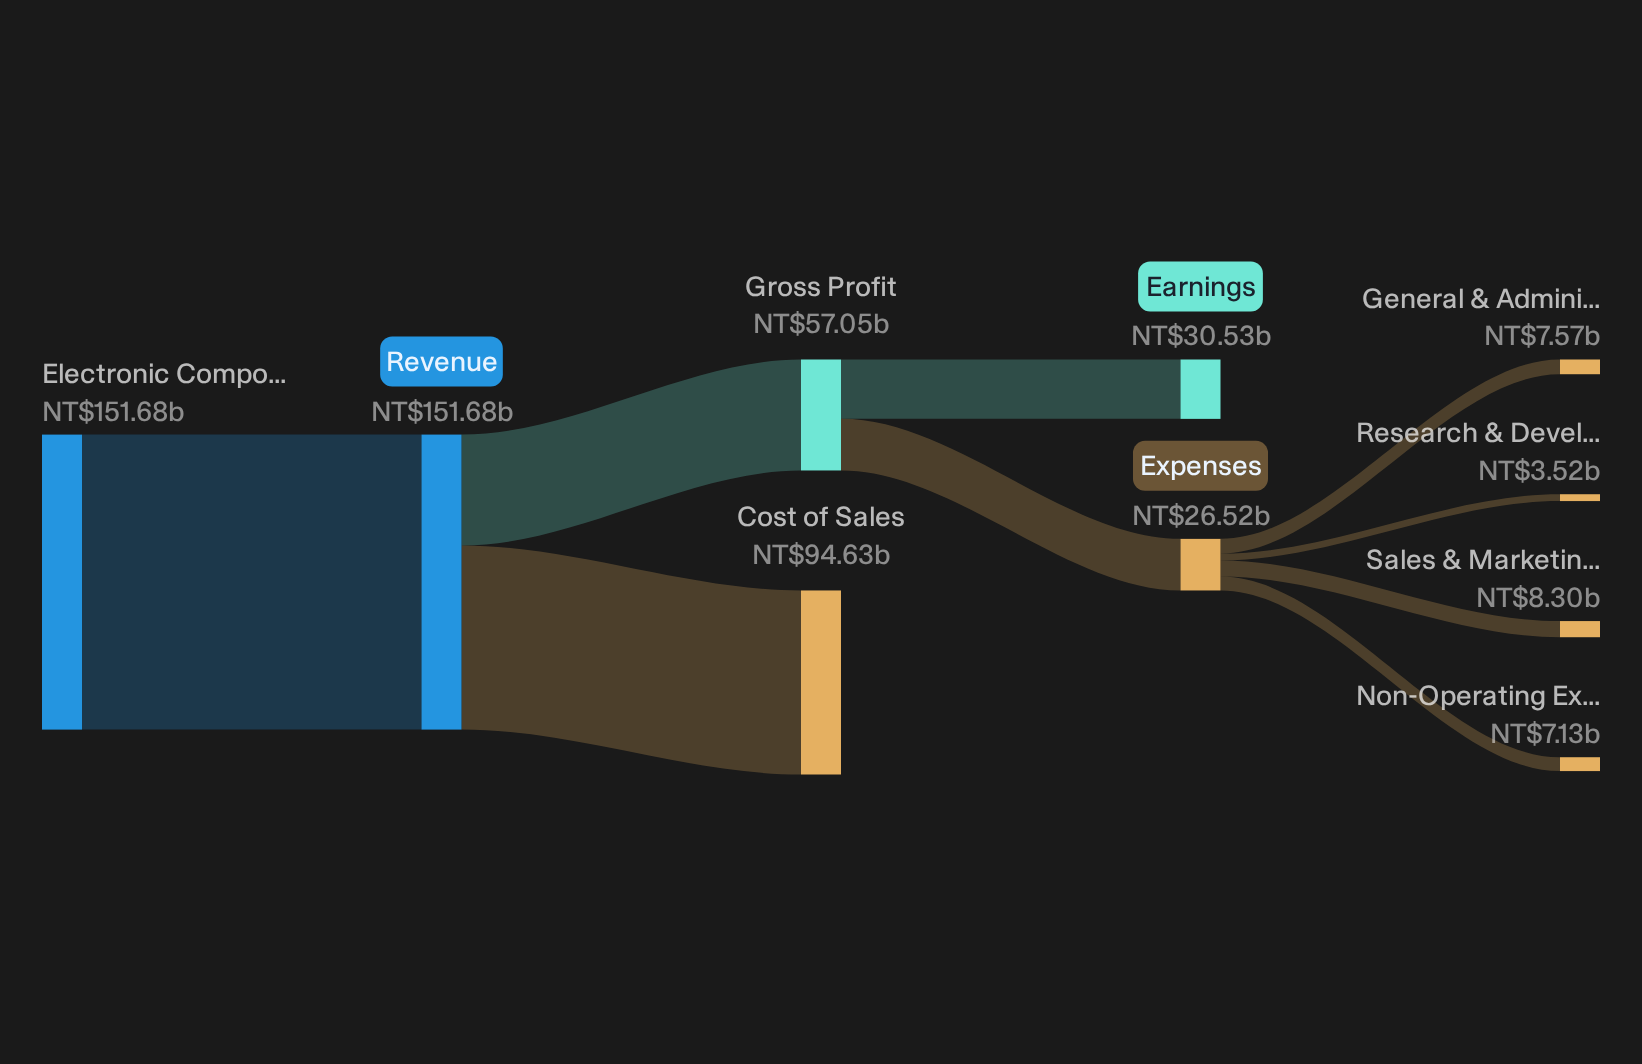
Operations: Yageo reports NT$151.7b of revenue from Electronic Components & Parts, reflecting a broad footprint across global manufacturing supply chains.
Market Cap: NT$1,130.2b
For this tariff focused upstream screen, Yageo matters because its capacitors, resistors, and inductors are basic building blocks for electronics production across China, the US, Europe, and the rest of Asia. Trade driven shifts in where factories run their lines can ripple quickly into its order book.
"Yageo is strategically positioned to benefit from growth in computing and enterprise segments, particularly through its MLCC, tantalum polymer capacitors, and inductors, which are increasingly used in AI servers and applications. Persistent weakness in the industrial sector, particularly in Europe, poses risk to net income as the segment is a significant contributor to Yageo’s sales mix."
What really matters for Yageo now is how one quiet swing in end market demand ultimately filters into pricing power and profit resilience.
Those cross currents in profit resilience are exactly what the full narrative for Yageo unpacks in detail, surfacing where Yageo’s AI demand and industrial softness could decisively diverge.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. When the next breakout gathers momentum, the early money is already flying while latecomers get caught chasing drops. Scan these under the radar lists and consider your options.
- Spot resilient compounders before the crowd by reviewing a curated 226 resilient stocks with low risk scores built to highlight businesses that hold up when volatility starts biting.
- Track early AI momentum where profits already show up on the income statement by scanning the hand picked 38 profitable AI stocks that aren't just burning cash before valuations move ahead of fundamentals.
- Rotate into cash generators with pricing power by reviewing a focused 179 high quality undervalued stocks that filters for quality balance sheets and robust free cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com