


Revenue Growth Outlook Might Change The Case For Investing In Novanta Stock (NOVT)
- Recent coverage of Novanta highlights multi-year revenue growth of 10.7% and a 44.4% gross margin, with commentators focusing on expectations for stronger demand and revenue momentum across its precision technologies.
- An interesting angle is how those high margins and perceived market share gains, combined with an active acquisitions pipeline, are renewing attention on Novanta’s ability to convert advanced sensing and motion products into long-term, higher quality revenue.
- We will now examine how Novanta's investment narrative could be influenced by this renewed focus on its revenue growth and demand outlook.
Scan beyond Novanta and compare its revenue momentum and margin story with a curated 33 high quality undervalued stocks that could be pricing in similar quality at a different entry point.
Novanta Investment Narrative Recap
To own Novanta, you need to believe that its precision medicine, automation, and medical solutions businesses can turn current revenue momentum and 44.4% gross margins into more consistent, higher quality earnings. The recent focus on stronger demand expectations supports that thesis, but it does not remove the reality that organic growth guidance around flat to low single digits leans heavily on acquisitions.
The near term swing factor is execution on manufacturing regionalization and cost actions while keeping robotics, warehouse automation, and advanced surgery wins on track. The biggest risk is that weak Precision Medicine and Manufacturing demand, trade friction with China, or integration hiccups in acquired units slow that transition and keep margins under pressure.
With no fresh company specific announcements tied directly to this recent commentary, the most relevant reference point is still management’s emphasis on robotics and automation contracts, such as the cited US$50 million warehouse robotics deal and design wins in physical AI. These orders are a practical bridge between today’s order book and the growth investors are being asked to underwrite.
For you, the question is whether that pipeline can offset softer areas like Precision Medicine while Novanta absorbs restructuring costs from plant moves and tariff workarounds. Stronger high margin automation revenue can help, yet dependence on external borrowing, high P/E multiples, and one off items in past earnings keep execution risk firmly in view.
Analysts expect Novanta to reach US$1.7b in revenue and US$168.2 million in earnings by 2029, based on assumed yearly revenue expansion of 17.1%. That projection implies an earnings increase of about US$106.4 million from US$61.8 million today to the 2029 consensus figure.
Uncover why Novanta's fair value indicates a 46% potential upside to its current price that could close sooner than many investors expect.
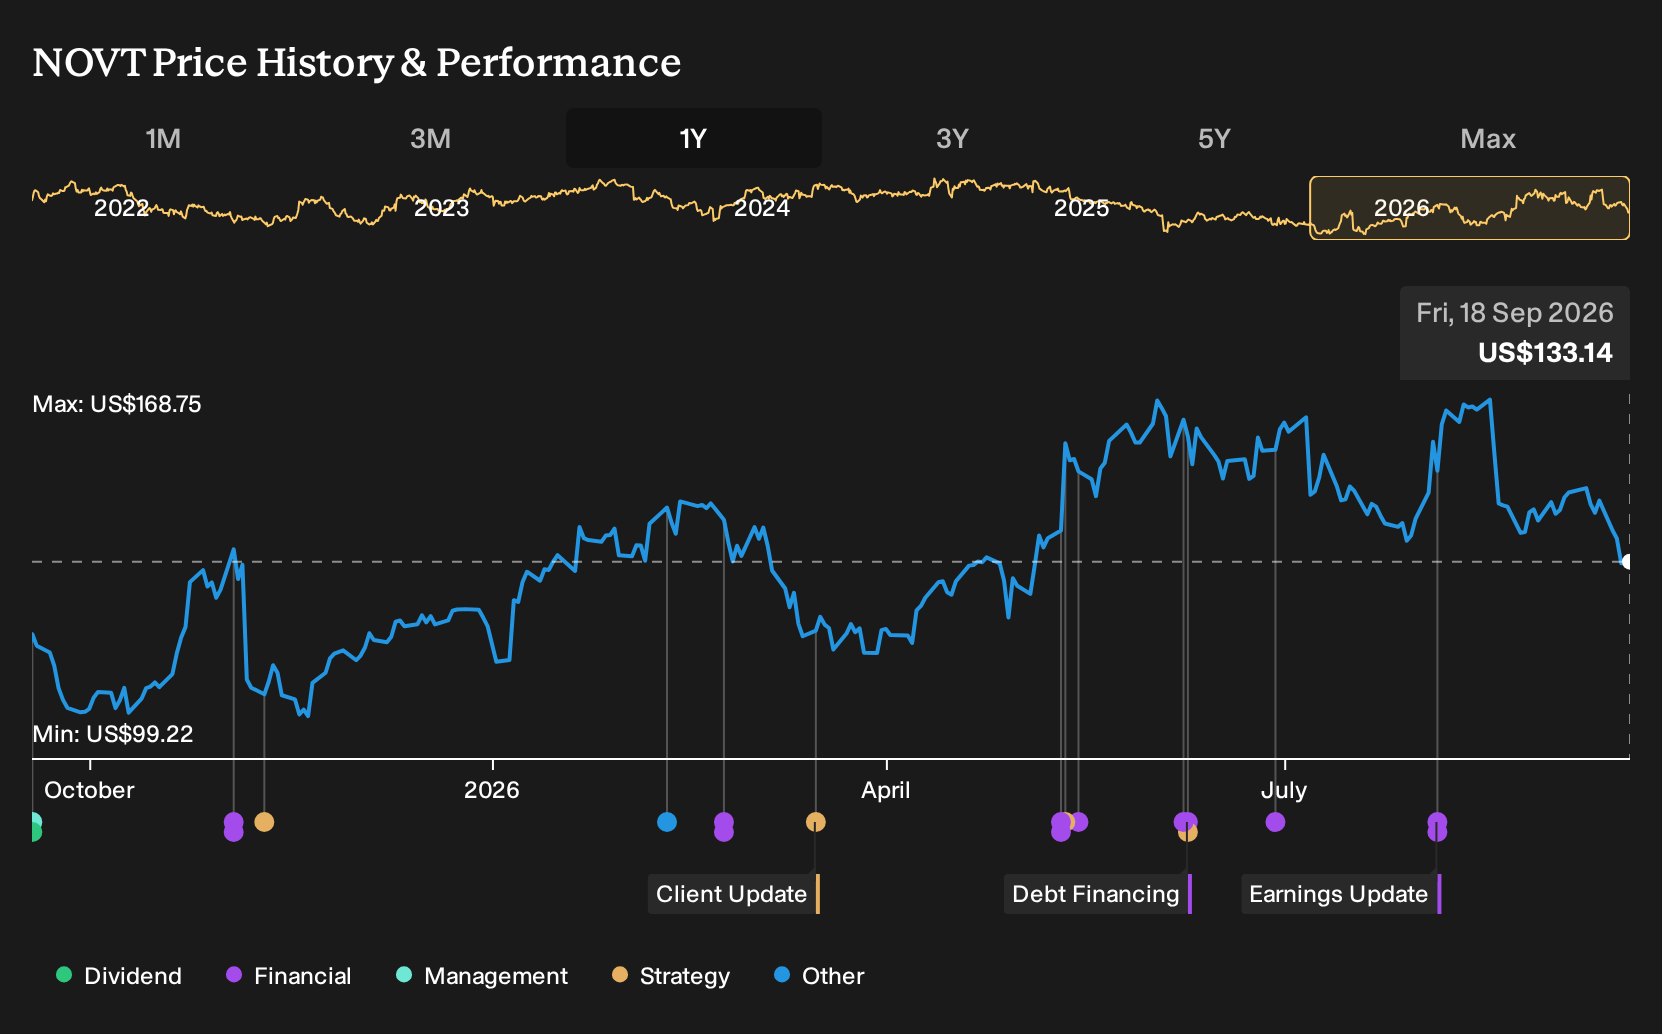
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$44 to almost US$195 per share, which signals wildly different views on Novanta's long term earnings power. When this is set against risks around flat organic growth, China trade exposure, and automation adoption, it results in a wide field of opinion worth exploring.
Explore 2 other Novanta fair value estimates, including one that suggests there may be as much as 46% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Novanta research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novanta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novanta's overall financial health at a glance.
Looking for more investment ideas beyond Novanta?
If the Novanta story has sharpened your sense of what quality looks like, it can help to compare it with other opportunities and test your thesis across different types of businesses.
- For investors who want potential upside without ignoring balance sheet strength, start with a 16 high quality undiscovered gems that may not yet be crowded with attention.
- If capital preservation and steadier profiles matter most to you, filter for a 30 resilient stocks with low risk scores that keeps overall risk scores in tighter check.
- Income focused readers can widen the search to a 6 dividend fortresses that combines 5%+ yields with an eye on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com