


Centerra Gold (TSX:CG) Stock Could Be Undervalued As Earnings Stay In Focus
Centerra Gold has delivered a very strong run over the past few years, which now puts a spotlight on whether the current share price is properly supported by its earnings power. With the stock closing at C$32.24, the key issue for you is how much of that track record is already reflected in the multiple investors are paying today.
- Over the past 3 years, Centerra Gold has returned about 386.7%, which raises the question of how closely its earnings profile lines up with that kind of share price performance.
- The business depends heavily on converting its mining output into consistent profit, so the stability and timing of those earnings can shape how justified the current P/E looks against the Fair Ratio benchmark.
- Your read on Centerra Gold is one view; the desks covering it have another. See what analysts think Centerra Gold's shares could be worth.
The issue now is whether the earnings that Centerra Gold generates today, and is expected to produce ahead, are enough to make the current share price look reasonable on this earnings lens.
If you want a second reference point alongside Centerra Gold, a focused stock screen built around 36 elite gold producer stocks can be a useful place to start your next round of research.
Is Centerra Gold Still Cheap on Earnings?
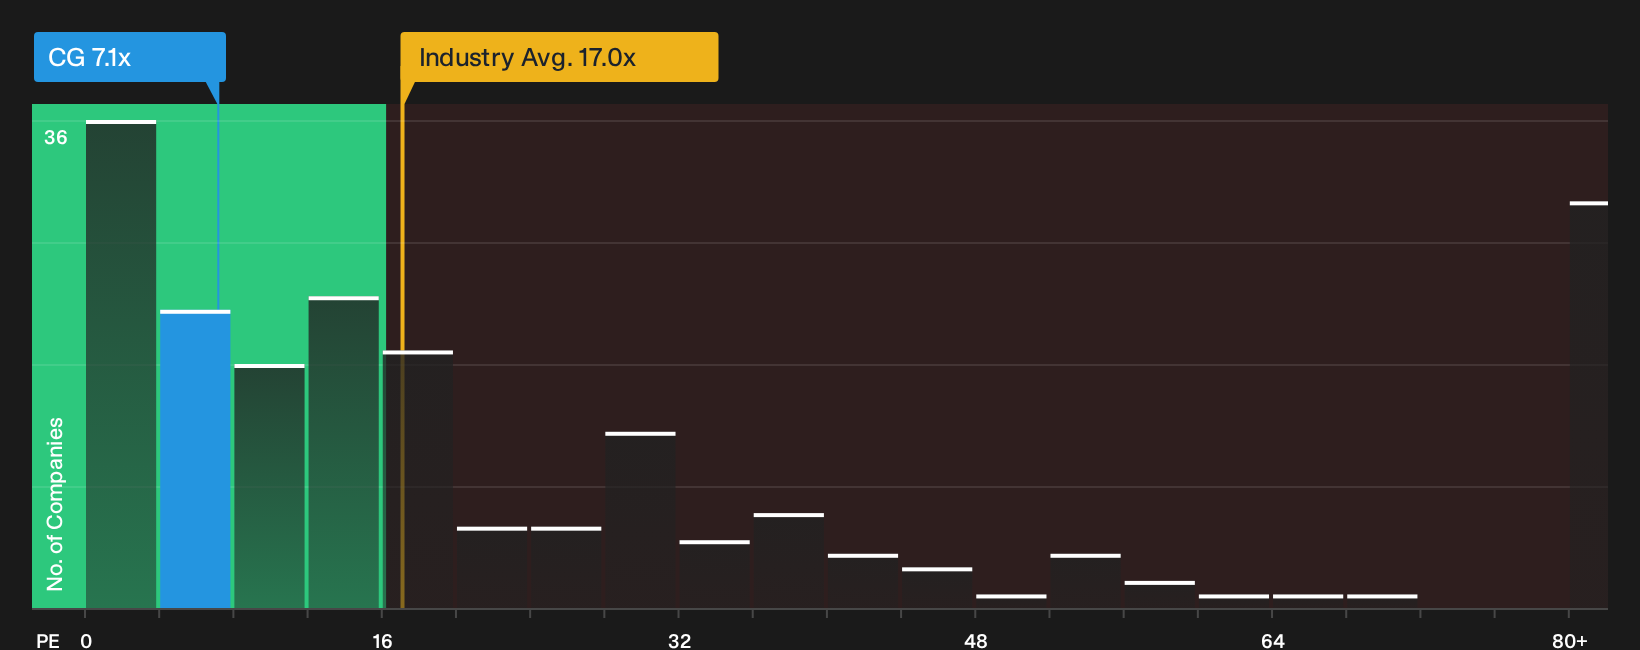
The P/E ratio is a useful lens for Centerra Gold because it links the current share price directly to the earnings that underpin it. On this measure, the stock trades at about 7.1x earnings, which is well below the Metals and Mining industry average of roughly 17.0x and also under the broader peer group at about 13.5x. That gap suggests the market is pricing Centerra Gold more cautiously than many comparable miners despite the recent share price run.
The Fair Ratio model, which looks at factors such as growth expectations, profitability, size and sector risk, points to a higher P/E than where Centerra Gold trades today. The current 7.1x sits below that tailored yardstick, which indicates the market multiple does not fully match what this framework implies for the business. For you as an investor, the key question is whether the earnings quality and risk profile justify that lower P/E, or whether there is room for the share price to better reflect those fundamentals. Explore the numbers behind Centerra Gold's P/E valuation.
The Centerra Gold Narrative: What Would Justify Today's Price?
Narratives for Centerra Gold pick up where the P/E puzzle leaves off by spelling out exactly which paths for growth, margins and earnings would need to play out for the stock to end up worth materially more or materially less than it is today. Instead of a single output from a ratio or model, they lay out the future that number relies on so you can watch how Centerra Gold's actual progress lines up over time.
Community views on Centerra Gold split between those who see more upside in the current project pipeline and those who think expectations already look full.
Bull case: 13% undervalued
"Centerra's near-exclusive focus on de-risked, tier-one jurisdictions like North America and its ability to self-fund all pipeline projects without dilutive equity or high-cost debt sharply reduces risk..."
Discover why this Narrative puts Centerra Gold at 13% undervalued.
Bear case: roughly fairly valued
"High all-in sustaining costs, especially at Oksut and in updated consolidated guidance, leave Centerra vulnerable to margin compression if gold prices soften..."
Explore why this Narrative puts Centerra Gold at roughly fairly valued.
One more Centerra Gold check that belongs beside the P/E
Price and earnings give you one angle on Centerra Gold, but the next piece is how professional analysts currently map out the business a few years from now and how that lines up with what you see today. Explore where analysts expect Centerra Gold to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com