


How Three New ETFs At T. Rowe Price Group (TROW) Have Changed Its Investment Story
- T. Rowe Price Group recently launched three fully transparent actively managed equity ETFs on the NASDAQ, targeting biotech, U.S. small caps, and U.S. mid caps, with expense ratios between 0.47% and 0.59%.
- The new ETFs broaden T. Rowe Price Group’s active ETF shelf across key equity segments, which may support more diversified fee streams and help address competitive pressure from lower cost passive products.
- We will look at how T. Rowe Price Group’s investment narrative intersects with this active ETF expansion, especially the biotech focus.
T. Rowe Price Group Investment Narrative Recap
To own T. Rowe Price Group, you need to believe this asset manager can keep reshaping its product menu fast enough to offset pressure on traditional active funds and fees. The expansion into fully transparent ETFs fits that story but does not on its own resolve persistent net outflow risk or fee compression across the platform.
The key near term swing factor remains whether new vehicles like these ETFs can attract steady assets without cannibalising higher margin products too aggressively. The main risk is that flows keep tilting toward lower fee options faster than T. Rowe Price Group can scale volume, which would squeeze revenue growth and profitability.
The Anthropic partnership is the most relevant adjacent announcement for this ETF push. Management is rolling out Claude, Claude Cowork, and Claude Code across the research and investment organisation, with the aim of giving analysts and portfolio managers more capacity to process information and refine security selection in complex areas such as biotech.
For you as a shareholder, the link is operational. ETF expansion increases product breadth, while AI adoption targets research quality, speed, and efficiency, which can matter for performance and cost control. Execution risk sits in integrating these tools without diluting human judgment. If deployment runs smoothly, it could support both investment outcomes and margin discipline.
T. Rowe Price Group's narrative projects US$8.4b revenue and US$2.6b earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of US$0.6b from US$2.0b today.
Uncover how T. Rowe Price Group's fair value indicates a 6% potential upside to its current price before that discount closes.
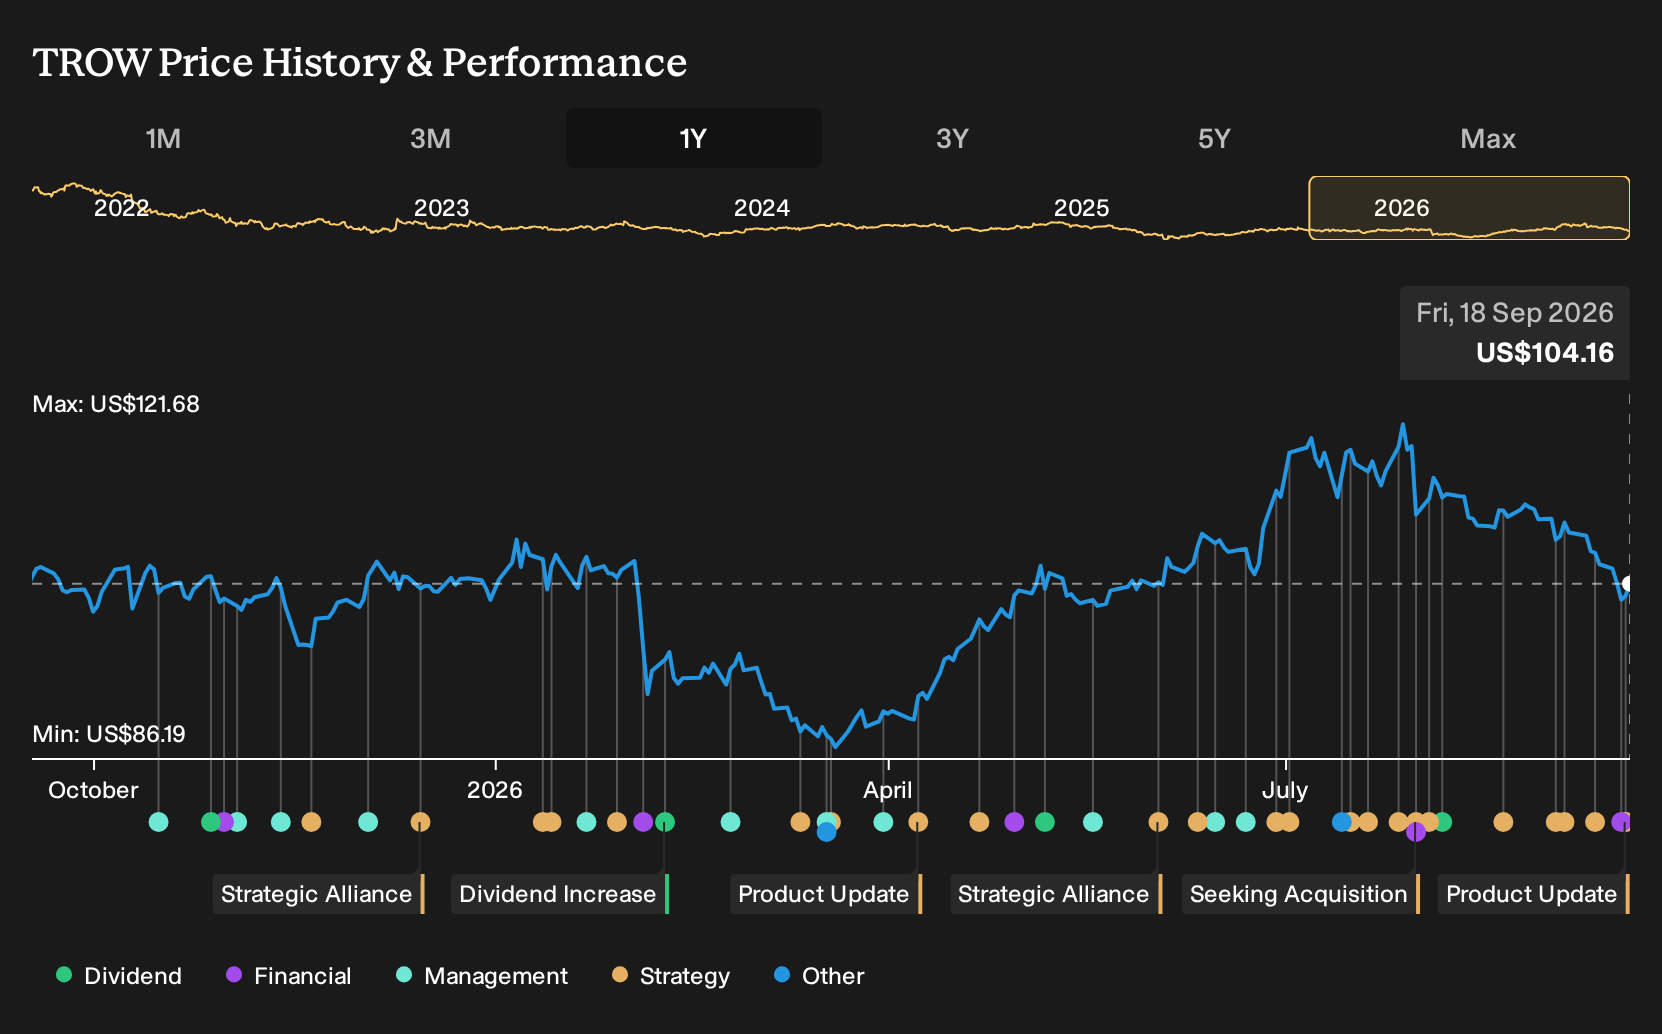
Exploring Other Perspectives
Some of the most optimistic analysts see T. Rowe Price Group’s ETF buildout as a real earnings swing factor. They were already penciling in US$8.5b of revenue and US$2.6b of earnings by 2029, slightly above consensus. You can read those projections as a bolder story that this ETF launch may yet reshape.
Explore 4 other T. Rowe Price Group fair value estimates, including one that suggests as much as 85% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your T. Rowe Price Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T. Rowe Price Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T. Rowe Price Group's overall financial health at a glance.
Looking for more T. Rowe Price Group investment ideas?
If this T. Rowe Price Group update has sharpened your view but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other businesses that fit your risk, income, or quality preferences.
- If resilience and balance sheet strength are high on your list, scan a list of solid balance sheet and fundamentals (23 results) that can help you focus on companies with room to absorb shocks.
- If you want income to play a bigger role in your portfolio, review a curated set of 6 dividend fortresses that may suit a yield focused approach.
- If you are hunting for overlooked quality, run through 16 high quality undiscovered gems that combine fundamentals with relatively low profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com