


MMG (SEHK:1208) Stock Looks Hard To Call Despite Its 277% Run
MMG has delivered a powerful long term share price run, yet the recent pullback and ongoing regulatory scrutiny now put a simple question on the table for you as an investor. Is the current price still supported by what the business is earning today and what those earnings may reasonably grow into over time?
- Over the past 3 years, MMG has returned about 277.0%, which puts real pressure on the earnings story to justify how far the share price has come.
- Regulators in Europe have raised concerns over MMG's proposed acquisition of Anglo American's Brazilian nickel operations, which can influence how investors think about future earnings power, capital commitments and the timing of any benefits from added low carbon ferronickel supply.
- The analysts covering MMG have run their own numbers. See what analysts think MMG's shares could be worth.
The issue now is whether MMG's current share price, after this mix of long term gains and deal related uncertainty, is aligned with what its earnings can reasonably support.
If you want to stress test this same earnings question beyond MMG, run the same filter set across 179 high quality undervalued stocks.
Is MMG Fairly Priced on Earnings?
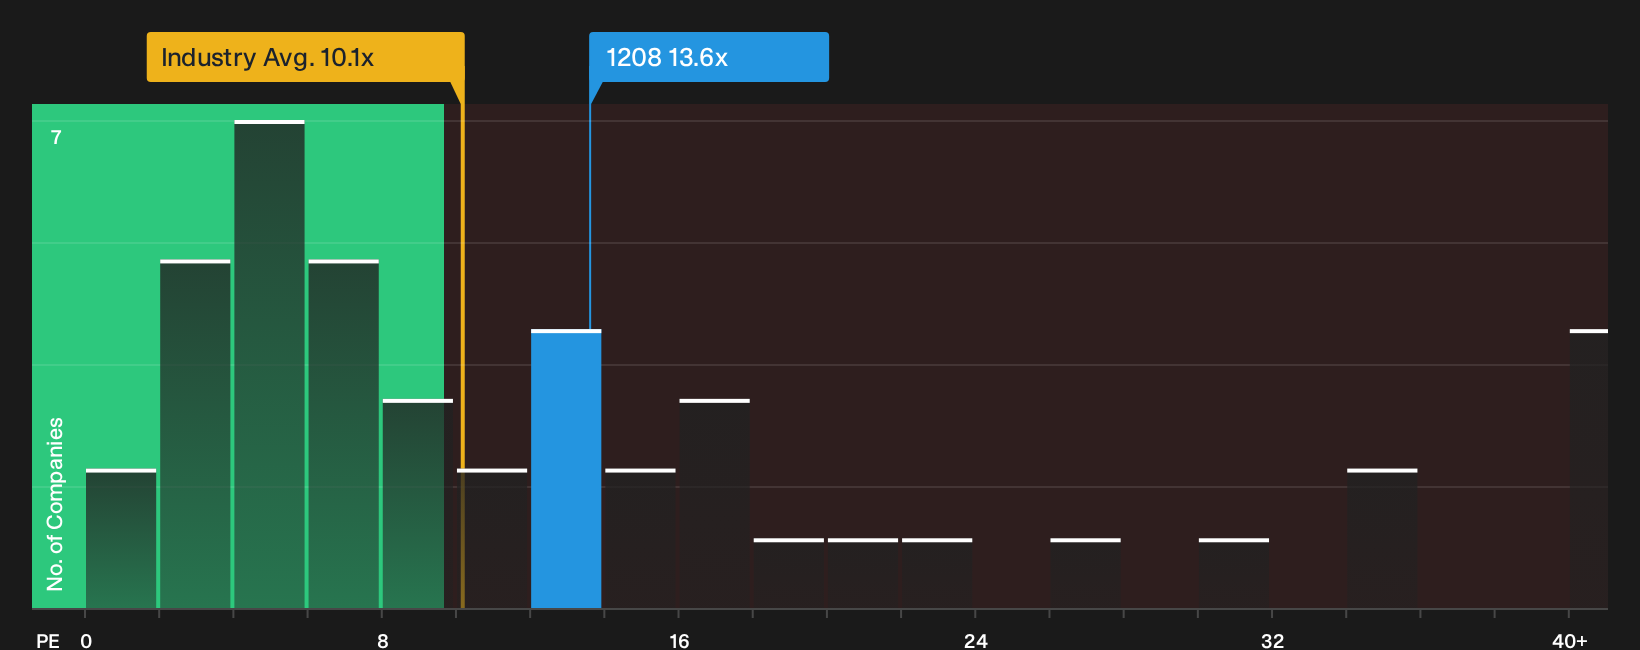
The P/E ratio is a useful way to think about what you are paying today for each dollar of MMG’s recent earnings. MMG currently trades on about 13.6x earnings, which is above the Metals and Mining sector average of roughly 10.1x but below the peer group average near 18.8x. That mix points to investors assigning the stock a richer tag than the broad industry, yet not as full a price as some directly comparable companies.
The fair P/E level implied by the valuation model sits close to where MMG is trading now, so the current multiple is not clearly stretched or obviously cheap on this framework. Because the EU has raised competition concerns over the Anglo American nickel acquisition, this earnings multiple also reflects how traders are weighing potential deal risks against the value of added low carbon ferronickel exposure. If you want to see how much room there is between today’s P/E and the modelled fair level, you can check the detailed comparison in. Explore the numbers behind MMG's P/E valuation.
The MMG Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for MMG pick up where the valuation puzzle leaves off and spell out what future growth, profitability and earnings path would need to look like for the stock to trade meaningfully higher or lower than today’s level. Each scenario links its number to a clear view on how MMG's growth, margins and risks could evolve, giving you a reference point you can revisit as new information comes through.
One of the top community narratives on MMG: 32% undervalued
"MMG's underappreciated growth pipeline in copper rich regions and its systematically advancing exploration program could unlock significant resource and reserve upgrades..."
Discover why this Narrative puts MMG at 32% undervalued.
One more thing about MMG that could move the story
The share price and earnings profile only tell part of the picture for MMG, because the people steering the business and the way they are rewarded can heavily shape how future decisions play out. See who runs MMG and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com