


Learn Why The Bull Case For Advance Auto Parts Stock Could Change Following New Jersey Hub Opening
- Advance Auto Parts recently opened a new store and market hub in Woodbridge, New Jersey, as part of a broader supply chain overhaul that consolidates its distribution footprint from 38 centers to 12 by 2026.
- This tighter network is designed to cut logistics costs and sharpen in-stock availability, which affects the core economics of how Advance Auto Parts serves professional and retail customers.
- We will now explore how this consolidation of 38 distribution centers into 12 could reshape Advance Auto Parts' broader investment narrative.
Scan how Advance Auto Parts' supply chain reset compares with peers by reviewing handpicked 33 high quality undervalued stocks that may be pricing in similar operational shifts.
Advance Auto Parts Investment Narrative Recap
To own Advance Auto Parts, investors need to believe the three year reset can turn a low margin, complex retailer into a cleaner, more efficient operator. The short term hinge is whether supply chain changes, including the Woodbridge hub and broader DC consolidation, start to support better in stock levels without causing transition costs to rise excessively.
The biggest near term risk still sits in execution. Store closures, inventory clean up and transitory expenses have already weighed on profitability. If sales softness, higher one off charges or macro pressure on consumer spending persist while the network is being rebuilt, the path to steadier earnings for Advance Auto Parts becomes harder.
The Woodbridge opening fits directly into the existing three year plan that aims to simplify the distribution network and improve gross margins. A tighter hub and spoke system only really pays off if it feeds into the new assortment framework, better availability for professional customers and faster delivery under the standardized store structure.
No fresh guidance came with this specific opening, so the announcement is best read as an execution checkpoint on the shift from 38 to 12 DCs in the network. For investors tracking catalysts, the key question is whether rollouts like Woodbridge reduce supply chain costs quickly enough to offset store closure charges, one off items and weaker early 2025 sales trends.
Advance Auto Parts' current consensus narrative points to revenue of US$9.1b and earnings of US$277.7m by 2029. That path assumes 1.7% yearly revenue growth and an earnings increase of about US$168.7m from US$109.0m today.
Discover why Advance Auto Parts' fair value indicates an 18% potential upside to its current price that could close sooner than many investors expect.
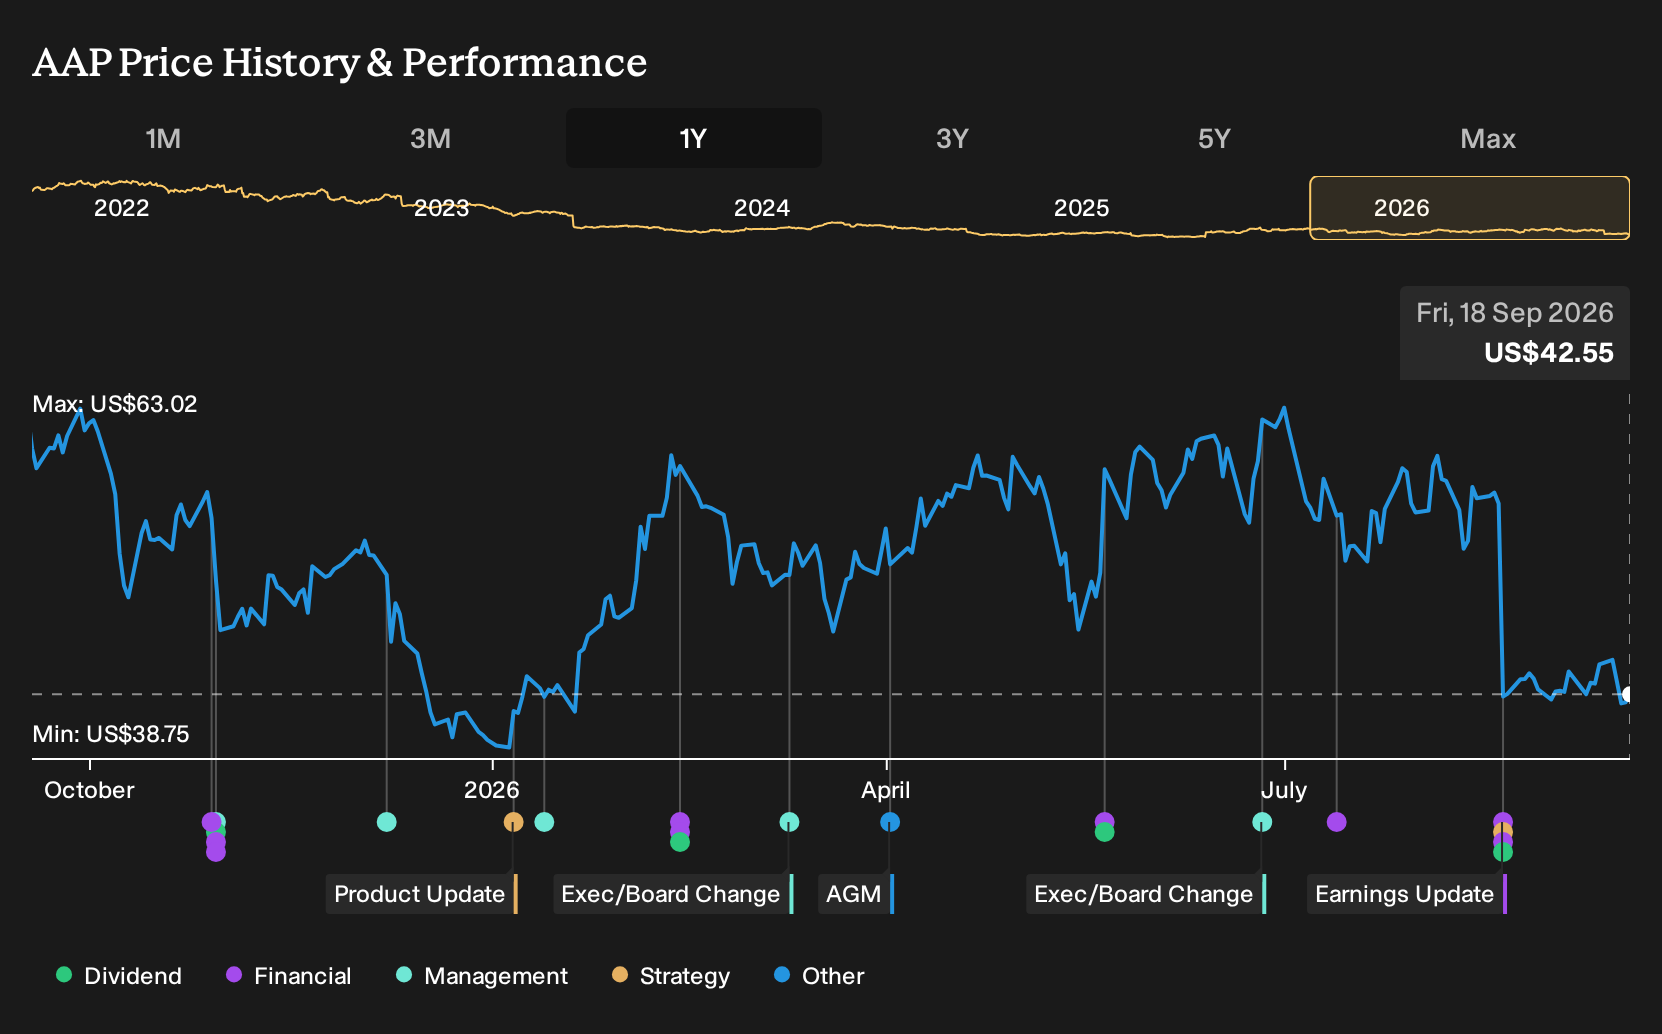
Exploring Other Perspectives
One alternative view on Advance Auto Parts leans into the Woodbridge hub as a potential accelerator. The most optimistic analysts were already modeling revenue near US$9.2b and earnings of about US$362.4m by 2029. You can see how that more upbeat story might evolve if this supply chain reset outperforms expectations.
Explore 2 other Advance Auto Parts fair value estimates, including one that suggests as much as 60% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Advance Auto Parts research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Advance Auto Parts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advance Auto Parts' overall financial health at a glance.
Looking for more investment ideas beyond Advance Auto Parts?
If the Advance Auto Parts story has you thinking about where else operational resets or stronger balance sheets might be underappreciated, use this momentum to broaden your watchlist with a few focused stock shortlists from the Simply Wall St Screener.
- For investors who care most about resilient business models and capital preservation, start with a 30 resilient stocks with low risk scores that could help you focus on companies with steadier fundamentals.
- If dependable income streams are a priority, scan a 6 dividend fortresses to find candidates that combine higher yields with an emphasis on durability.
- For readers hunting for mispriced opportunities with solid fundamentals, a 16 high quality undiscovered gems can surface lesser known stocks that may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com