


How Investors May Respond To Avantor (AVTR) APAC Bioprocessing Expansion
- Avantor recently expanded availability of its RIM single-use bioprocessing portfolio across the Asia Pacific region, including local manufacturing capacity in China, to better support regional biopharma producers.
- This move ties directly into Avantor's Revival strategy, connecting commercial execution and manufacturing productivity with on-the-ground support for APAC biologics demand and supply reliability.
- We will now look at how Avantor's broader investment narrative is affected by the APAC rollout of its RIM bioprocessing portfolio.
Compare Avantor's APAC bioprocessing push with other potential breakout plays in life sciences by scanning our curated list of list of solid balance sheet and fundamentals (23 results).
Avantor Investment Narrative Recap
To own Avantor, you need to believe the core lab and bioprocessing franchise can translate its broad product footprint into steadier earnings after a tough stretch of profitability pressure and weak organic trends. The APAC RIM rollout fits that thesis only modestly in the near term, since the bigger swing factor is whether demand in key end markets moves off flat to negative territory.
The main short term catalyst is execution on cost transformation and pricing discipline while still holding on to large enterprise contracts. The biggest risk remains margin strain from aggressive discounting and underused capacity, combined with leverage that already leaves interest costs poorly covered by earnings. The APAC expansion does not materially change that balance yet.
The recent APAC expansion of Avantor’s RIM single use bioprocessing portfolio is the clearest operational move tied to its Revival plan. It responds directly to earlier bioprocessing headwinds like flat revenue and customer specific setbacks by trying to bring supply closer to regional demand and tailor assemblies for local biologics producers.
For catalysts, this matters most if it helps shift product mix toward higher value single use solutions and steadier utilization at the new China site. Execution risk is real. Competitive pricing, regulatory uncertainty in newer modalities, and already thin margins mean any ramp in APAC needs to translate into disciplined volume, not just more fixed cost on the ground.
Avantor's current loss of $578.0 million is forecast by analysts to shift to earnings of $651.0 million by 2029, a change of about $1.23b. Top line projections call for $7.1b of revenue by that same year, with an assumed 2.8% yearly revenue growth rate to reach that level.
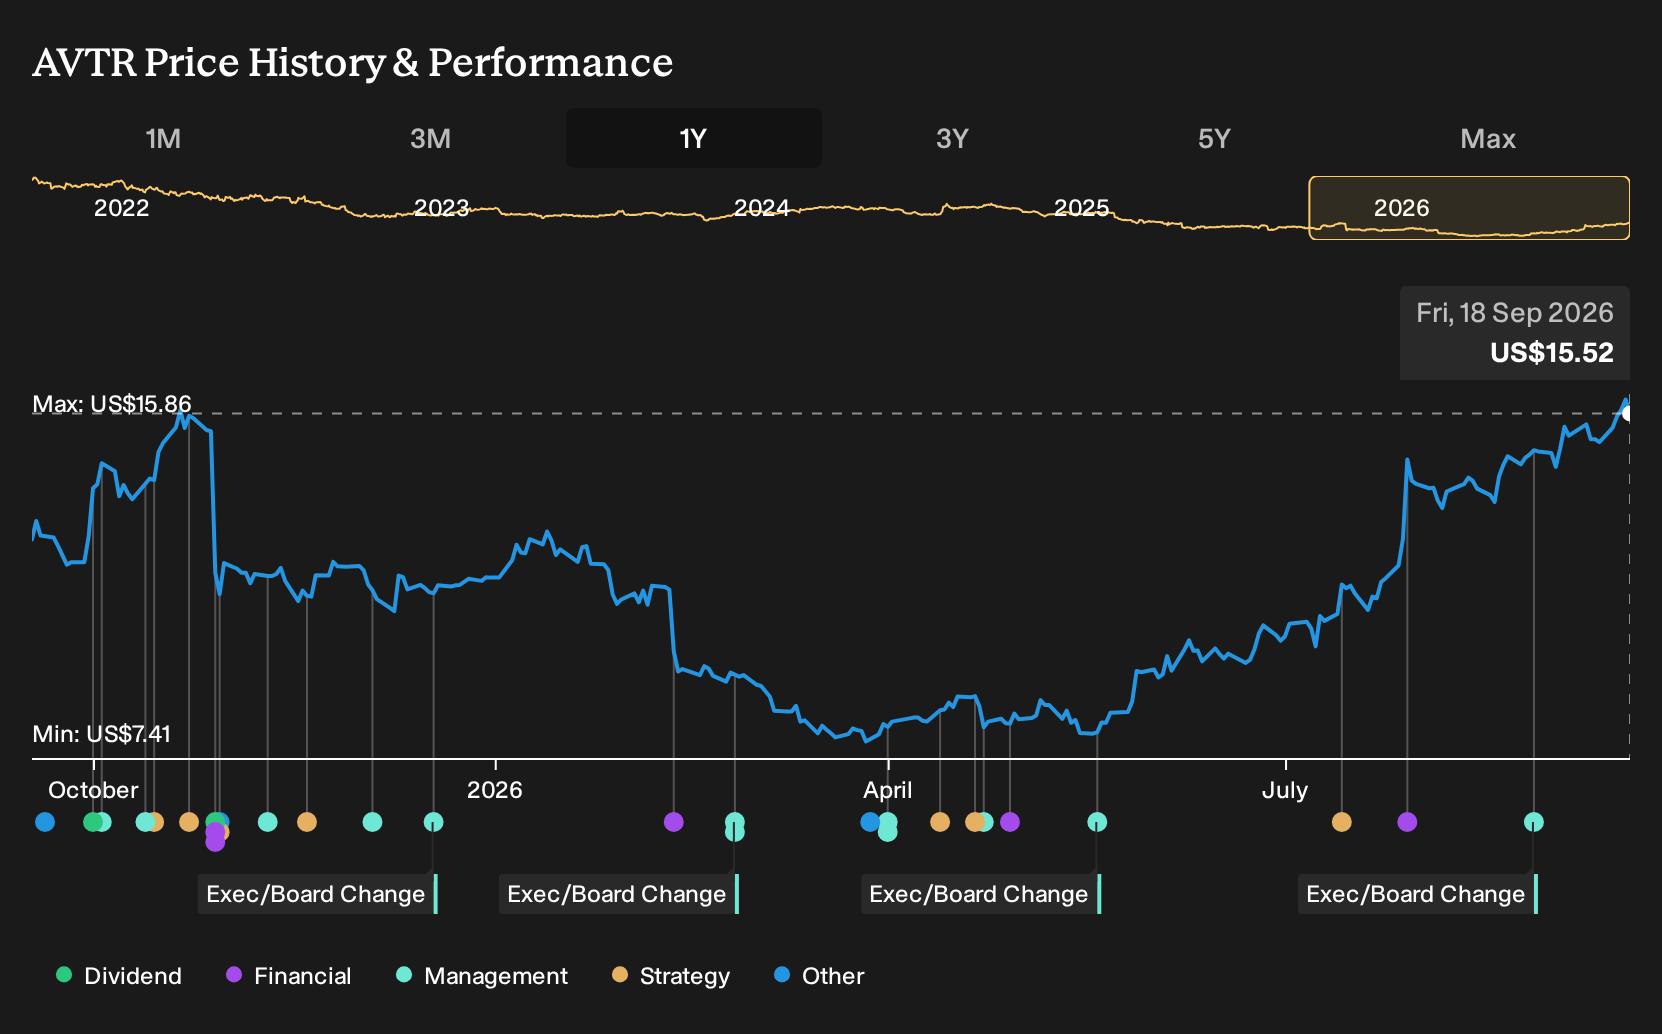
Uncover why Avantor's fair value indicates a 6% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
One alternate view focuses on digital automation risk rather than APAC bioprocessing upside. In that more cautious scenario, the lowest analysts were only penciling in about 2.3% annual revenue growth and earnings of roughly $524.9 million by 2029. Those forecasts were set before this Avantor APAC expansion, so opinions may shift as details land.
Explore another Avantor fair value estimate, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Avantor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Avantor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avantor's overall financial health at a glance.
Looking for more Avantor sized investment ideas?
Once you have a view on Avantor, it helps to compare it with a few other opportunities that match your risk tolerance and return goals, rather than anchoring everything on a single ticker.
- For investors who want potential upside without stretching on quality, scan a curated group of resilient businesses through the 30 resilient stocks with low risk scores.
- If income matters more than fast moves, focus on cash generating payers by reviewing the 6 dividend fortresses.
- When you want to get ahead of the crowd, look at under followed opportunities with solid fundamentals using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com