


Allegion (ALLE) Stock Looks Fully Priced Given Its Cash Flow Outlook
Allegion shares have pulled back over the past year after a strong multi year run. This puts a spotlight on whether the current market value lines up with the cash the business is expected to generate. With the price sitting around US$152.28 at the last close, the central question is how that tag compares to what its future cash flows may be worth today.
- Over the past 3 years, Allegion has delivered a 53.2% share price gain, which makes it important to test whether that climb is supported by the underlying cash generation story.
- The company relies on converting security product sales into steady free cash flow, so assumptions about pricing power, manufacturing efficiency, and investment needs can significantly influence any intrinsic value estimate based on its cash flows.
- Prefer to judge Allegion on earnings? See what Allegion's 19.7x P/E says about the price.
The issue now is whether Allegion's current share price is appropriately grounded in the cash flows implied by a Discounted Cash Flow (DCF) style intrinsic value estimate.
If you are weighing whether Allegion's cash flows justify its current price, it can help to compare that question across 33 high quality undervalued stocks.
Is Allegion Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on how much cash Allegion can return to shareholders over time. Latest twelve month free cash flow sits around $670.3 million, and the model projects this cash figure continuing to grow, with analyst inputs running through to 2030 before easing into more modest estimates beyond that point.
This pattern suggests a business leaning on steady free cash flow from its security products, rather than dramatic swings in either direction. With the DCF output putting Allegion broadly in line with the current trading level of $152.28, the market price already reflects a view that these projections are reasonably dependable. For anyone comparing price against cash generation, the DCF implies Allegion is neither clearly cheap nor obviously stretched on this set of assumptions. Find out what Allegion could be worth using our Discounted Cash Flow (DCF) estimate.
The Allegion Narrative: What Would Justify Today's Price?
Narratives for Allegion pick up where the DCF puzzle leaves off and spell out which paths for growth, margins, and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price, and they live on Simply Wall St’s Community page. Instead of a single output from a model or ratio, you see the specific future that number leans on so you can watch whether Allegion’s reality tracks it.
One of the top community narratives on Allegion: 13% undervalued
"Robust expansion in smart and connected security solutions, particularly through strong electronics growth and new launches, positions Allegion to benefit from increased adoption of IoT…"
Discover why this Narrative puts Allegion at 13% undervalued.
One more Allegion signal to check before you decide
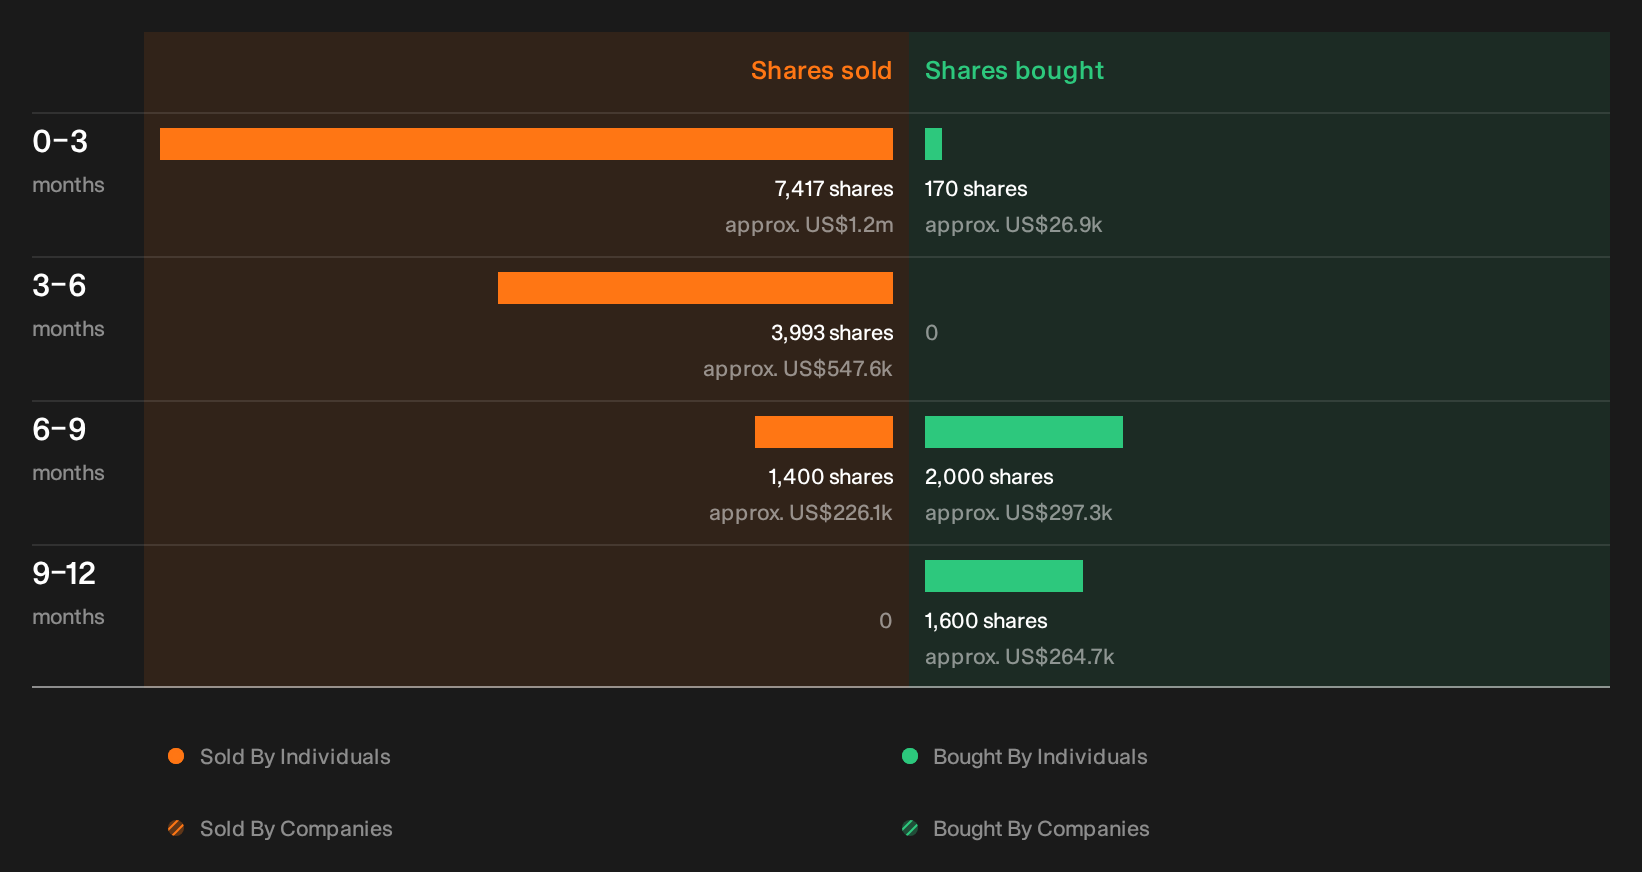
Before you lean too heavily on the cash flow view of Allegion, it is worth looking at what recent seller activity from people inside the business might be hinting at. See the recent insider selling flagged for Allegion.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com