


Is LPL Financial Holdings (LPLA) Undervalued Or Is Its Advisor Growth Already Priced In?
Gateway Financial Partners’ decision to keep 28 former Sierra Ridge advisors on the LPL Financial Holdings (LPLA) platform, along with about $825m in client assets, puts fresh attention on the stock’s longer term business momentum.
Recent trading has been choppy for LPL Financial Holdings, with the share price down 7.26% over the past week and 8.67% over the last month. Even so, the 90-day share price return is up 11.61% and the 5-year total shareholder return is 115.67%, suggesting long term holders have still seen strong compounding despite fading near term momentum.
Scan 33 high quality undervalued stocks that share LPL Financial Holdings’ adviser-led model and could be setting up for the next leg of business momentum.LPL Financial Holdings has slipped in the short term while still carrying a strong multi year track record. The real question now is how much of the valuation upside already sits in the rearview mirror.
Most Popular Narrative: 24% Undervalued
On the most followed narrative, LPL Financial Holdings screens as undervalued, with a fair value estimate of about $429 against a last close of $328.09. That gap rests on a detailed view of advisor growth, interest sensitive revenue and how the platform scales.
The demographic shift toward an aging population and rising demand for financial advisory services is expanding the addressable market for LPL, as evidenced by record total assets of $1.9 trillion and strong organic net new asset growth supporting long-term revenue growth. The continued industry movement from defined benefit to defined contribution and individual investment accounts is increasing the need for independent financial advice, fueling LPL's robust advisor recruitment (with $161 billion in recruited assets over the trailing 12 months) and contributing to higher fee-based revenue growth.
See why 4 investors see LPL Financial Holdings as 24% undervalued.
Result: Fair Value of $429.33 (UNDERVALUED)
Still, the story for LPL Financial Holdings can change quickly if rate sensitive cash sweep revenue weakens or if large acquisitions like Commonwealth increase costs and affect advisor growth.
Find out about the key risks to this LPL Financial Holdings narrative.
Another Angle On LPL Financial Holdings’ Valuation
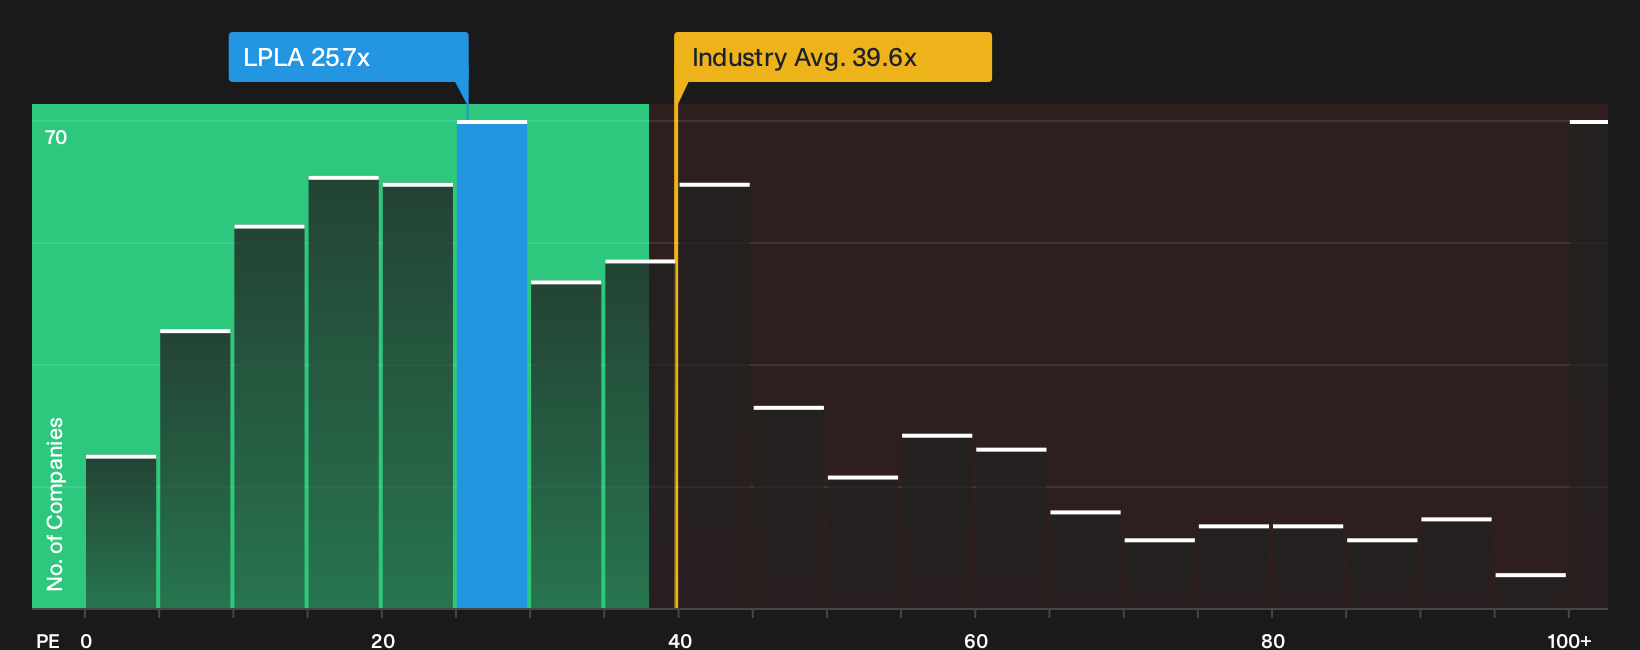
The earlier narrative leans on future cash flows and analyst targets that point to LPL Financial Holdings looking undervalued. A second lens using the current P/E ratio tells a more mixed story. The stock trades on 25.7x earnings while the fair ratio sits closer to 19.8x.
That gap suggests investors today are already paying a premium to the level our fair ratio implies the multiple could move toward, even though the same P/E still comes in below peers at 27.4x and well under the wider US Capital Markets group at 39.6x. Is that premium simply the cost of access to forecast earnings growth, or a sign that expectations now leave less room for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or emerging opportunity, the key is to move quickly enough to test the evidence yourself and decide where you stand. To see how the risks and rewards stack up side by side, start with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond LPL Financial Holdings?
If you only stop with LPL Financial Holdings, you could miss other opportunities that match your goals, risk tolerance, and income needs across the market.
- Target potential mispricing by scanning a focused pool of quality opportunities through 33 high quality undervalued stocks that may align better with your return objectives.
- Strengthen capital preservation by reviewing a 30 resilient stocks with low risk scores that keeps volatility in check while you assess where to allocate fresh capital.
- Spot under-the-radar potential by searching across a 16 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com