


How Stronger Rental Demand At United Rentals Stock Has Changed Its Investment Story
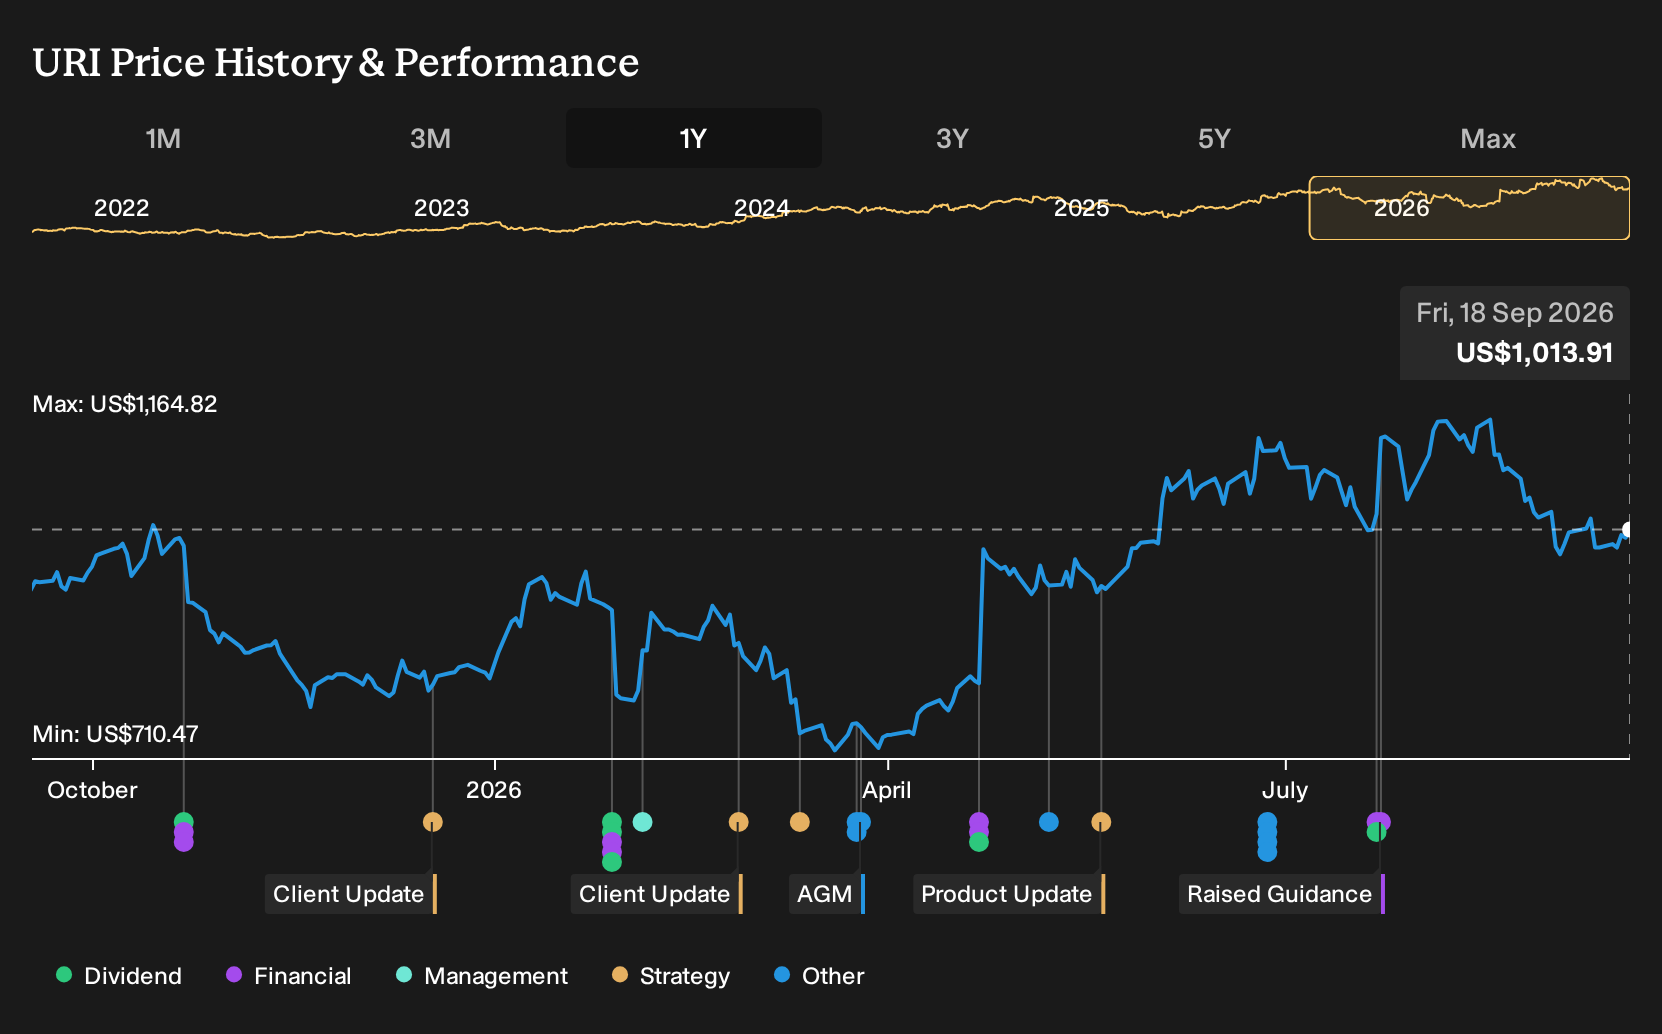
- United Rentals recently told investors that construction equipment rental demand has exceeded its own expectations, helped by a strong pipeline of large projects and continued momentum in specialty rentals, which supported a guidance increase in July despite higher diesel costs.
- Management also highlighted heavier use of technology and AI across operations and customer service, signaling a push to squeeze more productivity and service quality from the existing rental fleet rather than relying only on additional capital spending.
- We will now explore how United Rentals' investment narrative could be affected by this stronger than expected rental demand and raised outlook.
Compare how United Rentals' equipment rental story stacks up against other contractors connected to major project pipelines by reviewing the hand-picked 38 power grid technology and infrastructure stocks in the same infrastructure slipstream.
United Rentals Investment Narrative Recap
To own United Rentals, you need to believe that large project work and specialty rentals can keep equipment utilization healthy while management squeezes more productivity from the existing fleet. The recent update that demand is running ahead of internal expectations supports that thesis in the near term and backs the focus on technology and AI to run the network tighter.
The nearest catalyst sits in how effectively that stronger rental backdrop converts into margins and cash generation, given high diesel costs and ongoing CapEx needs. The biggest risk still comes from any slowdown in large projects that leaves the fleet underutilized and makes those capital commitments harder to absorb.
The upcoming appearance at Morgan Stanley's Laguna Conference on 15 September 2026 is well timed against this stronger rental commentary. Investors will be watching how United Rentals frames specialty operations, technology use and capital intensity when CEO Matthew Flannery and CFO William Grace field questions.
What matters most is whether management reinforces confidence in funding requirements, debt levels and free cash flow while still supporting specialty growth. Clear commentary around pricing, utilization and any discipline on new fleet purchases could either ease concerns around high leverage or keep balance sheet risk as a primary consideration for you.
United Rentals' current analyst script points to revenues of US$22.4b and earnings of US$4.0b by 2029. That path assumes revenue growth of 10.0% per year and an earnings increase of about US$1.4b from US$2.6b today.
Uncover why United Rentals' fair value indicates a potential 25% upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on United Rentals focuses on regulatory and fleet risk rather than big project momentum. The most cautious analysts worry about higher compliance costs on a largely diesel fleet and had pencilled in 7.1% annual revenue growth and earnings of about US$3.4b by 2029. Those forecasts predate this conference news, so their narrative may change over time.
Explore 2 other United Rentals fair value estimates, including one that suggests it could be worth just $1050.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Rentals research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Rentals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Rentals' overall financial health at a glance.
Looking for more investment ideas beyond United Rentals?
Once you have a view on United Rentals, it can help to widen the lens and see how other listed businesses measure up on quality, value and balance sheet strength using the Simply Wall St Screener.
- If you want potential mispricing combined with solid fundamentals, start by reviewing a curated pool of companies through the 33 high quality undervalued stocks.
- For investors who care most about resilience and capital preservation, you can narrow the field to businesses that score well on financial risk using the 30 resilient stocks with low risk scores.
- If balance sheet strength is your first filter, focus on firms that pair cleaner leverage profiles with sound fundamentals using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com