


How Investors May Respond To Johnson Controls Stock After Europe Heat Pump Launch
- Johnson Controls International has launched its Sabroe HitemHP high temperature industrial heat pumps in Europe, targeting process heat users with natural refrigerants, modular factory-assembled units, and part load efficiency that can materially cut electricity use, water consumption, and on site CO2 emissions when paired with waste heat.
- The product line shows how Johnson Controls International is leaning into EU-aligned refrigerants, configure to order designs, and customer tested performance to address energy cost pressure and operational reliability demands in industrial heating.
- We will now examine how Johnson Controls International's investment narrative could be influenced by the HitemHP heat pumps' high energy efficiency profile.
Scan beyond Johnson Controls International and review other industrial decarbonization plays with the 38 power grid technology and infrastructure stocks that could benefit as demand for electrified process heat and grid-ready solutions increases.
Johnson Controls International Investment Narrative Recap
To own Johnson Controls International, you need to believe its building products and decarbonization platforms can translate into steadier earnings, better margins and solid service revenue over time. The Sabroe HitemHP launch supports that idea on the operations side, but the main near term swing factor still looks like execution on the new organizational model and Lean efforts.
The bigger risk is that complexity in product lines, high debt and restructuring friction dilute the benefit of strong demand and decarbonization tailwinds. If pricing actions, service attachment and cost discipline underperform, the current premium P/E and tight discount to estimated fair value leave limited room for operational missteps.
The HitemHP launch feels most relevant because it ties directly into Johnson Controls International’s decarbonization and efficiency story. Management is marketing up to 3x electric boiler efficiency, significant energy cost reductions, and higher part load COP, which speaks to industrial customers facing energy price and regulatory pressure, especially in Europe.
For you as a shareholder, the interesting link is execution. HitemHP uses natural refrigerants aligned with EU rules, a modular configure-to-order design and a compressor architecture aimed at longer service intervals. If Johnson Controls International can replicate that kind of customer-tested engineering and modularity across more offerings, it may support backlog quality and service revenue, while poor rollout would reinforce the existing complexity and integration risks.
Johnson Controls International’s consensus narrative points to revenues of US$31.5b and earnings of US$4.6b by 2029. This is based on analysts’ assumptions of 8.0% yearly top line growth and an increase in profits from US$2.2b today, which implies roughly a 2.1x earnings step up over that period.
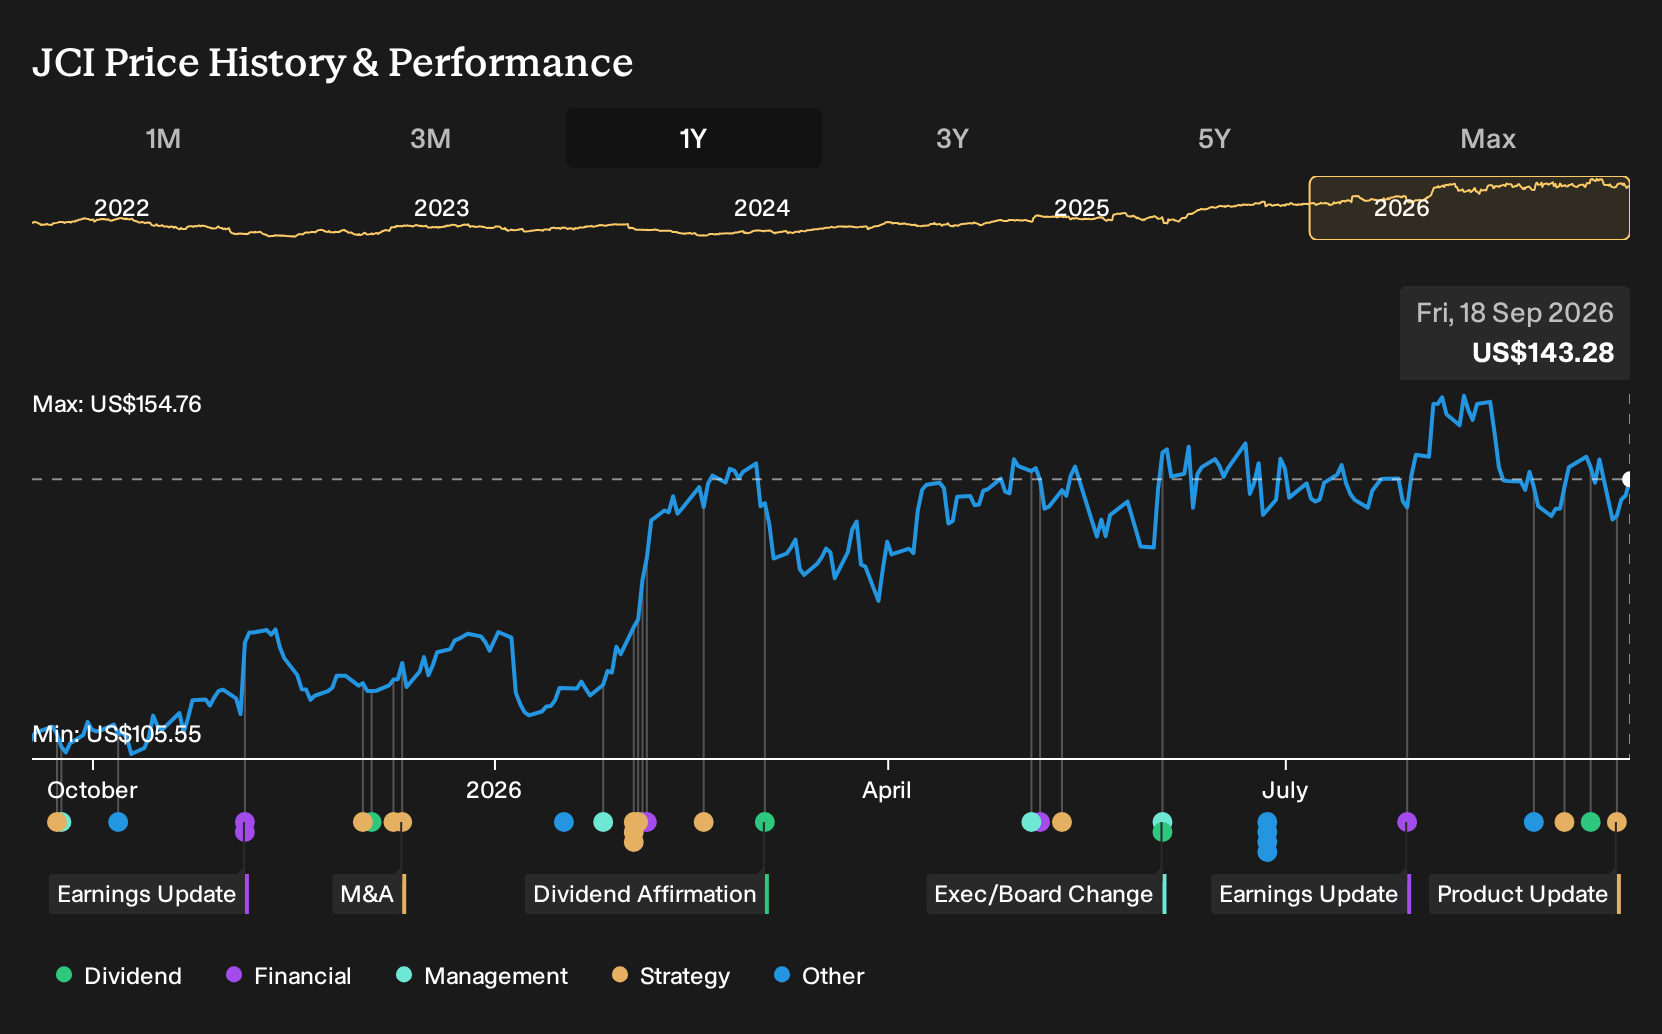
Uncover how Johnson Controls International's fair value indicates a 14% potential upside to its current price, which could narrow quickly if expectations reset.
Exploring Other Perspectives
One alternate view says the real risk for Johnson Controls International is slow expansion beyond mature regions. The most bearish analysts were modeling revenue of about US$30.3b and earnings of US$4.5b by 2029, slightly below consensus. Those estimates came before the HitemHP launch, so opinions on long term potential may shift.
Explore 3 other Johnson Controls International fair value estimates, including one that suggests it could be worth just $144.12.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Johnson Controls International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Johnson Controls International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Johnson Controls International's overall financial health at a glance.
Looking for more investment ideas beyond Johnson Controls International?
If the Johnson Controls International story has you thinking about where else decarbonization, resilient balance sheets and consistent cash generation might matter, it can be useful to widen the lens with a structured stock search.
The Simply Wall St Screener lets you filter by financial strength, valuation and risk profile so you can line up opportunities that fit your own checklist rather than just following headlines.
- For investors who want to focus on stability first and potential upside second, start with companies that score well on debt, liquidity and cash coverage by scanning the list of solid balance sheet and fundamentals (23 results).
- If capital preservation and steadier returns matter most to you, narrow your list to businesses with fewer red flags and steadier fundamentals by reviewing the 30 resilient stocks with low risk scores.
- When you are hunting for less crowded ideas with strong underlying numbers, broaden your watchlist with the 16 high quality undiscovered gems that may not yet sit on every analyst's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com