


How Investors May Respond To Verisk Analytics (VRSK) Fraud Platform Launch
- Verisk Analytics recently launched Verisk Fraud Discovery, a modular fraud prevention platform that unifies analytics, network analysis and digital media forensics, with early adopters including Hiscox, Allianz and law firm Weightmans.
- The arrival of Verisk Fraud Discovery speaks directly to insurers’ need to handle complex, technology driven fraud. It may deepen client reliance on Verisk’s data and workflow tools across underwriting, claims and fraud teams.
- We will now test how Verisk Fraud Discovery’s connected fraud intelligence might reshape the existing investment narrative around data driven platforms.
Verisk Analytics Investment Narrative Recap
For Verisk Analytics, the core belief as a shareholder is that insurers keep paying for deeper, more connected data tools that support underwriting, catastrophe modelling, claims and fraud detection. The recent Verisk Fraud Discovery launch and Greg Alling’s appointment both sit within that theme, but do not obviously change the near term picture on their own. The bigger swing factor still looks like how insurer budgets hold up against inflation, regulation and reconstruction cost pressure.
On the risk side, the drag from weaker marketing activity outside insurance and the firm’s high debt load still matter, particularly if borrowing costs stay elevated. Weather related loss volatility can also hit transaction based revenue and margins. In the short run, execution on new product rollouts and cost discipline remain the clearest internal levers to offset that backdrop.
The Verisk Fraud Discovery launch ties directly into the most important operational catalyst. It adds another way to monetise Verisk’s long standing insurance data, while giving clients a single fraud workflow that spans detection, investigation and case management across underwriting and claims. Early adoption by Hiscox, Allianz and Weightmans signals real world testing rather than a purely theoretical platform story.
For you as an investor, this matters because it supports the narrative that Verisk Analytics can extend its role from point solutions toward more end to end environments such as Core Lines Reimagine or Enterprise Exposure Manager. If insurers keep seeking connected fraud and casualty insights, that could help counter softer areas such as marketing, while still leaving macro shocks and client budget cuts as the main external risks.
Verisk Analytics’ current analyst narrative points to forecast revenue of US$3.8b and projected earnings of US$1.3b by 2029. That profile assumes annual top line growth of 6.7% and an earnings increase of about US$414.5m from US$885.5m today.
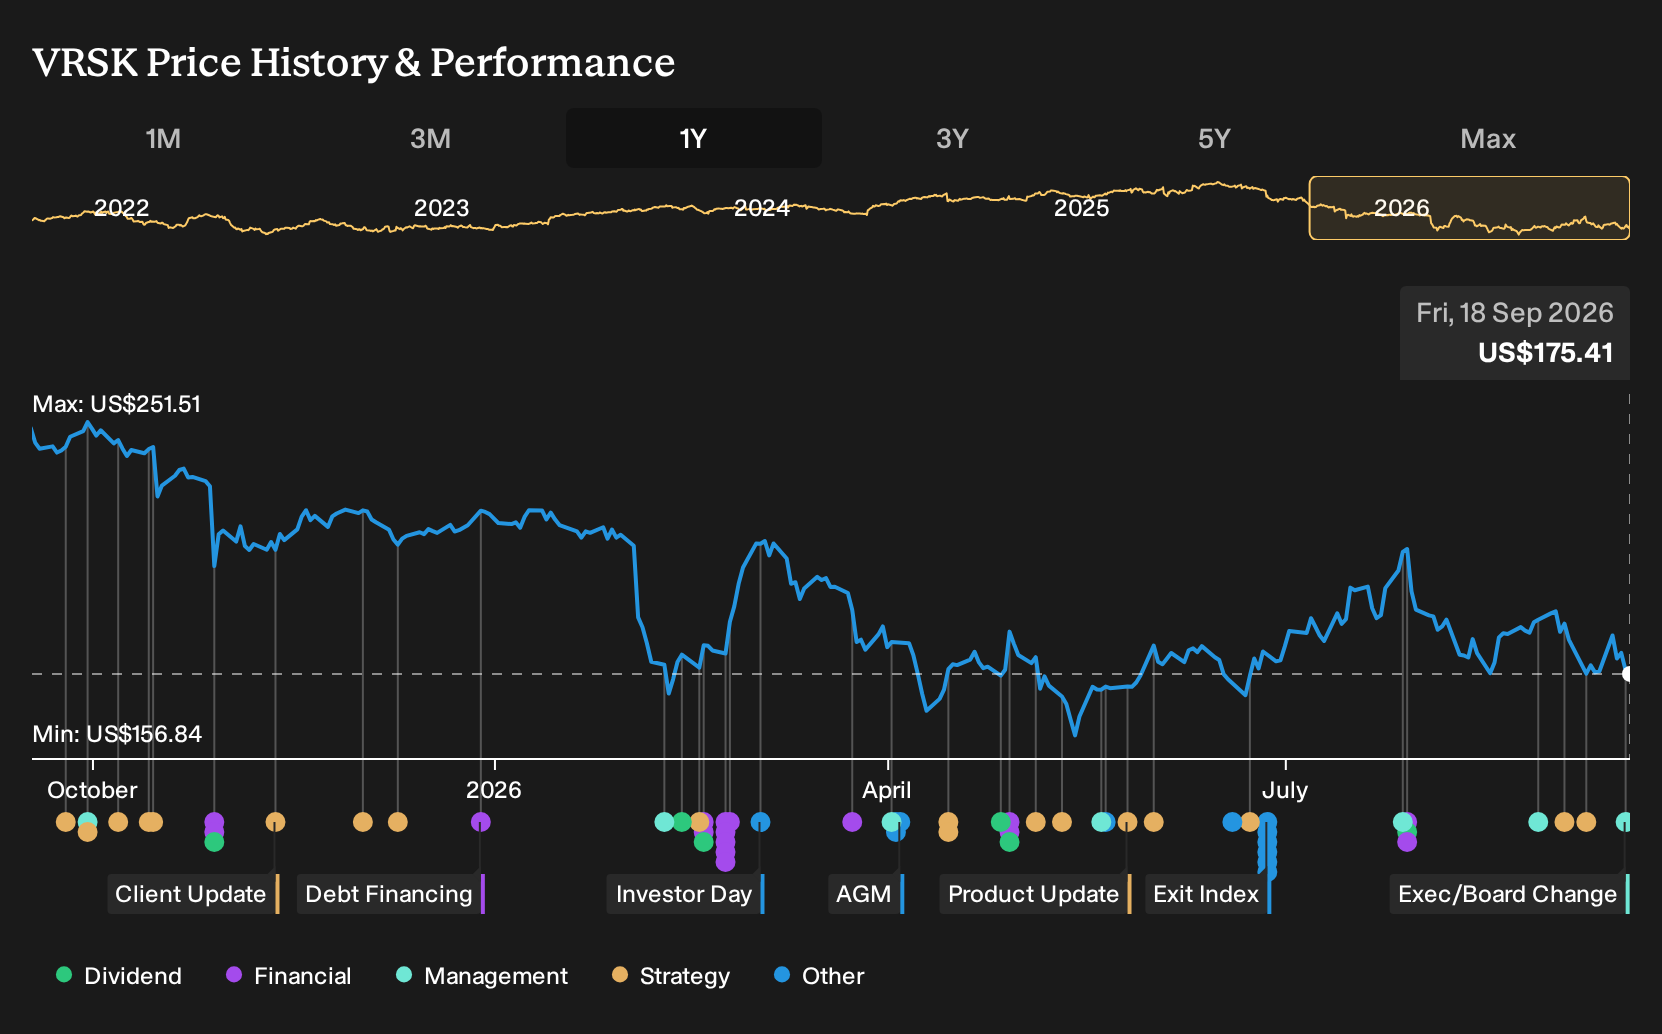
Uncover how Verisk Analytics' fair value indicates a 36% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$77 to US$271 per share, so opinions on Verisk Analytics are already wide apart. Those views also pre date Verisk Fraud Discovery and Greg Alling’s appointment. New product spend, shifting insurer budgets and fraud trends could all push future community estimates in very different directions.
Explore 4 other Verisk Analytics fair value estimates, including one that suggests as much as 54% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Verisk Analytics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verisk Analytics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verisk Analytics' overall financial health at a glance.
Looking for more Verisk Analytics style ideas?
If Verisk Analytics has sharpened your appetite for data led business models, it can help to widen the lens and compare it with other opportunities that already clear some quality hurdles on the Simply Wall St Screener.
- For investors who want resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that already passes strict financial strength filters.
- If value is your priority and you like finding quality at a discount, scan the 33 high quality undervalued stocks that combine robust fundamentals with potentially attractive pricing.
- For those hunting for under the radar potential, review the 16 high quality undiscovered gems that pair strong business quality with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com