


Vita Life Sciences And 2 Australian Dividend Stocks To Own
Central banks are lifting interest rates again, and the Federal Reserve has just kicked off a new hiking cycle. Income from cash and term deposits may shift quickly, but reliable dividend cheques can feel far steadier. Australian dividend stocks with long records of paying and growing income can turn market swings into an entry point. This article walks through three high yield veterans from that group.
The stocks covered below are just a starter pack in the hunt for reliable income, and the full screen has surfaced 0 more companies with equally compelling dividend stories that are not unpacked in this article. To size up the full field of high yield Dividend Aristocrats, identify resilient payers and analyze which ones best fit your portfolio goals, head straight into the Dividend Aristocrats screener.
Vita Life Sciences (ASX:VLS)
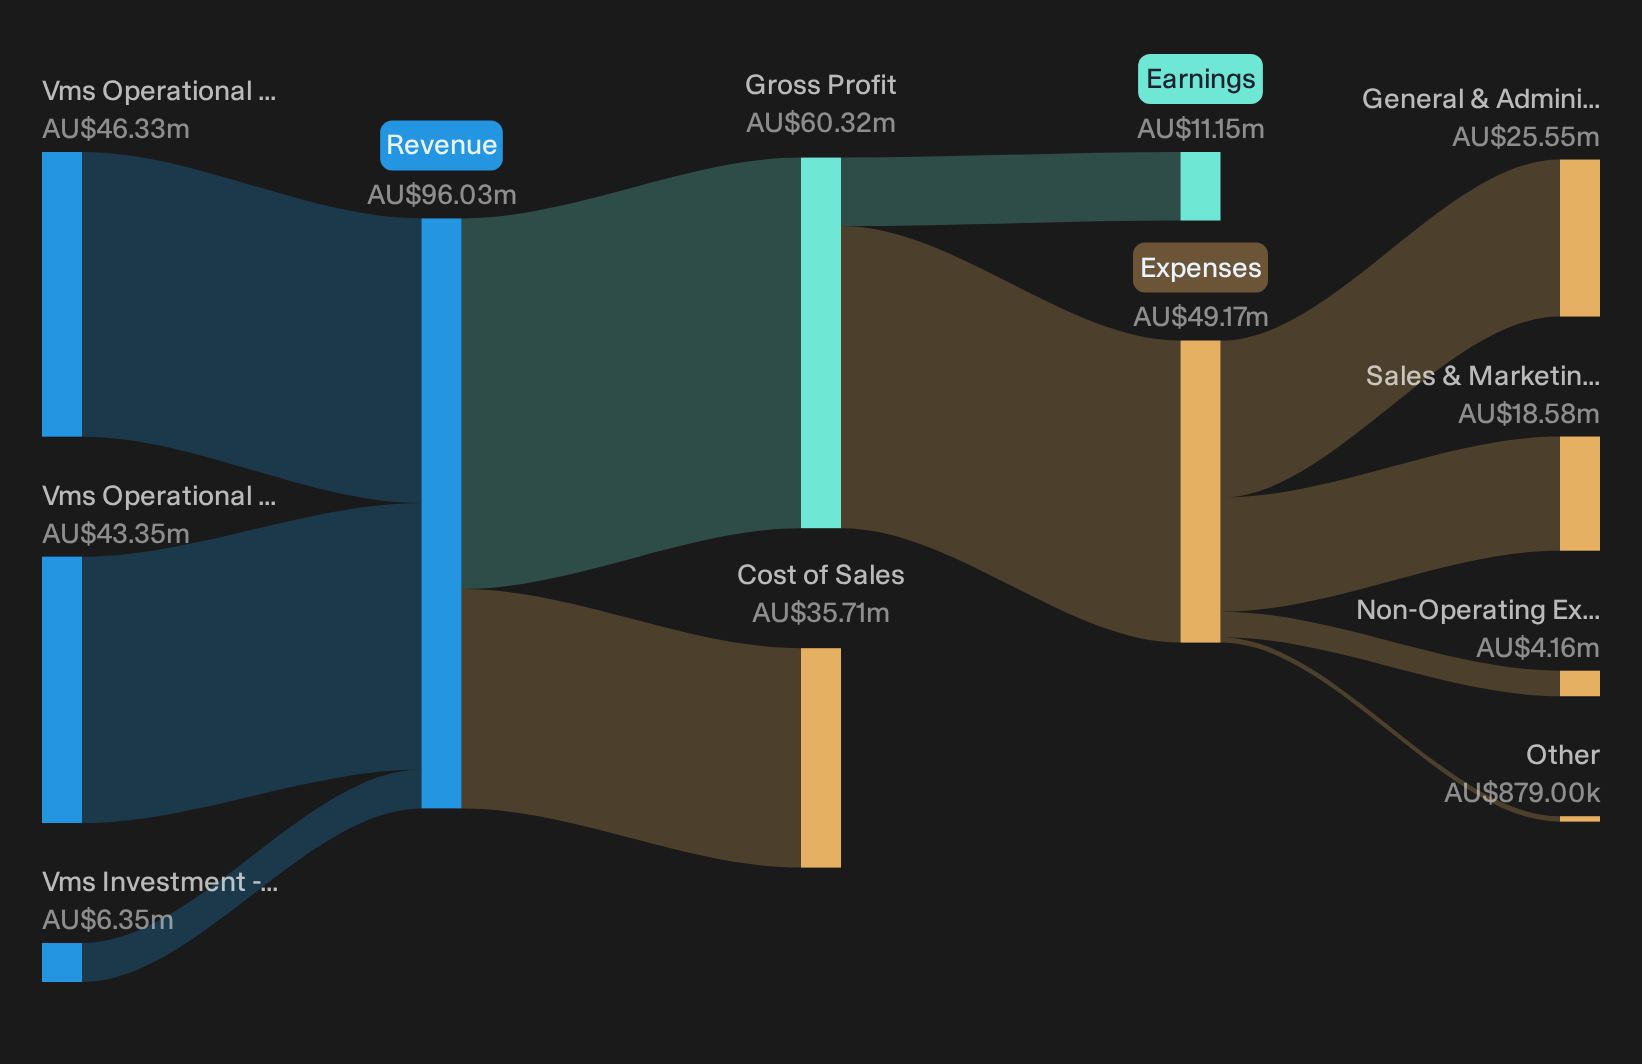
Vita Life Sciences runs vitamin and supplement brands like Herbs of Gold, VitaHealth and VitaScience, tapping steady consumer health demand that suits a dividend aristocrat style profile. It generates about A$43 million from Australia and A$46 million from Malaysia and Singapore, with A$6 million from China and Vietnam, and carries a market value near A$156 million.
For an income hunter, Vita Life Sciences ties a roughly 5.05% yield to a vitamins and supplements business that produced an 11.6% net margin and 20% ROE, backed by recent earnings and dividend announcements in August 2026. The appeal of that cash return depends on how one unseen pressure on those margins develops.
Those margin pressures are exactly what make the 3 key rewards and 1 important warning sign so useful for spotting where Vita Life Sciences’ income story could accelerate or stall next.
Peet (ASX:PPC)
Peet develops and sells residential land across Australia, with most revenue from Development at about A$305 million, supported by A$95 million from Funds Management and A$33 million from Joint Arrangements. That funds management arm anchors the Dividend Aristocrats theme under a business valued near A$779 million.
Income investors get a land developer whose funds management arm generates recurring fees that support high yield potential, backed by A$419 million in revenue and A$103.4 million in profit in FY2026 plus a fully franked A$0.065 half year dividend. Dividend history is uneven, so the appeal of that payout hinges on how one quiet tension between growth and consistency resolves.
That pull between growth and consistency is exactly why it helps to see the full 2 key rewards and 1 important warning sign before deciding how Peet’s income profile really stacks up.

Sandfire Resources (ASX:SFR)
Sandfire Resources is a copper focused miner whose cash producing Motheo and MATSA operations anchor its role in a high yield dividend screen, with revenue of about $745 million from Motheo, $910 million from MATSA and a market value near A$10.3b.
Income investors looking for yield backed by real assets may view Sandfire Resources as a pure copper play that links directly into the Dividend Aristocrats theme, with producing mines able to convert strong copper pricing into distributable cash when conditions are favourable.
"The global acceleration of energy transition (EVs, renewables, grid upgrades) continues to underpin structural demand for copper, directly supporting Sandfire's core product pricing and offering a favorable backdrop for group sales volumes and future earnings expansion."
The real test for Sandfire Resources will be how one quietly growing cost burden interacts with that copper tailwind to shape future dividend capacity.
That cost burden is exactly why it pays to read the full narrative for Sandfire Resources and see how Sandfire Resources’ copper story could be accelerating or quietly stalling.

Seeking Alternatives Before The Window Closes
Fresh ideas move first. By the time momentum is obvious, the easiest opportunities are usually gone. Scan these curated stock lists while the data still matters and get in early.
- Spot cash generative miners and suppliers before copper stories are fully priced by scanning the 16 top copper producer stocks that filters for producers already turning resources into revenue.
- Track the early shift toward autonomous factories and warehouses by reviewing the curated 95 robotics and automation stocks and see which operators are already building real commercial traction.
- Find resilient payers built on strong finances by running the list of solid balance sheet and fundamentals (12 results) and focus on businesses where sturdy cash flows back every dividend headline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com