


Does Valuation Warning Change The Bull Case For GEO Group (GEO)?
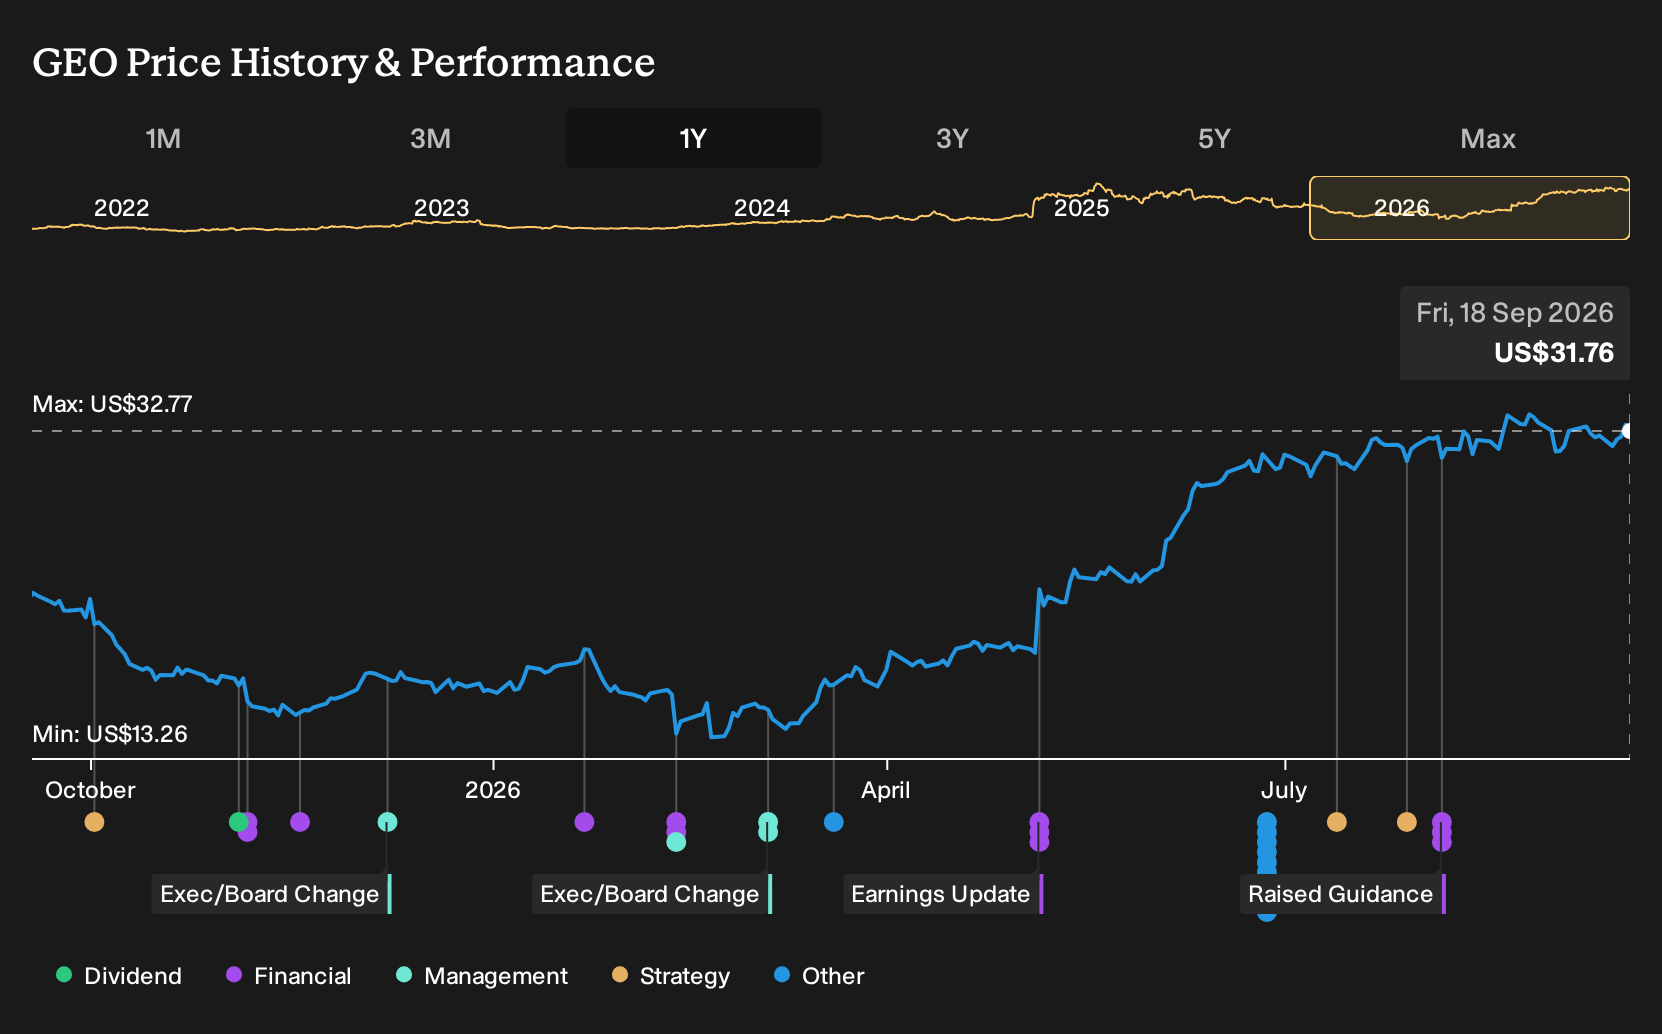
- GEO Group has recorded a very strong multi year share price run, with a 5 year share price return of 349.2%, while still trading on a P/E that sits below industry and peer averages.
- The Fair Ratio model now flags GEO Group as potentially overvalued relative to its growth profile, margins, scale, and risk. This suggests the current price may be running ahead of the underlying profit engine.
- We will now look at how GEO Group's extended share price run and fresh valuation concerns reshape the broader investment narrative.
Pressure test GEO Group's surge against peers by scanning a hand picked set of 33 high quality undervalued stocks that combine earnings power with relatively simple valuations.
GEO Group Investment Narrative Recap
To own GEO Group, you need to be comfortable with a business that leans heavily on U.S. federal detention and supervision contracts and operates with meaningful political and regulatory exposure. The short term swing factor is how fully its existing secure facilities and electronic monitoring programs are used. The recent valuation flag does not change that operational reality, but it does raise the bar for execution.
The biggest near term risk remains a policy or funding shift that reduces ICE detention or electronic monitoring usage, which could leave capacity underused. Interest costs also matter. Analysts highlight that earnings are expected to decline while interest payments are not well covered, so any pressure on cash flows would bite quickly.
One of the most important developments around GEO Group is the large federal funding pool earmarked for immigration enforcement and detention, including money directed toward ICE beds. That funding underpins expectations for higher facility activations and utilization, which are central to the growth story that helped drive the share price run.
Higher federal spending interacts directly with the Fair Ratio valuation concern. If facility activations, ISAP monitoring volumes and idle bed absorption unfold more slowly than hoped, the current P/E could look demanding given analysts expect earnings to decline by about 16.3% per year over the next three years. Execution against those funded opportunities is what now needs to do the heavy lifting.
GEO Group's current analyst narrative points to revenues of US$3.8b and earnings of US$137.8m by 2029, based on forecast revenue growth of 9.9% per year and a shift from current earnings of US$291.5m to the 2029 consensus figure. This implies an earnings decline of about US$154m over that period.
Uncover why GEO Group's fair value indicates a 19% potential upside to its current price before that discount closes for GEO Group investors.
Exploring Other Perspectives
One alternate take on GEO Group leans hard into the upside from aggressive ICE bed expansion. Those bullish analysts were sketching out revenue of about US$4.0b and earnings of roughly US$203.7m by 2029 before this latest valuation concern. Their more optimistic ramp could look very different once the new information is fully absorbed.
Explore 3 other GEO Group fair value estimates, including one that suggests as much as 404% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your GEO Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking For More Ideas Beyond GEO Group?
If GEO Group has you rethinking how risk, valuation, and policy exposure fit together, it can help to line it up against a wider watchlist of potential opportunities.
- For investors who want income to be a central part of the thesis, scan a curated set of 6 dividend fortresses that focus on yield and payout resilience.
- If capital protection and steadier fundamentals rank higher for you than raw upside, filter for 30 resilient stocks with low risk scores that aim to keep drawdowns in check.
- When you want quality businesses that are not yet widely followed, review a hand picked pool of 16 high quality undiscovered gems that pair solid fundamentals with lighter coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com