


NetApp (NTAP) Is Back In The Spotlight, So What Is Driving Attention?
NetApp (NTAP) just extended its NFL footprint, becoming the Official Partner of the Tampa Bay Buccaneers after the team’s first 2026 regular season game. The move highlights NetApp’s data infrastructure role in live sports.
For investors watching the ticker, NetApp’s share price has moved to US$197.79, with a 90-day share price return of 23.84% and an 85.77% share price return year to date. The 5-year total shareholder return of 136.68% points to strong long term compounding, despite a recent softer 7-day share price return of 0.75% that suggests momentum has cooled slightly around the latest NFL and Buccaneers developments.
Spot similar data infrastructure and cloud stocks that could be building their own sports and entertainment partnerships by scanning our curated list of 89 AI infrastructure stocks.NetApp’s Buccaneers tie-up puts its data infrastructure story in front of more fans, yet the modest 7 day move hints at sentiment catching its breath. Is the current valuation tracking business progress or crowd mood?
Most Popular Narrative: 2% Overvalued
The most followed NetApp valuation story puts fair value at $194.19, slightly below the last close at $197.79, so the stock screens as mildly rich rather than deeply mispriced.
Accelerating adoption of AI and analytics workloads across industries is driving demand for unified, high-performance, and scalable data infrastructure, with NetApp securing over 125 AI wins in Q1 (more than doubling year-over-year). This trend is expected to drive revenue and earnings growth as AI deployments move from proofs-of-concept to large-scale production.
See why 47 investors see NetApp as 2% overvalued.
Result: Fair Value of $194.19 (OVERVALUED)
Still, NetApp’s reliance on hyperscaler partnerships and softer trends in regions like EMEA could pressure margins and keep future revenue visibility more fragile than it appears.
Find out about the key risks to this NetApp narrative.
Another View on NetApp’s Valuation
While analyst targets suggest NetApp is mildly overvalued around US$197.79, the Simply Wall St DCF model points in the opposite direction. On that framework, the stock trades roughly 17.5% below an estimated future cash flow value of US$239.81, which presents NetApp as undervalued instead. Which lens investors rely on more depends on how confident they are in long term cash generation as opposed to near term earnings multiples.
For a closer look at how those long range assumptions compare, and how sensitive they are to changes in growth and margin inputs, Look into how the SWS DCF model arrives at its fair value.
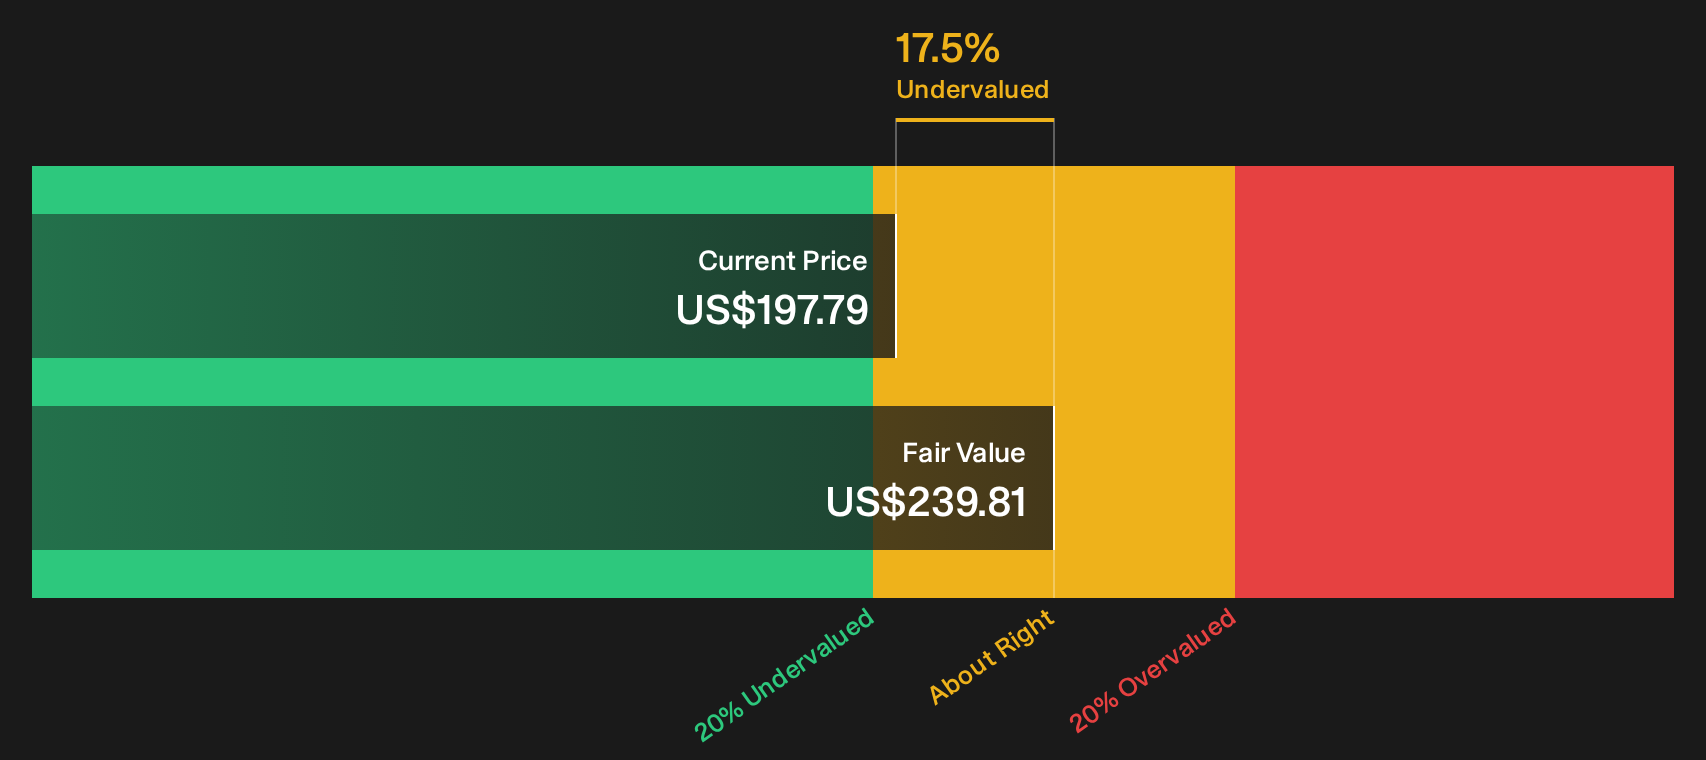
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NetApp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on NetApp valuation and sentiment are one thing; seeing the detail yourself is another, so move quickly and weigh the balance of 3 key rewards and 1 important warning sign.
Looking for more NetApp sized ideas?
If NetApp has your attention, do not stop here. Broader context across other opportunities can sharpen your judgement and keep your watchlist focused.
- Spot potential mispricings early by scanning a curated set of 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Build resilience into your portfolio by reviewing a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier business profiles.
- Get ahead of the crowd by tracking a 16 high quality undiscovered gems that highlights financially strong companies still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com