


Centerspace (CSR) Could Be 2% Below Fair Value Following The IRT Merger Deal
Centerspace (CSR) moved into the spotlight after Independence Realty Trust agreed to acquire the apartment owner in an all stock merger valued at about US$1.1b, with Centerspace investors receiving IRT shares.
For Centerspace, the proposed merger has arrived after a choppy stretch, with the share price falling 16.38% year to date but posting a 3.57% 1 month share price return and a slightly positive 1 year total shareholder return of 1.10%. This suggests momentum had only recently started to stabilise before the deal headlines reset expectations around future risks and potential rewards.
Scan the merger space around Centerspace by reviewing a curated 16 high quality undiscovered gems that are still flying under most investors’ radars yet already match on strong underlying fundamentals.
Centerspace now trades at a meaningful discount to both intrinsic estimates and analyst targets after the merger pop. Is that simply merger risk being reflected in the price, or is the market assessing the fundamentals correctly?
Most Popular Narrative: 2% Undervalued
Centerspace closed at $56.00, while the most followed narrative anchors fair value near $57.00, implying only a small discount once longer term cash flows are run through an 8.0% style discounting framework.
Despite long term household formation and high homeownership costs supporting rental demand in markets like Denver, the need to use a portion of disposition proceeds for special distributions and debt repayment reduces near term capital available for growth investments. This can temper future revenue expansion and Core FFO growth.
See why 0 investors see Centerspace as 2% undervalued.
Result: Fair Value of $57 (UNDERVALUED)
Still, the Centerspace narrative can be knocked off course if softness in Denver lingers or if asset sales remove too much high performing cash flow.
Find out about the key risks to this Centerspace narrative.
Another View On Centerspace Using Market Ratios
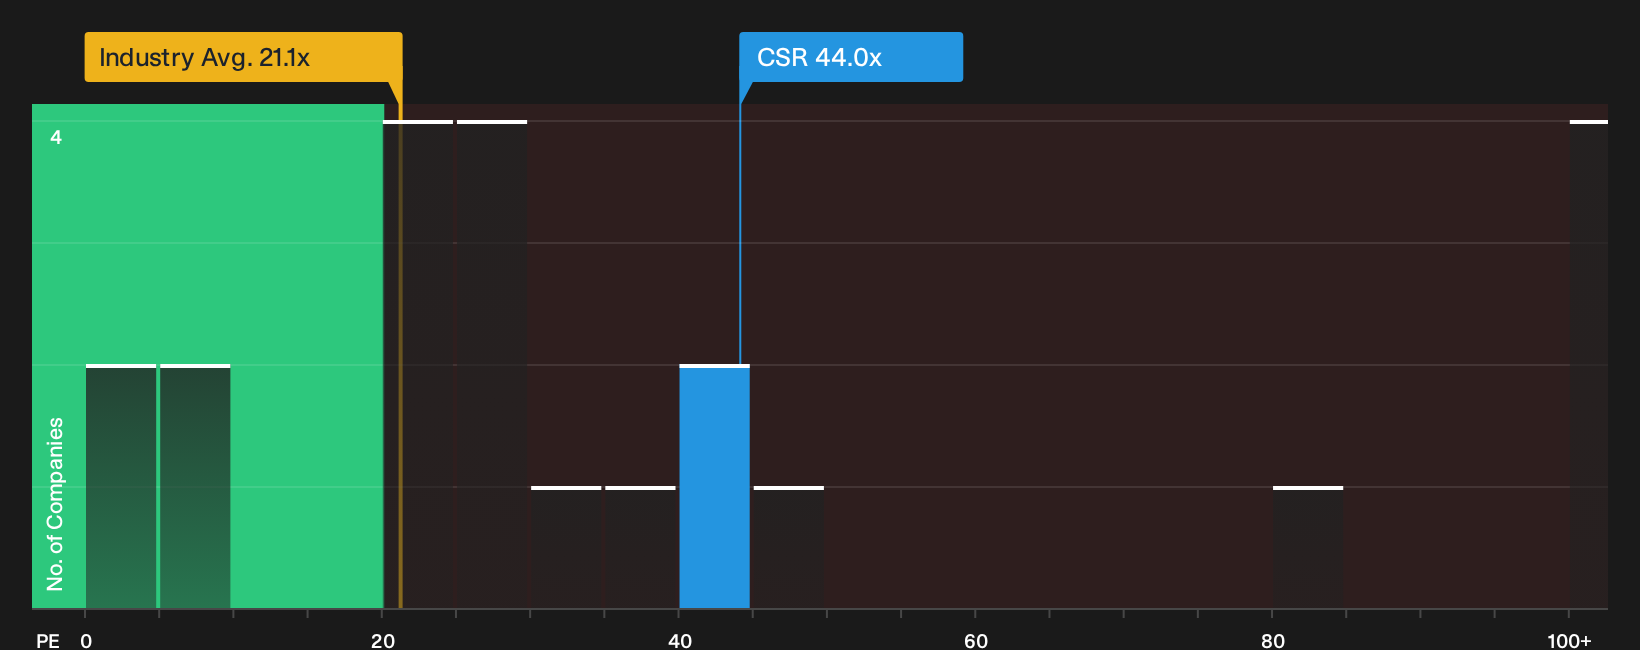
The SWS DCF model suggests Centerspace is worth $81.95 per share, while the market price is $56. That flags undervaluation on cash flows, yet the current P/E of 44x looks expensive against the estimated fair ratio of 2.6x and the Residential REITs industry on 20.2x. How much weight do you put on market multiples versus long term cash flow estimates when those signals clash this sharply?
For a closer look at how this ratio gap could matter for future returns, see the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The sentiment around Centerspace is mixed, with clear risks on one side and some genuine bright spots on the other. Review the numbers yourself, then weigh up the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Centerspace?
If you only stop at Centerspace, you risk missing other opportunities that fit your style, your risk comfort, and the returns profile you really want.
- Spot potential bargains early by reviewing a curated 33 high quality undervalued stocks that already combine solid fundamentals with prices that sit below intrinsic estimates.
- Build a sturdier core to your portfolio by scanning a focused list of solid balance sheet and fundamentals (23 results) that can help anchor overall risk.
- Target income plus resilience by searching through a hand picked 6 dividend fortresses that aim to pair higher yields with durable cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com