


How Investors May Respond To Vail Resorts (MTN) Board Challenge
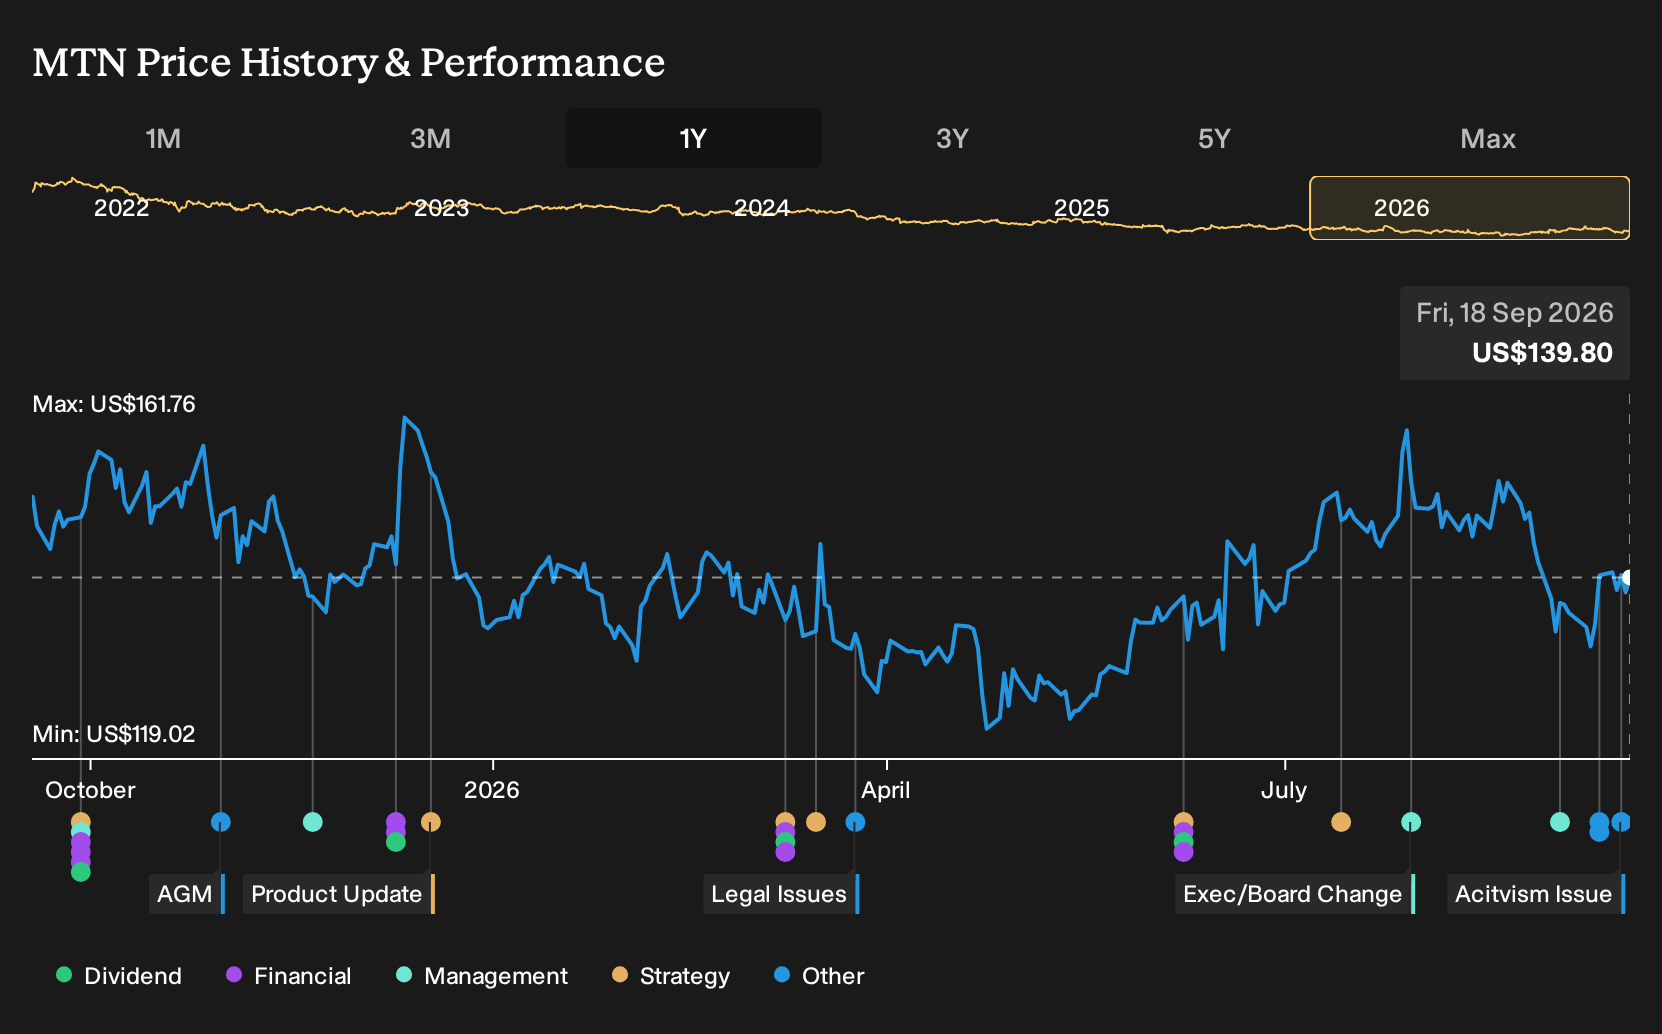
- Oasis Management has launched an activist campaign at Vail Resorts, nominating four director candidates after the 2026 nomination window closed and arguing that the company’s 42 mountain resorts and hospitality assets are not fully reflected in its current valuation.
- The activist fund is pushing for a refreshed board to refocus on guest experience, pricing, labor relations, and year round resort programming at a time when Epic Pass sales have reportedly decelerated and snowfall has become less predictable.
- This article will examine how Vail Resorts’ investment narrative relates to Oasis Management’s board initiative and its focus on guest experience.
Compare how Vail Resorts stacks up against other travel and leisure plays facing similar weather, pricing, and demand pressures by scanning our curated list of 33 high quality undervalued stocks
Vail Resorts Investment Narrative Recap
To own Vail Resorts, you need to believe its 42 mountain and lodging assets can keep pulling in high value guests even as snowfall becomes less predictable and visitation patterns shift. The near term focus is on Epic Pass trends and whether decelerating sales point to softer demand or just timing. That is the key operational catalyst to watch.
The biggest risk right now sits in weaker destination trips and labor friction at the same time pricing has moved higher and profit margins have compressed. Oasis highlighting guest experience, community ties, and year round programming could influence how quickly management tackles these operational pressure points.
The most relevant development is Oasis Management’s nomination of four directors, including Robert Chapek, after Vail Resorts’ own nomination window closed. That move puts specific pressure on the board to scrutinize pricing, pass strategy, and guest satisfaction just as UBS has flagged decelerating Epic Pass sales heading into fiscal 2027.
If activism leads to sharper execution on the Resource Efficiency Transformation Plan, better alignment of staffing with demand, and more thoughtful use of hospitality assets outside peak ski months, that could matter for the earnings path investors are underwriting. The flip side is distraction, potential governance disputes, and uncertainty around future dividend and capital allocation priorities.
Vail Resorts’ analyst narrative points to forecast revenue of US$3.2b and expected earnings of US$310.0 million by 2029, based on an assumed 4.2% yearly revenue growth rate and a move from current earnings of US$156.8 million to that 2029 consensus. This implies an earnings increase of about US$153 million over the period.
Uncover why Vail Resorts' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate view is how four season expansion at Vail Resorts could reshape the story. The most bullish analysts were penciling in about US$3.3b of revenue and US$363.2 million of earnings by 2029 before this Oasis campaign. Those forecasts look punchier than consensus and may shift as the activism plays out.
Explore 2 other Vail Resorts fair value estimates, including one that suggests as much as 93% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vail Resorts research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vail Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vail Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Vail Resorts?
If the Vail Resorts story has you thinking about portfolio upgrades, it can help to line it up against other opportunities that share some of the same themes such as quality, income, or resilience.
- For investors who want dependable income streams, scan companies that show up in our curated set of 6 dividend fortresses and see how their payouts compare.
- If balance sheet strength matters most to you, focus on businesses filtered through the list of solid balance sheet and fundamentals (23 results) to spot those with sturdier financial foundations.
- When you are hunting for lesser known opportunities with room to gain attention, sift through the 16 high quality undiscovered gems and see which stories you want to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com