


AI Chip Demand Might Change The Case For Investing In Ultra Clean Holdings Stock (UCTT)
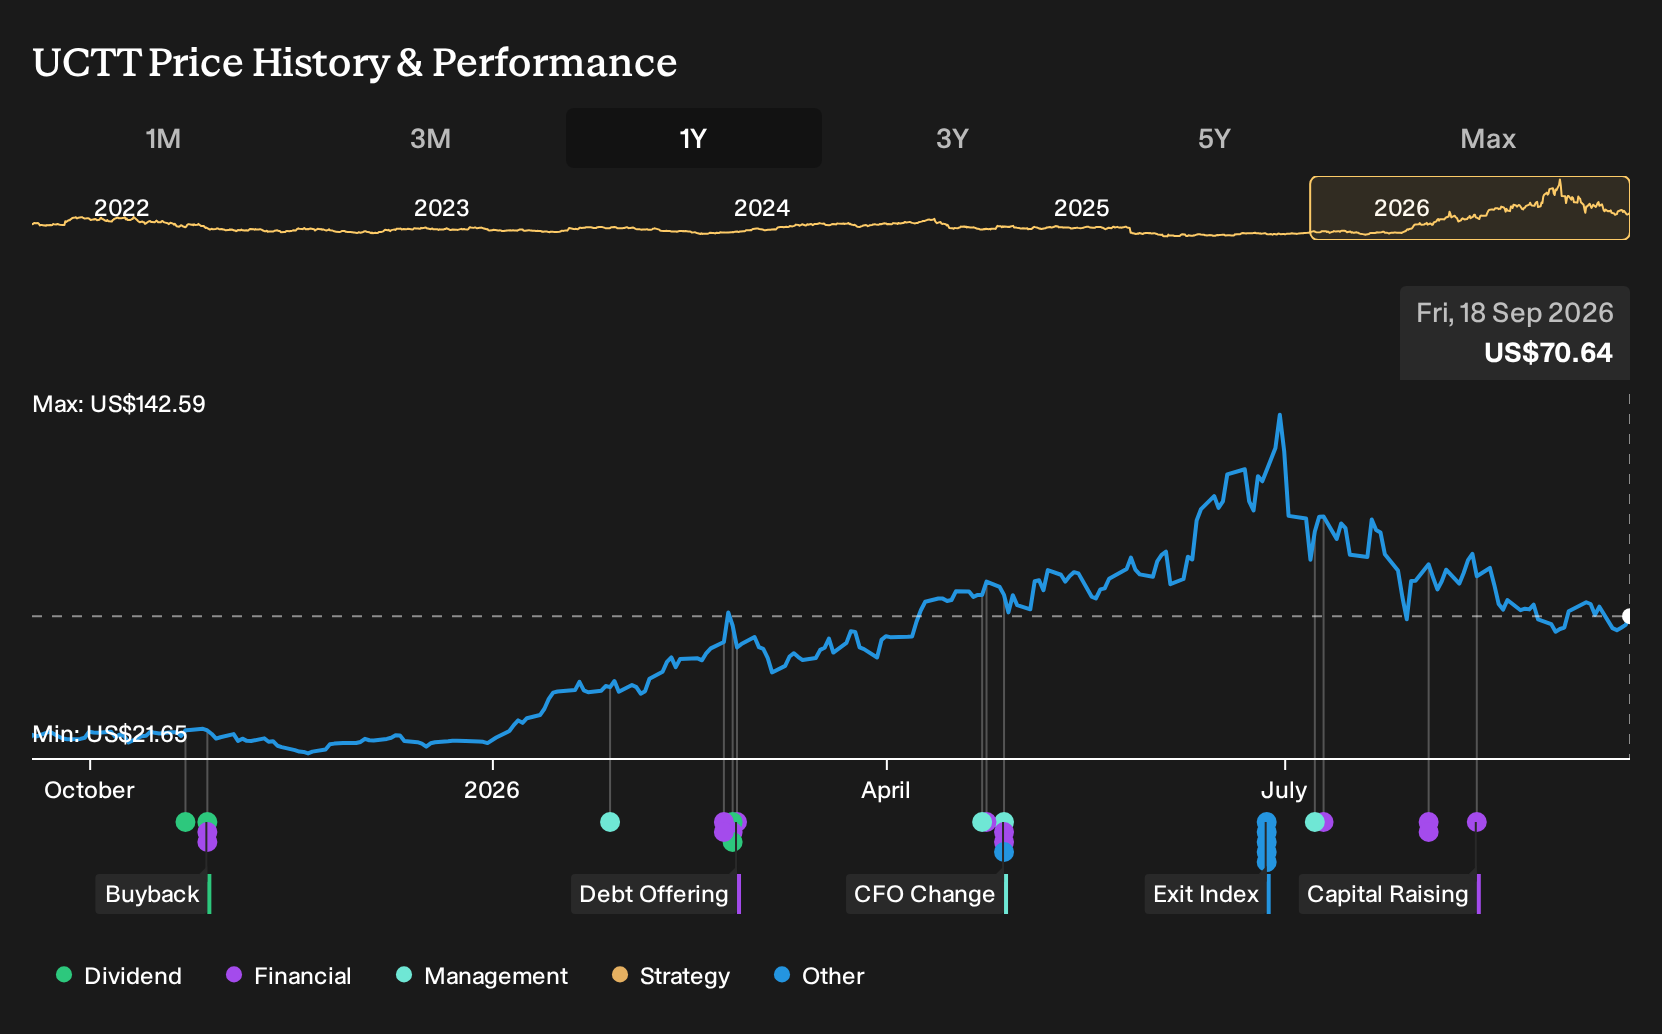
- Ultra Clean Holdings has seen strong business momentum over the past year, supported by healthy semiconductor demand tied to AI and advanced packaging needs.
- The company’s focus on AI-related subsystems and services has helped it align closely with areas of the chip supply chain seeing the most investment interest.
- We will now look at how Ultra Clean Holdings’ AI driven demand backdrop may reshape the broader investment narrative for the business.
Scan beyond Ultra Clean Holdings and see how other AI infrastructure suppliers are positioned by reviewing our curated list of 89 AI infrastructure stocks.
Ultra Clean Holdings Investment Narrative Recap
To own Ultra Clean Holdings, you need to believe the AI driven build out of advanced fabs and packaging will keep requiring its subsystems and cleaning services, and that current demand momentum can translate into steadier earnings over time. The recent share price move reflects that optimism but does not change the near term swing factor, which is order strength from a concentrated group of semiconductor customers.
The biggest risk still sits on the other side of that same equation. Customer concentration, industry cyclicality, tariff friction and operations running below initially scaled capacity all leave Ultra Clean Holdings exposed if AI related equipment spending cools or big accounts trim orders. Recent performance does not remove those pressures; it makes execution more important.
With no fresh company announcements tied directly to this AI related momentum, the clearest reference point remains management's existing plans to tighten costs, consolidate sites and deepen vertical integration, including the Fluid Solutions unit and SAP rollout. Those efforts are aimed at lifting efficiency and margins if semiconductor volumes hold up.
For you as a shareholder, the link is simple. If AI capital spending keeps flowing into advanced fabs, then new product qualifications, particularly at the Czech facility, cost cuts and services expansion could help Ultra Clean Holdings push closer to its previously scaled capacity and improve earnings quality. If those external drivers soften, the same fixed cost base, debt funded capital structure and tariff related expenses can work in the opposite direction.
Ultra Clean Holdings is modeled to reach US$4.5b in revenue and US$297.8m in earnings by 2029. That implies 26.9% yearly revenue growth and an earnings change of roughly US$321m, from a loss of US$23.4m today to the projected profit level.
Uncover why Ultra Clean Holdings' fair value indicates a 94% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on execution risk at Ultra Clean Holdings rather than AI demand strength. They worry that long customer qualification cycles and inventory overhang could cap revenue near US$4.1b and earnings around US$207.1m by 2029. That is far more cautious than consensus. Given the share price reaction to recent AI driven momentum, you may want to compare these older, more pessimistic assumptions with updated views once analysts fully react to the latest move.
Explore 3 other Ultra Clean Holdings fair value estimates, including one that suggests as much as 82% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ultra Clean Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ultra Clean Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ultra Clean Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ultra Clean Holdings?
If you want to apply the same kind of clear, numbers first thinking you used on Ultra Clean Holdings to the rest of your watchlist, the Simply Wall St Screener can help you quickly sort through thousands of companies by quality, valuation and risk profile.
- If you want potential mispricing with a margin of safety, consider starting with a curated set of 33 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- For income focused investing, you could scan a universe of reliable payers by reviewing our screener highlighting 6 dividend fortresses. This aims to balance yield with balance sheet strength.
- If capital preservation sits at the top of your checklist, filter for resilience first by working through a 30 resilient stocks with low risk scores. This concentrates on stronger finances and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com