


OceanaGold Stock And 2 Other Canadian Undervalued Stocks To Own
Higher interest rates in Japan, the US and Europe have pushed up borrowing costs globally, which also affects how investors price future cash flows. That kind of rate backdrop can leave some Canadian companies trading below what their long term cash generation suggests they are worth. This article walks through three Canadian stocks that currently screen as attractively priced on cash flows and explains what sets each one apart.
The three stocks that follow are only a small sample of the opportunities that screened as undervalued on cash flows, and the full list includes 0 more Canadian companies where the discounted cash flow work points to similarly interesting stories not covered here. To identify and analyze those additional ideas with the same framework used for this article, head straight to the Undervalued Stocks Based On Cash Flows screener.
OceanaGold (TSX:OGC)
OceanaGold is a Vancouver based miner focused on gold, with additional copper and silver, and its cash flow story is anchored in operating assets that feed directly into the undervalued on cash flows theme.
OceanaGold runs producing mines at Haile in the US, Waihi and Macraes in New Zealand, and Didipio in the Philippines, which together generated about $2.5b in segment revenue last period, and the group carries a market cap near $9.0b.
For value driven investors, OceanaGold matters because its producing assets already generate meaningful cash, and management is investing heavily to extend and deepen that stream rather than relying purely on higher gold prices.
Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, is expected by management to increase copper and gold output from an already low cost asset, with the goal of enhancing consolidated cash flow and margins.
The real swing factor is how one large capital program ultimately affects unit costs and the durability of those thicker margins.
If that capital program is what really moves the needle, the full narrative for OceanaGold shows how OceanaGold’s expansion plans, cost profile and risk trade offs fit together.
Savaria (TSX:SIS)
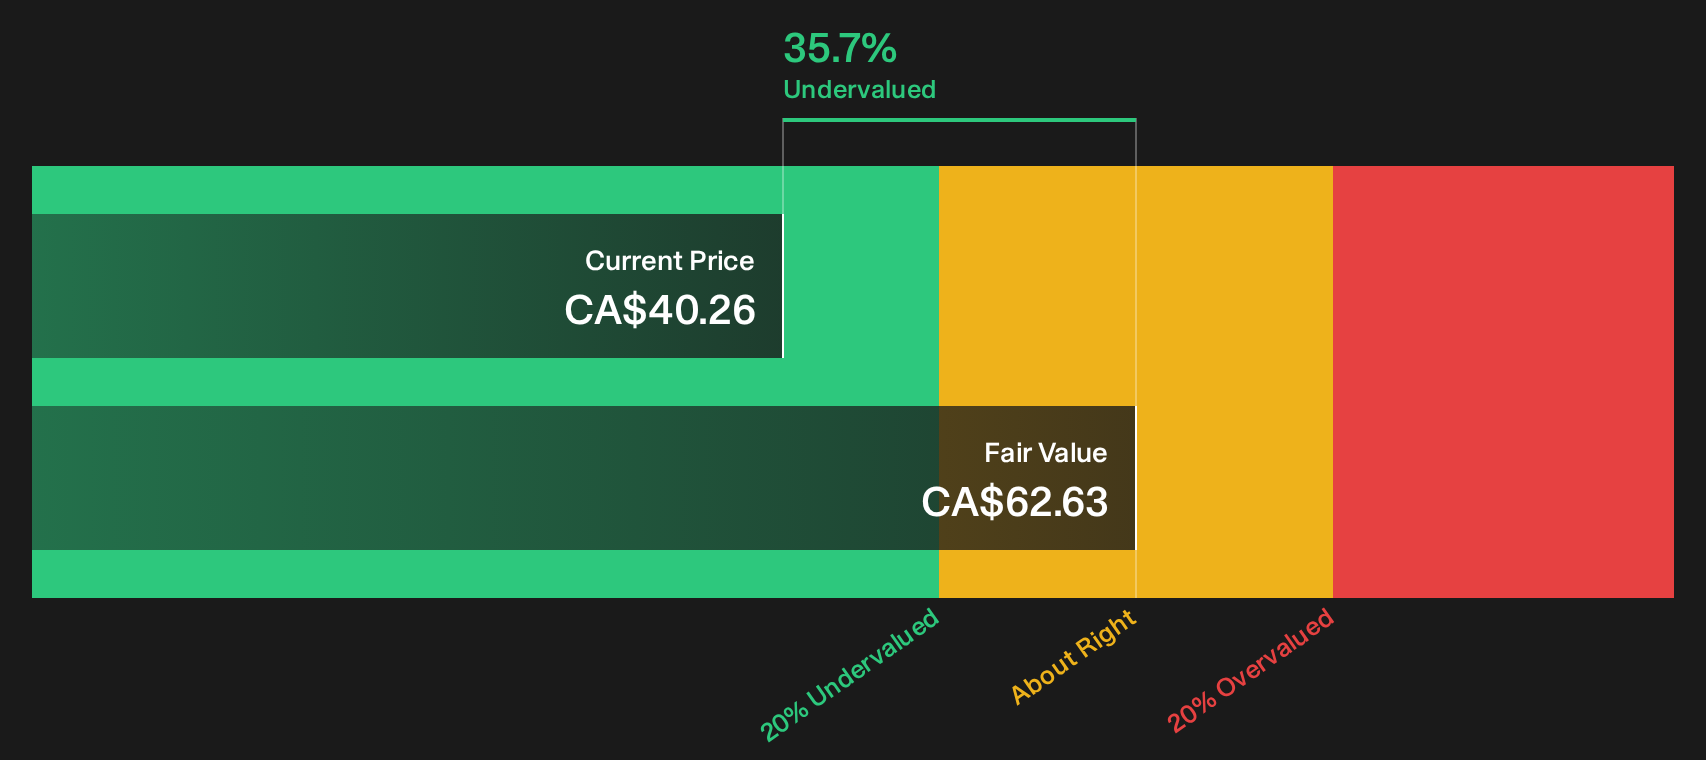
Savaria builds and installs accessibility equipment that helps people stay in their homes longer, which fits neatly with a cash flow focused screen because many of these products come with ongoing service work and repeat business tied to aging demographics.
Savaria generates about CA$739 million from Accessibility products and adapted vehicles and roughly CA$209 million from Patient Care equipment, with a market value near CA$2.1 billion.
Savaria interests value oriented investors because its accessibility cash flows are backed by long running demographic trends and a growing installed base that can support service and maintenance income over time.
Ongoing global demographic shifts, namely population aging and increased urban density, are expected to drive a sustained uptick in demand for home accessibility solutions (for example, elevators and stairlifts), positioning Savaria for long-term revenue growth as these trends intensify.
What matters next is how one pressure on future pricing power shapes the cash generation that underpins Savaria’s DCF valuation case.
That pressure point is exactly where the full narrative for Savaria zooms in, mapping how pricing power, capital intensity, and competition could be masking a stronger cash engine.
Suncor Energy (TSX:SU)
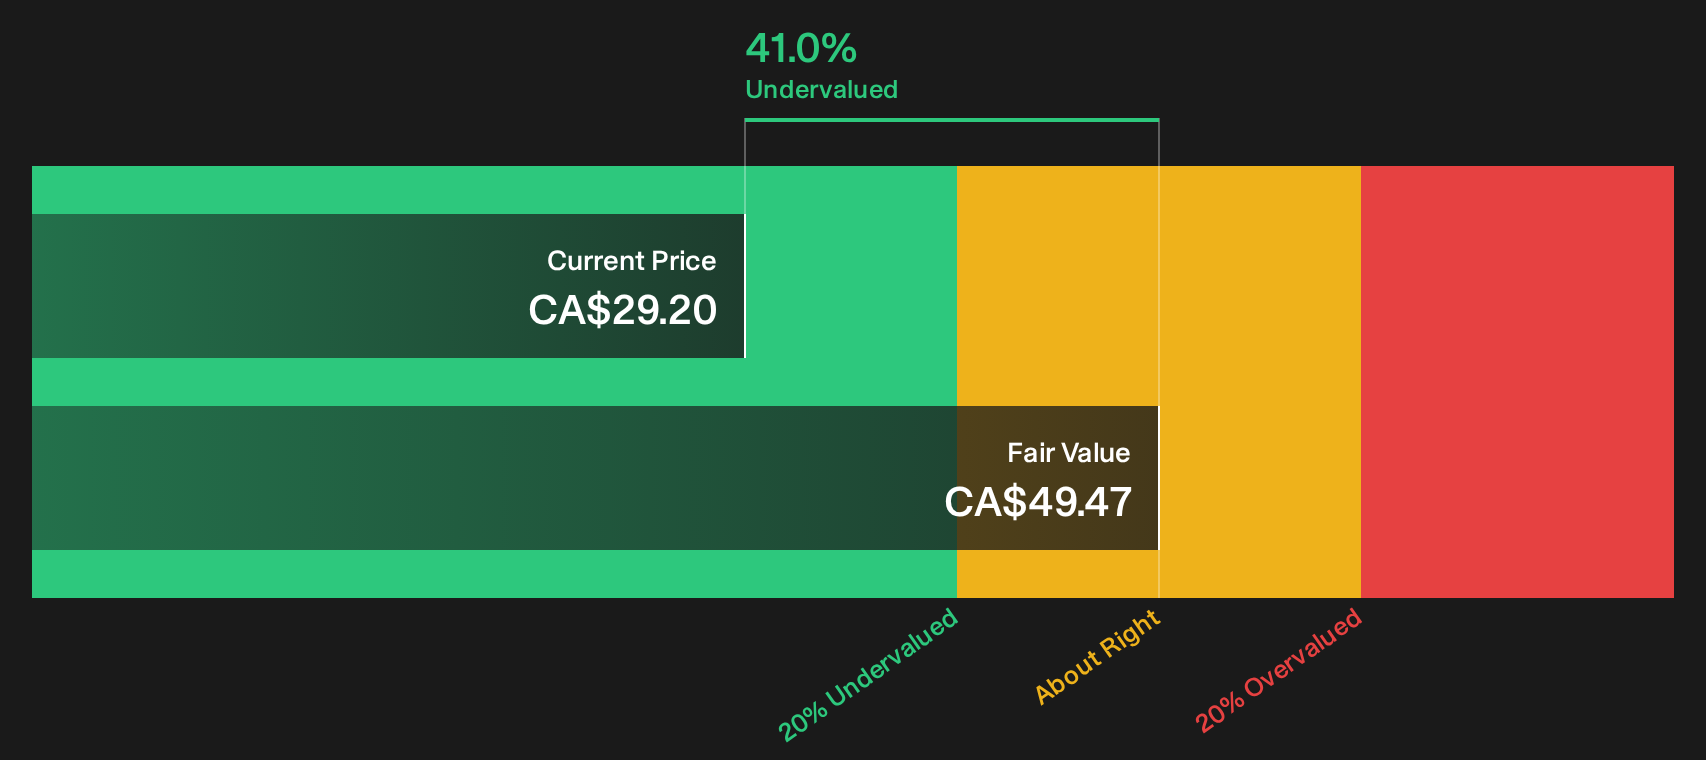
Suncor Energy is an integrated producer where the Oil Sands operations supply long lived bitumen output that feeds into its discounted cash flow story, while refining and marketing add a second cash engine that helps balance earnings through cycles for a business valued around CA$113.8b.
Oil Sands activities generated about CA$26.9b, refining and marketing brought in roughly CA$36.8b, and exploration and production added about CA$2.5b, with corporate and eliminations reducing the total by around CA$9.5b.
Suncor Energy ties into this undervalued on cash flows theme through its oil sands production, where long life projects underpin recurring cash generation that can be assessed over decades.
Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels.
What happens if a single assumption about how hard those assets can keep running begins to bend is what will really matter for margins.
If that assumption is what you are testing, the full narrative for Suncor Energy lays out how Suncor Energy’s cash flows could evolve if utilization and reliability start to decouple.
Seeking Alternatives Before They Fly Past
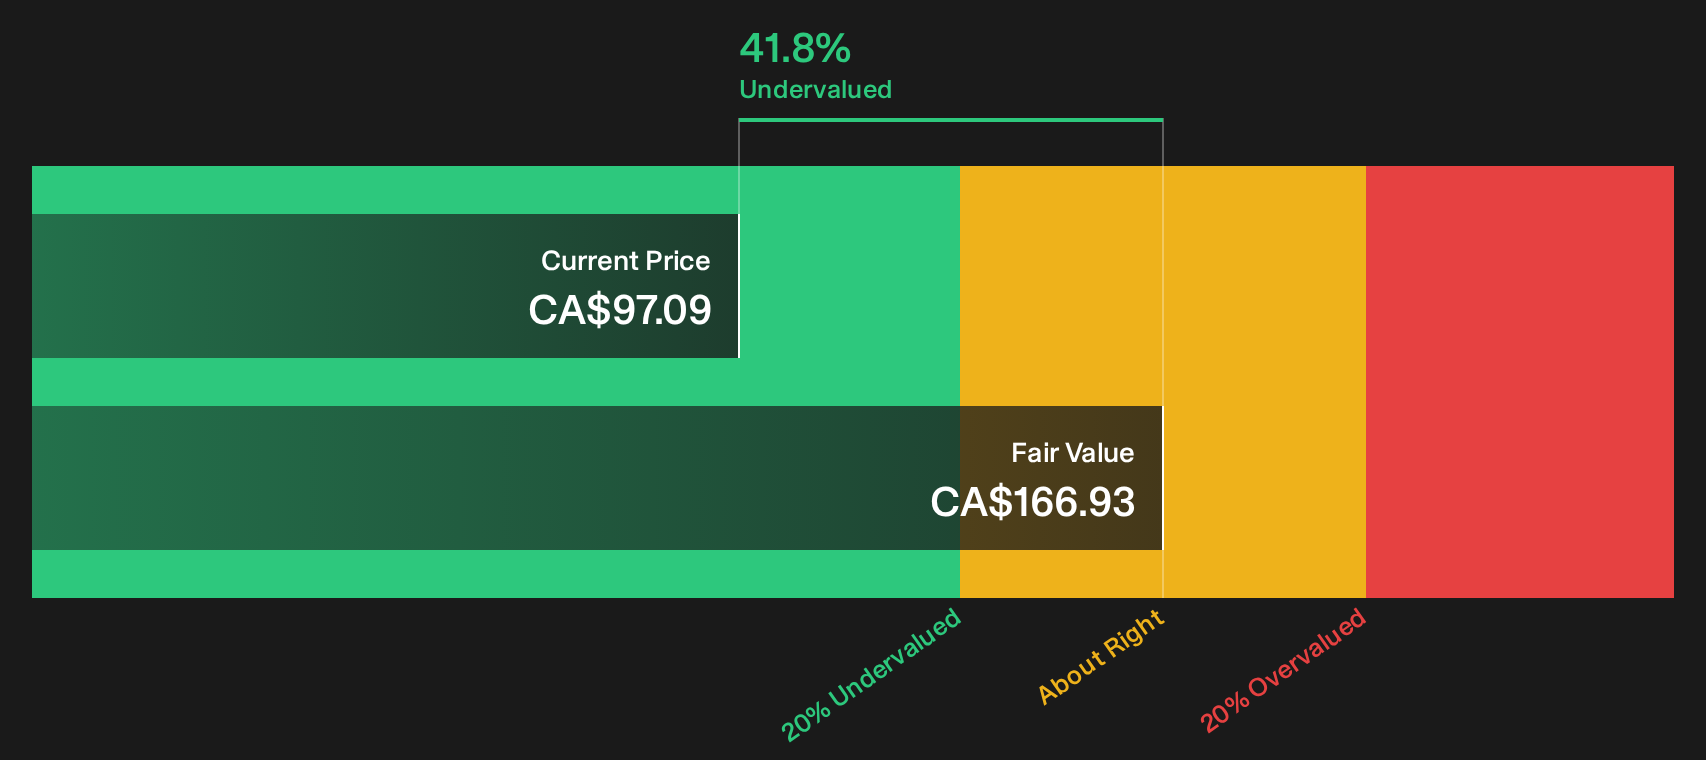
Fresh ideas can move from quiet to breakout quickly, and once momentum hits, ideal entry points get caught up fast. Scan these under the radar lists and get in early.
- Spot resilient cash generators that could hold up when others wobble by scanning a curated mix of 8 resilient stocks with low risk scores tuned for capital preservation with upside potential.
- Ride structural demand in critical materials by tracking carefully filtered 16 top copper producer stocks that support long term electrification and infrastructure themes while they are still priced for patience.
- Target durable income streams while prices are still dropping in and out of favor by reviewing hand picked 1 dividend fortresses built around robust payout histories and balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com