


Is Flat Sales And Lower Profit Altering The Investment Case For National Beverage (FIZZ)?
- National Beverage Corp. reported first quarter 2026 results, with sales of US$330.66 million roughly in line with a year earlier, while net income and earnings per share from continuing operations were lower than the prior period.
- The mix of steady revenue and softer profitability highlights potential pressure on costs or pricing for National Beverage, even as demand levels appear relatively unchanged.
- Next, the focus shifts to how National Beverage’s steadier sales but weaker earnings shape the broader investment narrative and risk profile.
Look past National Beverage’s flatter first quarter and evaluate other consumer staples with resilient demand and tighter cost control using our curated list of list of solid balance sheet and fundamentals (23 results).
What Is National Beverage's Investment Narrative?
To own National Beverage, you need to believe in a relatively simple story. A focused beverage portfolio, led by LaCroix, can keep demand steady enough for modest earnings growth over time, even if the broader US market grows faster. The latest quarter fits that script. Sales of US$330.66 million were essentially flat versus a year earlier, while net income of US$47 million and EPS of US$0.50 softened, which points more to pressure on costs and mix than a demand problem.
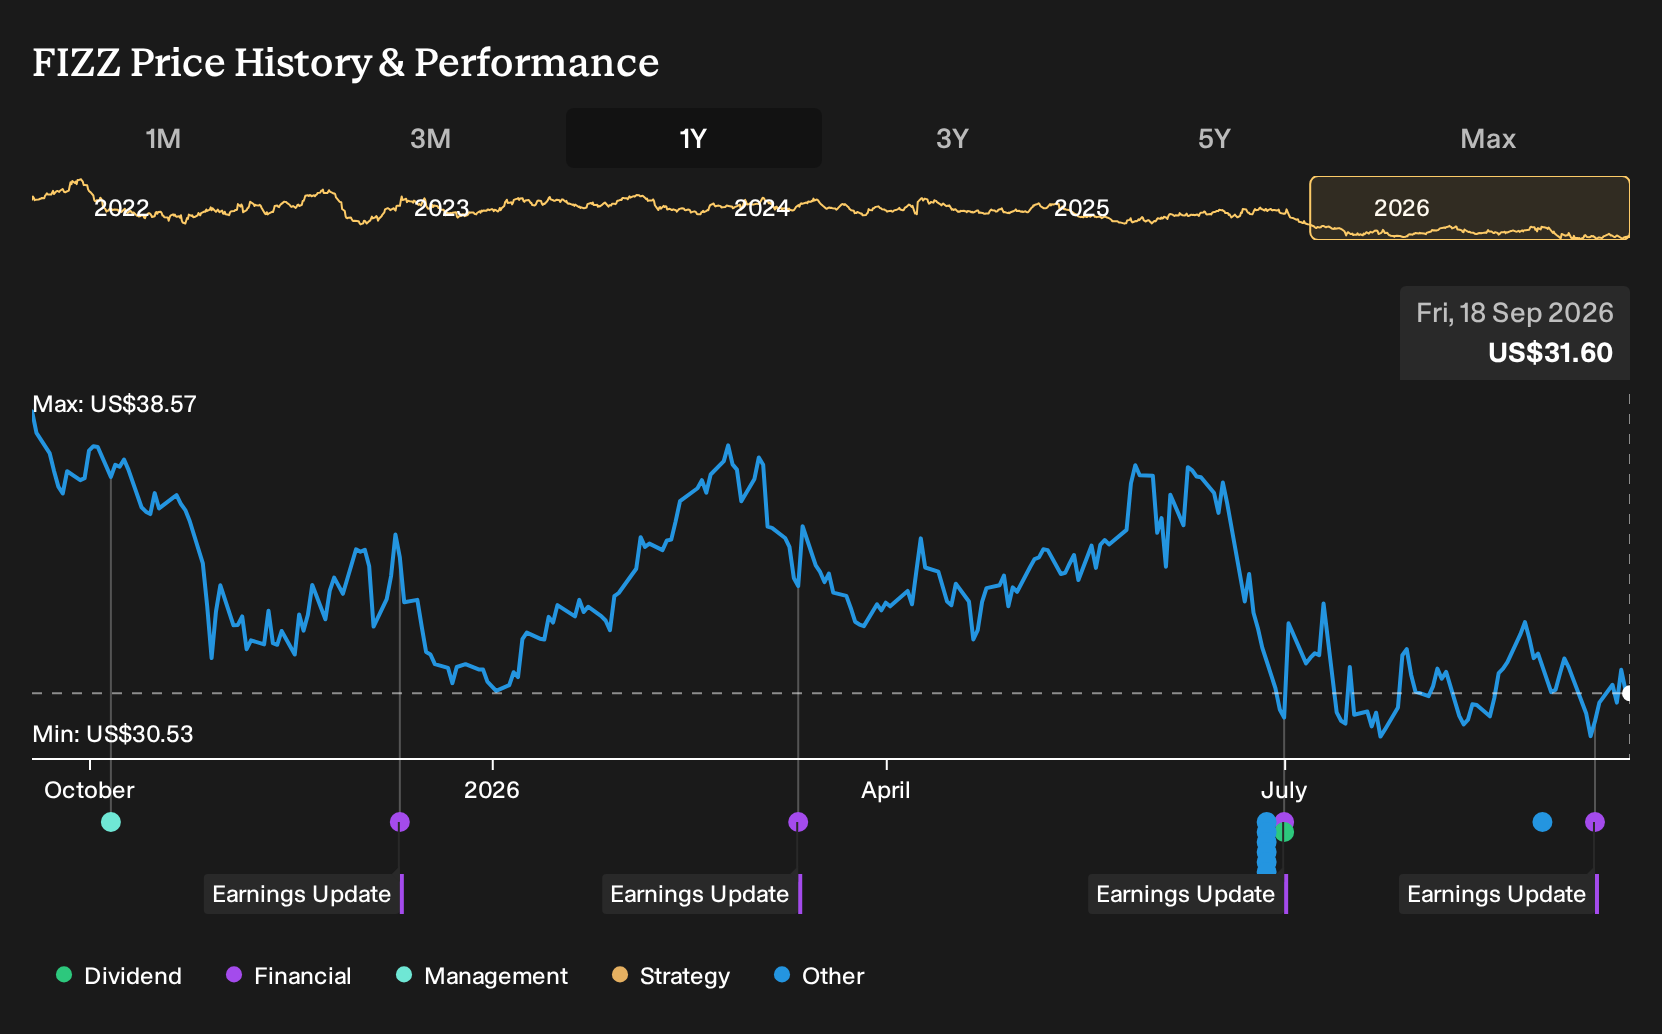
In the short term, the key question is whether management can protect margins without leaning too hard on pricing in a competitive category. The business is not especially capital intensive, so execution sits more in product, promotion and cost discipline than in heavy investment cycles. Recent share performance, with the stock down over the past year, suggests the market is already weighing slower forecast growth and a P/E that screens close to industry levels, even as some valuation models see a discount to estimated cash flow value.
Even so, there is a less obvious pressure point in the National Beverage story that only really shows up when you focus on ...
There's only one way to know the right time to buy, sell or hold National Beverage. Head to Simply Wall St's company report for the latest analysis of National Beverage's Fair Value.
Exploring Other Perspectives
National Beverage attracts only 2 fair value estimates from the Simply Wall St Community, clustered between US$31 and about US$35.95. That tight band still reflects different conviction levels, especially now that first quarter earnings and EPS are softer. Treat these views as starting points and compare several alternative opinions before acting.
Explore another National Beverage fair value estimate, including one that suggests it could be worth just $31.00.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for National Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Beverage?
If this update on National Beverage has you rethinking where you want earnings quality and balance sheet strength to come from, it can help to line it up against a broader watchlist built around clear filters.
- For investors who want potential upside without abandoning financial discipline, consider a curated set of companies that screen as 16 high quality undiscovered gems.
- If capital preservation and steadier profiles matter more to you right now, focus on businesses that score well in our 30 resilient stocks with low risk scores.
- Income focused readers who care about durability as much as yield can compare National Beverage with companies in the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com