


How Clean Energy Spending Will Impact Xcel Energy Stock Investors
- Xcel Energy is pushing ahead with a large clean energy and grid investment program that is supported by policy-driven decarbonization targets for carbon-free generation by 2030 and by rising electricity demand across its service territories.
- The utility’s recent operational focus highlights how long-term infrastructure spending, rather than short-term share moves, is shaping Xcel Energy’s earnings profile and capital needs.
- We will now explore how Xcel Energy's clean energy buildout and heavy infrastructure spending could influence its broader investment narrative.
Scan other grid and clean-energy plays that are riding similar demand and policy trends by reviewing our curated list of 38 power grid technology and infrastructure stocks.
Xcel Energy Investment Narrative Recap
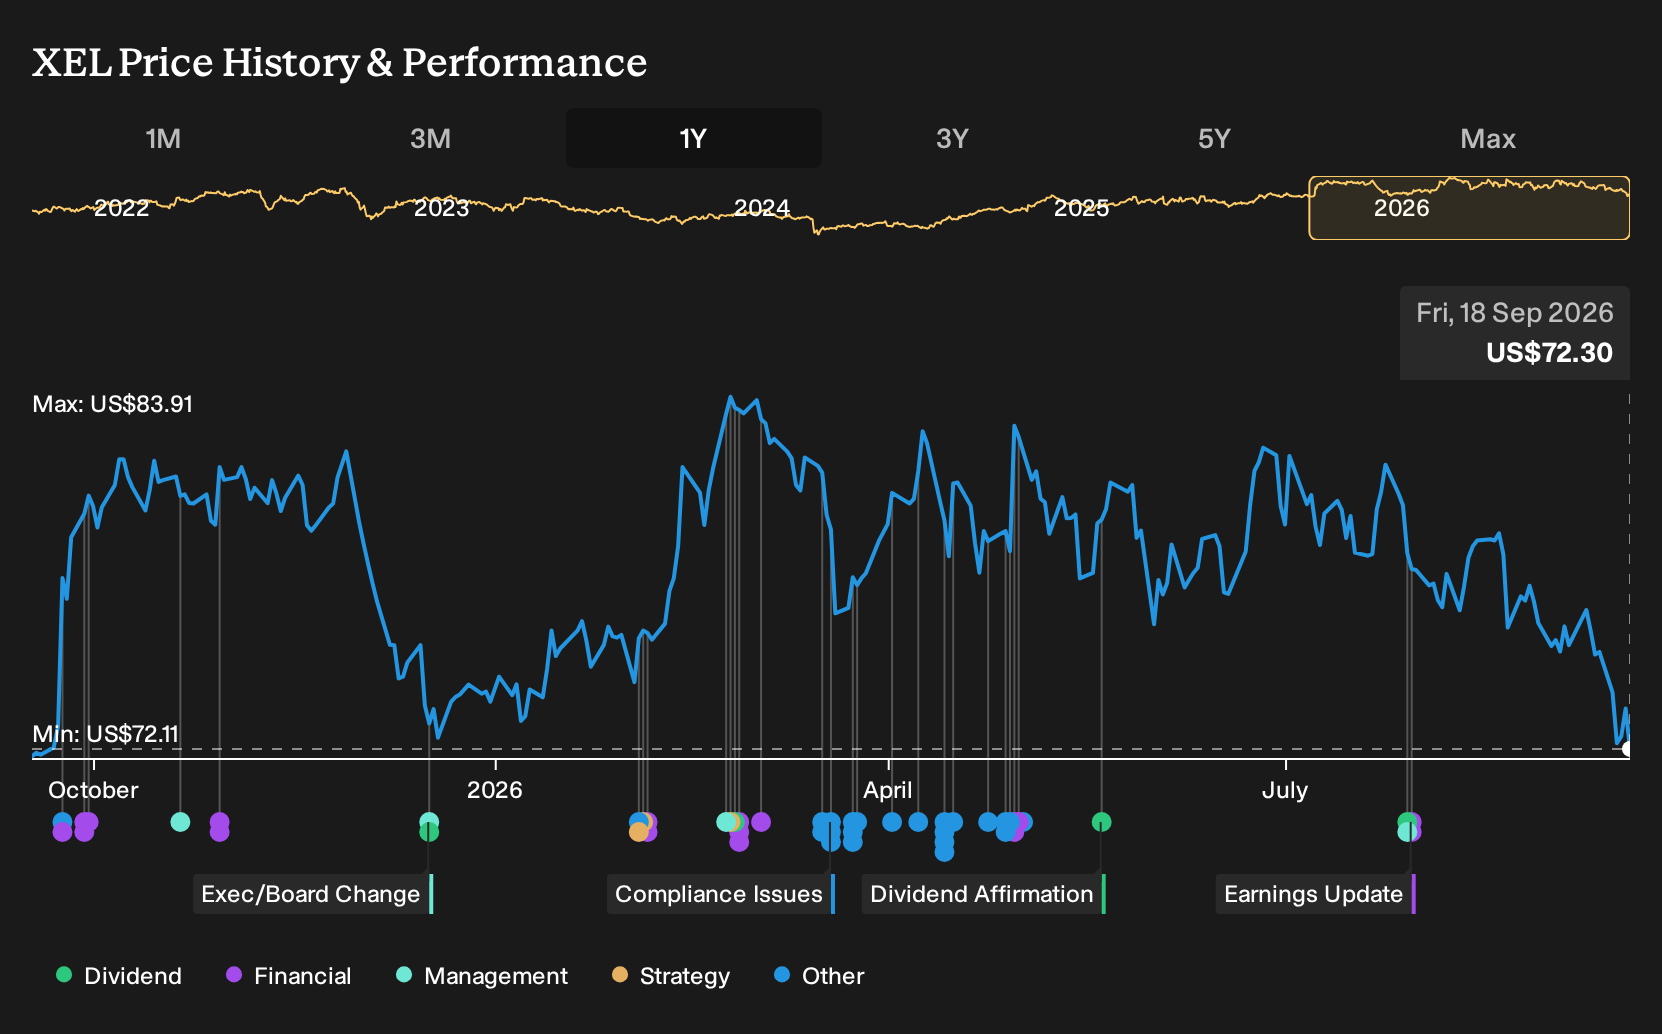
To own Xcel Energy, you need to be comfortable with a heavily regulated utility leaning into a huge clean energy and grid buildout. The thesis rests on electricity demand, policy support for decarbonization, and a long runway of capital projects that feed into the regulated asset base. Recent share weakness does not materially change that core story; it does, however, underline how sentiment can swing faster than fundamentals.
In the near term, the key catalyst is clear execution on those large projects and on rate cases that convert spending into allowed returns. The biggest risk is financial strain from more than $15b of extra capital needs funded with debt and equity, alongside wildfire liabilities and interest costs that are not fully covered by earnings.
Recent commentary around Xcel Energy has focused on the clean energy investment cycle that underpins the current valuation and analyst expectations for earnings. That program is closely tied to policy-supported goals for more than 80% carbon-free generation by 2030 and to grid upgrades for data centers, electrified transport, and heating. For you, the immediate operational watchpoint is whether those projects stay on time and on budget.
That same buildout is also where the main execution risks sit. Every large wind, solar, storage, or transmission asset needs regulatory approval across several states, which can affect the timing of revenue recognition and margins. Combined with equity issuance, interest coverage pressure, and wildfire litigation, the success of this investment cycle will largely determine whether the demand story translates into durable earnings growth.
Xcel Energy's current analyst narrative points to revenue of $19.1 billion and earnings of $3.4 billion by 2029, based on forecast revenue growth of 8.8% a year. That path assumes earnings today of $2.1 billion and an increase of about $1.3 billion to reach the 2029 consensus mark.
Uncover why Xcel Energy's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community contributors have three fair value estimates for Xcel Energy clustered between about $71.81 and $91.39 a share, so opinions are already spread across a wide band. Those views do not yet reflect the current infrastructure cycle, wildfire liabilities, or rate case outcomes. Other investors may interpret those same swing factors very differently, so explore several viewpoints before deciding how Xcel fits your portfolio.
Explore 2 other Xcel Energy fair value estimates, including one that suggests it could be worth just $71.81.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Xcel Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Xcel Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xcel Energy's overall financial health at a glance.
Looking for more Xcel Energy style investment ideas?
If the Xcel Energy story has you thinking about where else long term themes, balance sheet strength, or income potential might show up, the Simply Wall St screener is a useful way to cast a wider net without losing focus.
- For investors who want quality at a sensible entry point, scan a curated set of companies flagged as trading below their assessed worth with our 33 high quality undervalued stocks.
- If steadier sleep and capital protection matter most to you, start with businesses that carry stronger financial resilience scores by reviewing this 30 resilient stocks with low risk scores.
- For those who care about fundamentals and durability before anything else, filter for companies with robust finances using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com