


Agilysys (AGYS) Stock Dropped, So What Is Driving Attention Now?
Agilysys (AGYS) is back on investors’ radar after Chief Financial Officer Dave Wood outlined its subscription heavy hospitality software push at Piper Sandler’s Growth Frontiers Conference in Nashville on September 14.
Recent trading tells a mixed story for Agilysys. The share price has eased in the short term, with a 1-day move down of 2.04% and a 30-day share price return down 14.21%. However, momentum over the last quarter remains positive with a 90-day share price return up 14.42% and a 5-year total shareholder return of 90.22%, pointing to a much stronger long-run journey for investors.
Scan beyond Agilysys and see how other recurring revenue software players with solid fundamentals are shaping up inside our hand picked list of solid balance sheet and fundamentals (23 results)
Agilysys has already delivered a strong multi year run, yet the recent pullback and fresh subscription metrics leave a live question: Is most of the upside already in the rear view mirror, or does valuation still leave room ahead?
Most Popular Narrative: 25% Undervalued
On the most followed narrative, Agilysys screens as undervalued, with a fair value of $133.67 against a last close of $100.13, so the story hinges on whether subscription and margin assumptions hold up.
The company's focused and increasingly differentiated AI driven enhancements (such as personalized upselling, dynamic pricing, and AI powered guest engagement tools) are expected to meaningfully elevate product value, drive upsell opportunities, and improve operational efficiency, positively impacting both revenue growth and net margins.
See why 7 investors see Agilysys as 25% undervalued.
Result: Fair Value of $133.67 (UNDERVALUED)
Still, the Agilysys story can be knocked off course if hospitality spending slows or if tougher point of sale competition reduces new deals and pricing power.
Find out about the key risks to this Agilysys narrative.
Another View On Agilysys Valuation
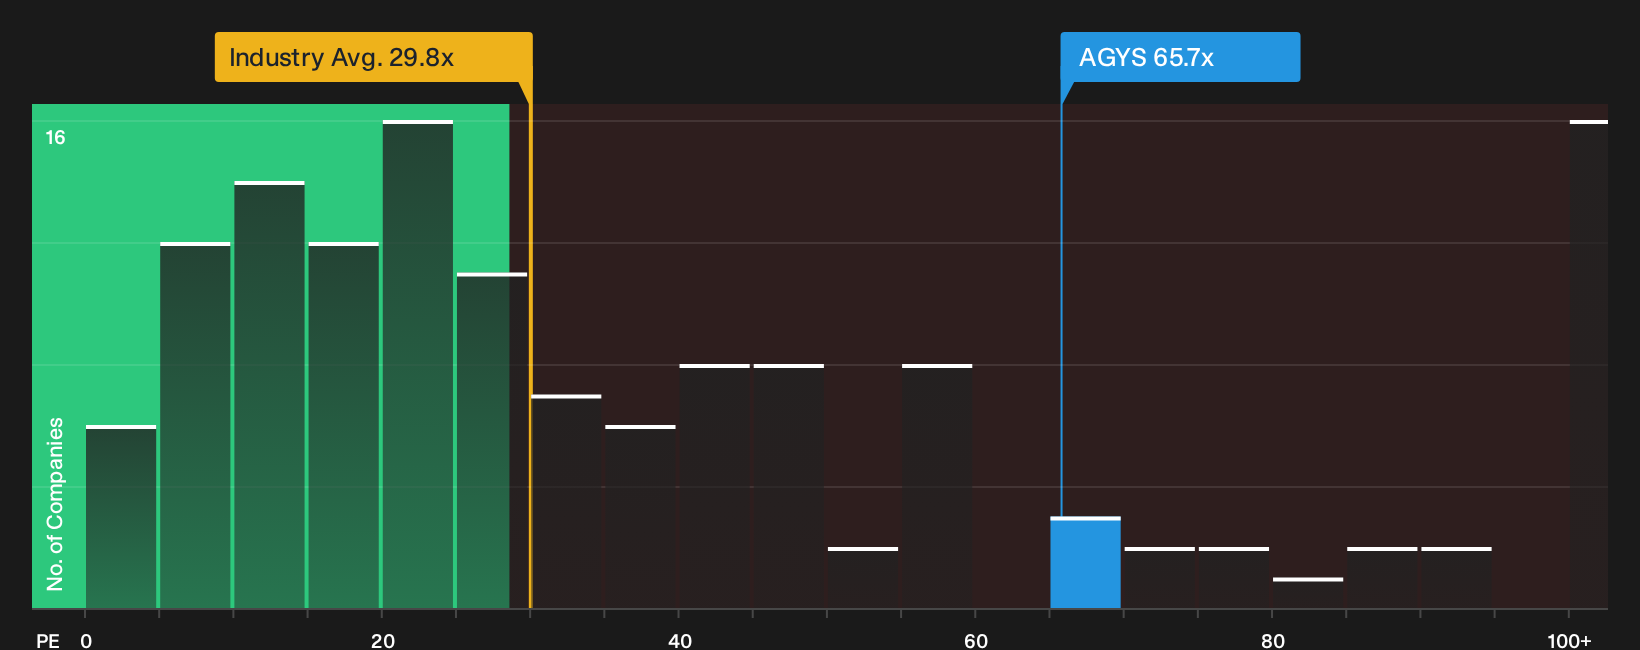
On a multiples check, the picture looks tougher. Agilysys trades on a P/E of 65.7x, which is well above both the US Software sector average of 29.8x and peers at 35.8x. It also sits far above the 34x fair ratio, so the key question is how comfortable you are paying that kind of premium.
For a closer look at how this pricing gap could close over time, see what the numbers say in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism and a fair bit of concern sit side by side in the Agilysys story. Move quickly, inspect the full risk and reward mix, and decide where you stand after weighing the 4 key rewards and 1 important warning sign.
Looking for more Agilysys sized investment ideas?
Do not stop at Agilysys. Broaden your watchlist with fresh opportunities that match your style before others start paying attention to the same setups.
- Target potential mispricing by scanning a curated set of quality stocks that screen as undervalued using the Simply Wall Street tool 33 high quality undervalued stocks.
- Prioritise staying power by focusing on businesses with robust finances through a purpose built list of solid balance sheet and fundamentals (23 results).
- Hunt for off the radar potential by filtering for stronger fundamentals inside a focused 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com