


Unusual Machines (UMAC) Reshoring Push Puts Its Valuation Story Back In Focus
Recent coverage around Unusual Machines (UMAC) centers on how the drone components specialist is scaling US manufacturing to align with government-backed reshoring and defense spending. This development is prompting investors to reassess the stock’s risk and reward profile.
The share price of Unusual Machines has pulled back over the past month, with a 30 day share price return down 18.09% and a 90 day share price return lower by 7.21%. This comes even though the year to date share price return is up 70.82% and the 1 year total shareholder return is 76.95%. This points to strong longer term momentum but some recent cooling as investors weigh the benefits of reshoring and upcoming conference appearances against higher expectations baked into the current US$23.18 share price.
Scan beyond Unusual Machines and compare its reshoring and defense story with other hand picked 95 robotics and automation stocks positioned around automation, unmanned systems, and hardware tied to government-backed demand.
After such a sharp pullback yet still strong gains over 12 months, Unusual Machines now sits at a fork in the road. Is the better move to step in at US$23.18 today, or keep cash waiting for a deeper reset as the valuation picture comes into focus next?
Most Popular Narrative: 41% Undervalued
Analyst models currently anchor Unusual Machines at a fair value of about $39 per share, well above the last close at $23.18. This puts the focus firmly on whether ambitious growth and reshoring themes can justify that gap.
The accelerating adoption of automation, robotics, and IoT, combined with the explosion of the U.S. drone market and increased demand for advanced, NDAA-compliant components, expands Unusual Machines'' long-term addressable market beyond just drones to broader smart hardware and embedded electronics, positioning the company for durable, above-market revenue growth well into the future.
See why 40 investors see Unusual Machines as 41% undervalued.
This widely followed narrative applies an 8.84% discount rate and arrives at a fair value of $39, which is 40.6% above the modeled intrinsic level implied by the latest Simply Wall St work. That framework leans heavily on very rapid projected revenue expansion, improving profit margins from current losses, and the idea that domestic, NDAA-compliant drone components could support a long runway of demand.
Analysts feeding into this storyline expect Unusual Machines to move from a net loss of $6.5 million today to earnings of $11.2 million by around August 2029, with revenue assumptions of $227.4 million in the same time frame. To connect those earnings to the current fair value estimate, the models use an implied future P/E of about 274x, which is far higher than the 30.3x level cited for the wider US Electronic industry in the narrative.
The same narrative also assumes annual revenue growth of 92.6% over the next three years and revenue growth of 39.8% per year beyond that, as well as a profit margin shifting from a negative 20.3% to a positive 4.9%. Those inputs feed into discounted cash flow style work where future cash generation is projected forward and then brought back to today using the 8.84% discount rate, producing the $39 output that anchors the current fair value view.
Investors weighing this against the $23.18 share price may want to compare their own expectations around government contract timing, manufacturing ramp up, and balance sheet use with the underlying assumptions in the narrative, including the expectation of meaningful share count growth of 7% per year for the next three years. The wider Simply Wall St coverage stresses that readers should sense check the analyst case against their own reading of the business, especially given the high implied valuation multiple and the company’s current unprofitable status.
Result: Fair Value of $39.00 (UNDERVALUED)
Still, the bullish Unusual Machines narrative leans heavily on timely U.S. government orders and flawless factory ramp up. Setbacks on either front could quickly challenge it.
Find out about the key risks to this Unusual Machines narrative.
Another Take On Unusual Machines' Valuation
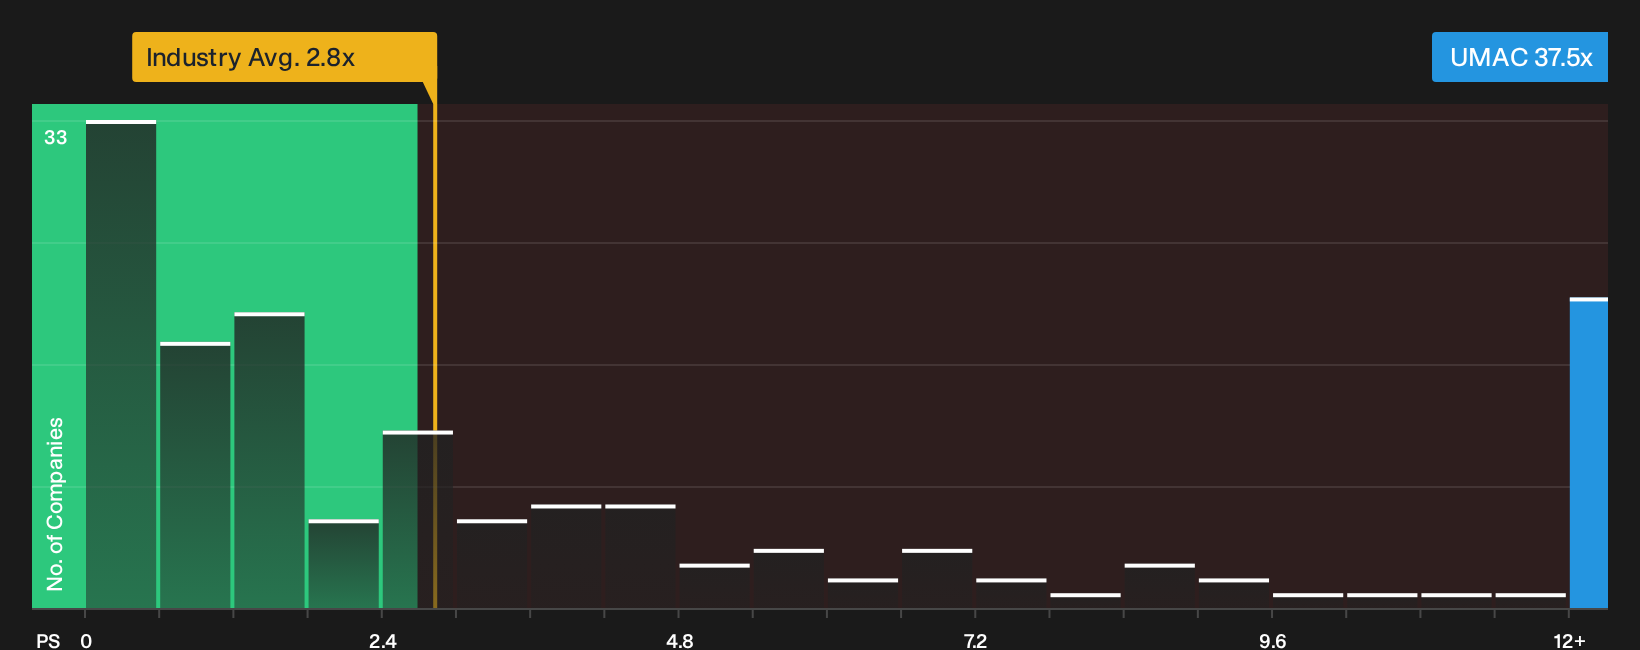
The analyst narrative frames Unusual Machines as roughly 41% undervalued at $23.18, based on future earnings assumptions and a high implied P/E. A simple P/S check tells a very different story. UMAC trades on a P/S of 37.5x, compared with a fair ratio of 5.7x, the US Electronic industry at 2.8x, and peers around 20x. That gap signals a lot of optimism already in the price. The question is which reference point to rely on more when real cash flow is still in the future.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Unusual Machines after all this. If you want to move fast but think for yourself, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Unusual Machines?
Use this Unusual Machines work as a launchpad. Then widen your watchlist with fresh ideas sourced from structured screeners built to surface clear, testable themes.
- Target potential mispricing by scanning a curated pool of companies that combine quality with appealing valuations through the 29 high quality undervalued stocks.
- Fortify your income focus by filtering for companies with stronger balance sheets that support reliable payouts using the 6 dividend fortresses.
- Spot future contenders early by tracking financially sound businesses that remain off most radars with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com