


EastGroup Properties (EGP) Rides Sunbelt Demand As Valuation Stays In Focus
EastGroup Properties (EGP) is back on watch after its recent pricing at US$201.63, with investors weighing the REIT’s exposure to high growth industrial hubs against its latest short term share moves.
Recent trading has tilted positive, with a 1-day share price return of 1.90% and a 7-day share price return of 2.51%. EastGroup Properties still carries a 12.08% year to date share price gain and a 1-year total shareholder return of 23.83%, indicating that while momentum has cooled from earlier strength, sentiment toward the REIT remains constructive overall.
Scan how EastGroup Properties compares with other industrial-focused real estate plays by reviewing a curated set of list of solid balance sheet and fundamentals (23 results).
EastGroup Properties now has a solid long-term track record and a portfolio tailored to high-growth industrial markets. After the recent move higher, is that quality already fully reflected in the current US$201.63 price, or not?
Most Popular Narrative: 11% Undervalued
On the most followed view, EastGroup Properties screens as undervalued, with a fair value of about $227.45 against the latest $201.63 close. This puts the focus squarely on how its industrial portfolio can support that gap.
Structural US population growth and migration to Sunbelt markets continues to underpin robust demand for modern industrial/logistics properties, directly benefiting EastGroup's core portfolio and positioning the company for sustained revenue and NOI growth as these regions outpace national averages.
Persistent e-commerce expansion and ongoing supply chain modernization are ensuring elevated leasing spreads and high occupancy in EastGroup's infill, last-mile logistics facilities, supporting above-average rental rate growth and driving resilient net margins.
See why 7 investors see EastGroup Properties as 11% undervalued.
Result: Fair Value of $227.45 (UNDERVALUED)
Still, the bullish EastGroup Properties story leans on a few pressure points, including tenant health in weaker regions and the risk of higher funding costs affecting future projects.
Find out about the key risks to this EastGroup Properties narrative.
Another View on EastGroup Properties Valuation
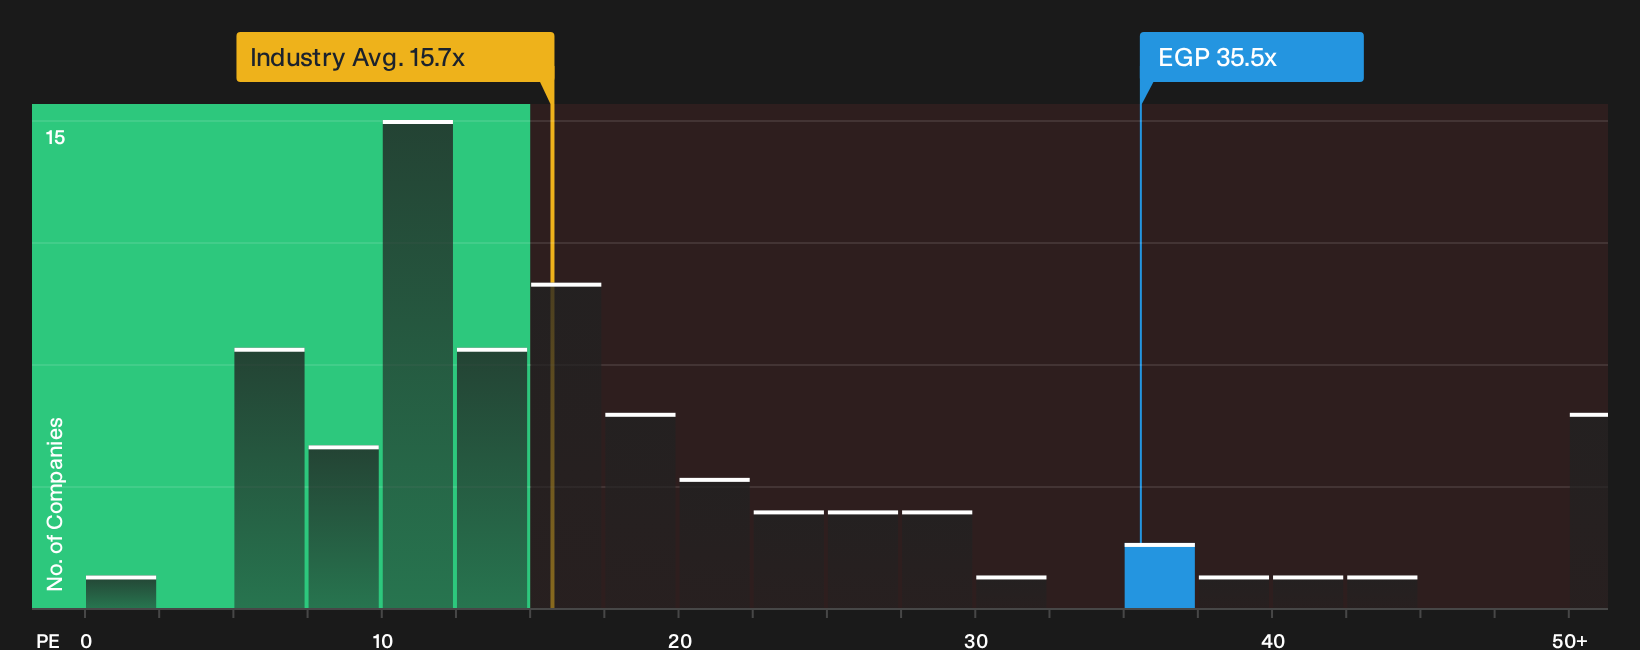
A different lens tells a less generous story. EastGroup Properties trades on a P/E of 35.5x, compared with 15.5x for the global Industrial REITs group and a fair ratio of 33.5x. That premium points to valuation risk if growth or sentiment cools even modestly.
It is worth asking whether this premium multiple is backing real quality or just stretching expectations. Our valuation breakdown helps you test this against your own assumptions, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone on EastGroup Properties leaves you unsure, consider acting while the data is fresh and forming your own view by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond EastGroup Properties?
Do not stop with EastGroup Properties. Broaden your watchlist now and let fresh ideas challenge your assumptions before the next round of price moves.
- Target potential mispricing by scanning a curated set of 29 high quality undervalued stocks that may offer stronger fundamentals than the headlines suggest.
- Prioritise resilience by reviewing 30 resilient stocks with low risk scores that score well on balance sheet strength and more consistent business profiles.
- Get ahead of the crowd by tracking 16 high quality undiscovered gems that combine solid financials with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com