


Fortum Oyj (HLSE:FORTUM) Could Be 18% Overvalued As Google Deal Reshapes Its Outlook
Fortum Oyj (HLSE:FORTUM) just reshaped its long term power story with Google in Finland, signing a multi decade power purchase agreement tied to the Loviisa nuclear plant through 2050.
Investors have already been leaning into the Fortum Oyj story, with the share price at €24.54 and a 30 day share price return of 23.35% feeding into a 32.65% year to date gain. Meanwhile, the 1 year total shareholder return of 67.93% and 3 year total shareholder return of 168.62% point to momentum that the new Google partnership is likely reinforcing rather than creating from scratch.
Scan 37 power grid technology and infrastructure stocks benefiting from long-term data center demand and low carbon power deals, similar to Fortum Oyj's new partnership with Google in Finland.Fortum Oyj now has a long term Google contract, a nuclear asset anchored through 2050 and a share price that has already re-rated hard. Does the current valuation still leave enough upside for new buyers?
Most Popular Narrative: 20% Overvalued
Against the last close of €24.54, the most followed narrative pegs Fortum Oyj's fair value at €20.37. This suggests a market price sitting well above that estimate while still reflecting solid earnings expectations and data center upside.
The analysts have a consensus price target of €20.37 for Fortum Oyj based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of €24.1, the analyst price target of €20.37 is 18.3% lower. Despite analysts expecting the underlying business to improve, they seem to believe the market's expectations are too high.
See why 7 investors see Fortum Oyj as 20% overvalued.
Result: Fair Value of €20.37 (OVERVALUED)
Still, Fortum Oyj could surprise if its €100m fixed cost reduction program lands cleanly and data center PPAs turn that 8 GW project pipeline into steadier cash flows.
Find out about the key risks to this Fortum Oyj narrative.
Another View: Fortum Oyj Through The DCF Lens
While analyst targets suggest Fortum Oyj is about 20% overvalued at €24.54 versus a €20.37 fair value, the SWS DCF model points in the opposite direction. On that approach, Fortum trades at roughly a 47% discount to an estimated future cash flow value of €45.92, which presents the current price as far more cautious than the earnings based narrative implies. Which perspective do you think better reflects the risk and reward you see in the business?
Look into how the SWS DCF model arrives at its fair value.
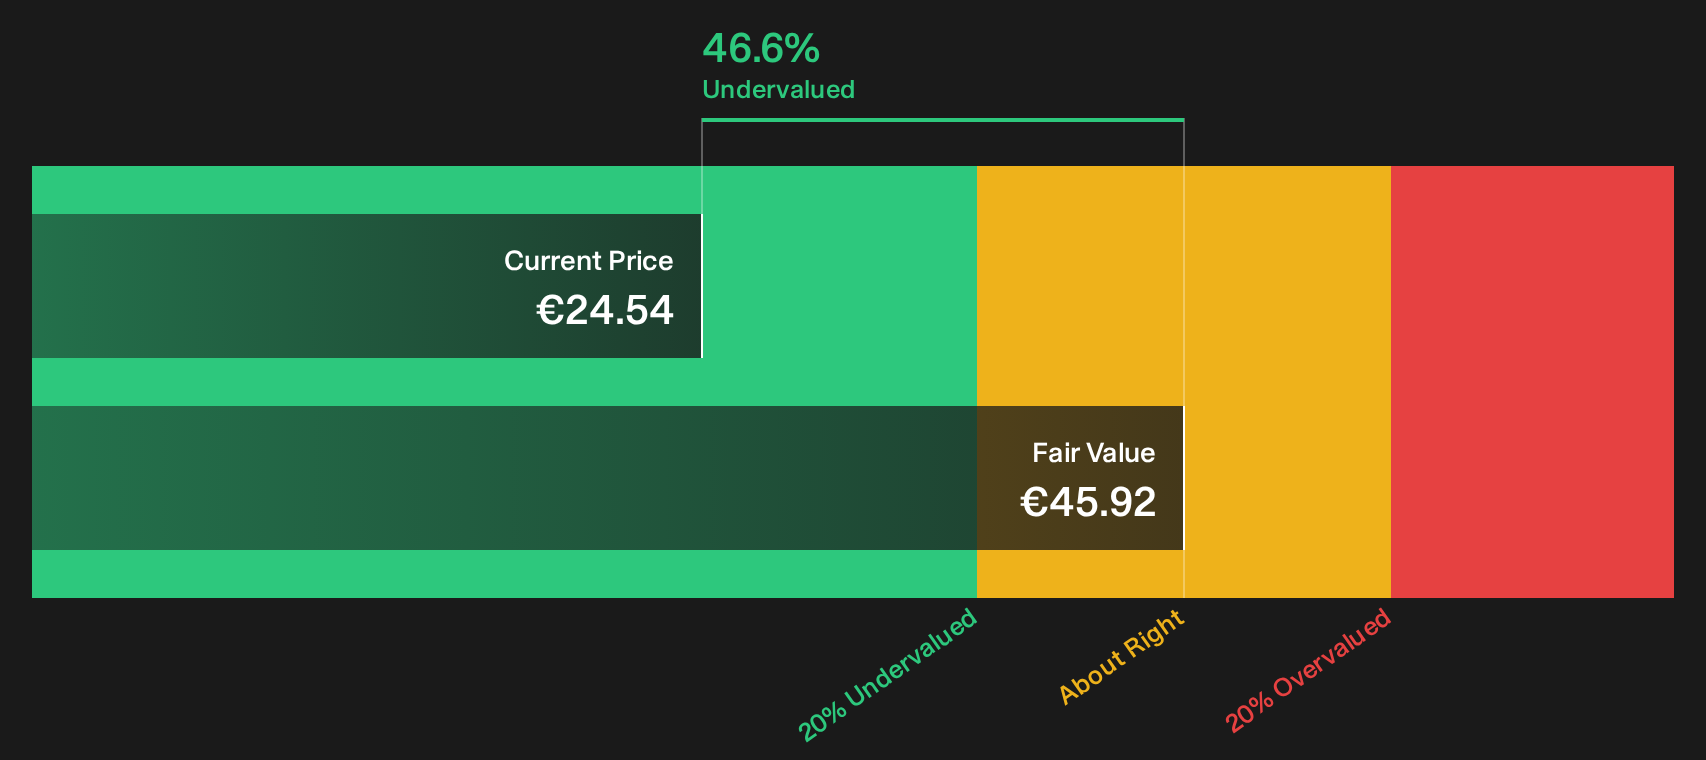
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fortum Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether Fortum Oyj's current enthusiasm is justified or stretched? Act while the data is fresh and test the bullish and bearish cases for yourself with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Fortum Oyj?
Do not stop with Fortum Oyj. Broaden your watchlist now and give yourself more options by scanning other high quality businesses through the Simply Wall Street Screener.
- Target quality at a discount by checking companies that pass rigorous valuation filters through the 173 high quality undervalued stocks.
- Build a steadier income stream by reviewing dividend payers highlighted in the 156 dividend fortresses.
- Guard your capital by focusing on financially robust businesses using the list of solid balance sheet and fundamentals (197 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com