


3 UK Industrial Stocks Retail Investors Are Watching As Steel Supply Pressures Build
The British Steel nationalisation saga is turning into a live stress test for UK industrial policy, with £1.3m a day in support and a possible £1.5b bill focusing attention on who ultimately pays. When core capacity is uncertain, suppliers, contractors and materials specialists can quietly gain ground. This article walks through 3 UK-listed industrials and construction materials stocks exposed to this disruption, and what that exposure might mean for your portfolio decisions.
The three stocks covered below are only a small sample of what this theme can touch, and the full screen surfaced 52 more UK-listed industrials and construction materials companies with equally compelling narratives that are not discussed in this article.
If you want to identify and analyze the broader opportunity set around steel-sector disruption, head straight to the UK-listed non-steel industrials and construction materials benefiting from steel-sector disruption screener.
Hill & Smith (LSE:HILS)
Overview: Hill & Smith is an infrastructure products group that supplies engineered components and galvanizing services which can substitute for traditional steel-heavy solutions across roads, utilities and wider construction projects.
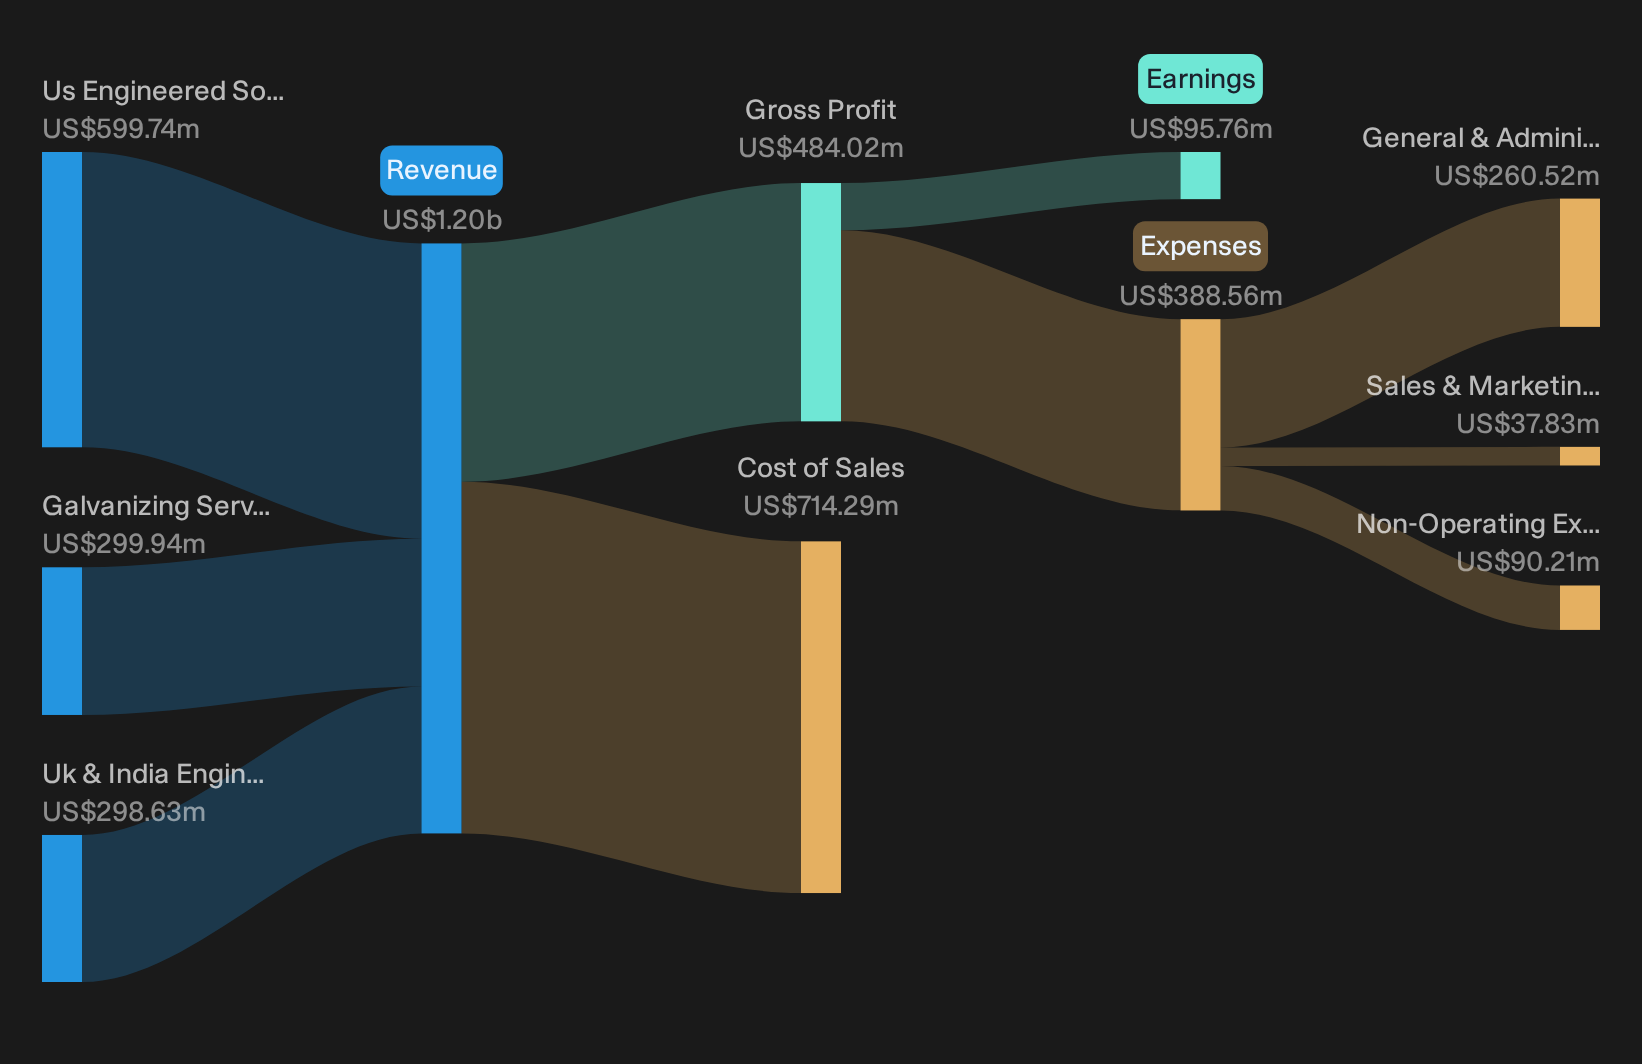
Operations: Hill & Smith generates about US$600 million from US Engineered Solutions, US$300 million from Galvanizing Services and US$300 million from UK & India Engineered Solutions, with North America around US$780 million of sales and the UK about US$340 million.
Market Cap: £2.27b
Hill & Smith matters in this steel disruption screen because its infrastructure products and galvanizing services give project owners options that do not rely solely on traditional domestic steel supply.
"Robust demand for engineered infrastructure solutions in the U.S., supported by record order books and multi-year federal and state investments in transportation and electric grid modernization, is expected to drive sustained revenue growth and margin expansion for Hill & Smith's higher-margin platform businesses."
What happens if a single underappreciated cost pressure starts to squeeze the return profile that those higher-margin platforms currently support?
That pressure point is exactly where the story can shift quickest, and the full narrative for Hill & Smith shows how Hill & Smith's pricing power, contracts and capital choices all interact.
RHI Magnesita (LSE:RHIM)
Overview: RHI Magnesita supplies refractory materials, linings and services that help steel, cement and other high temperature industrial plants operate safely and efficiently.
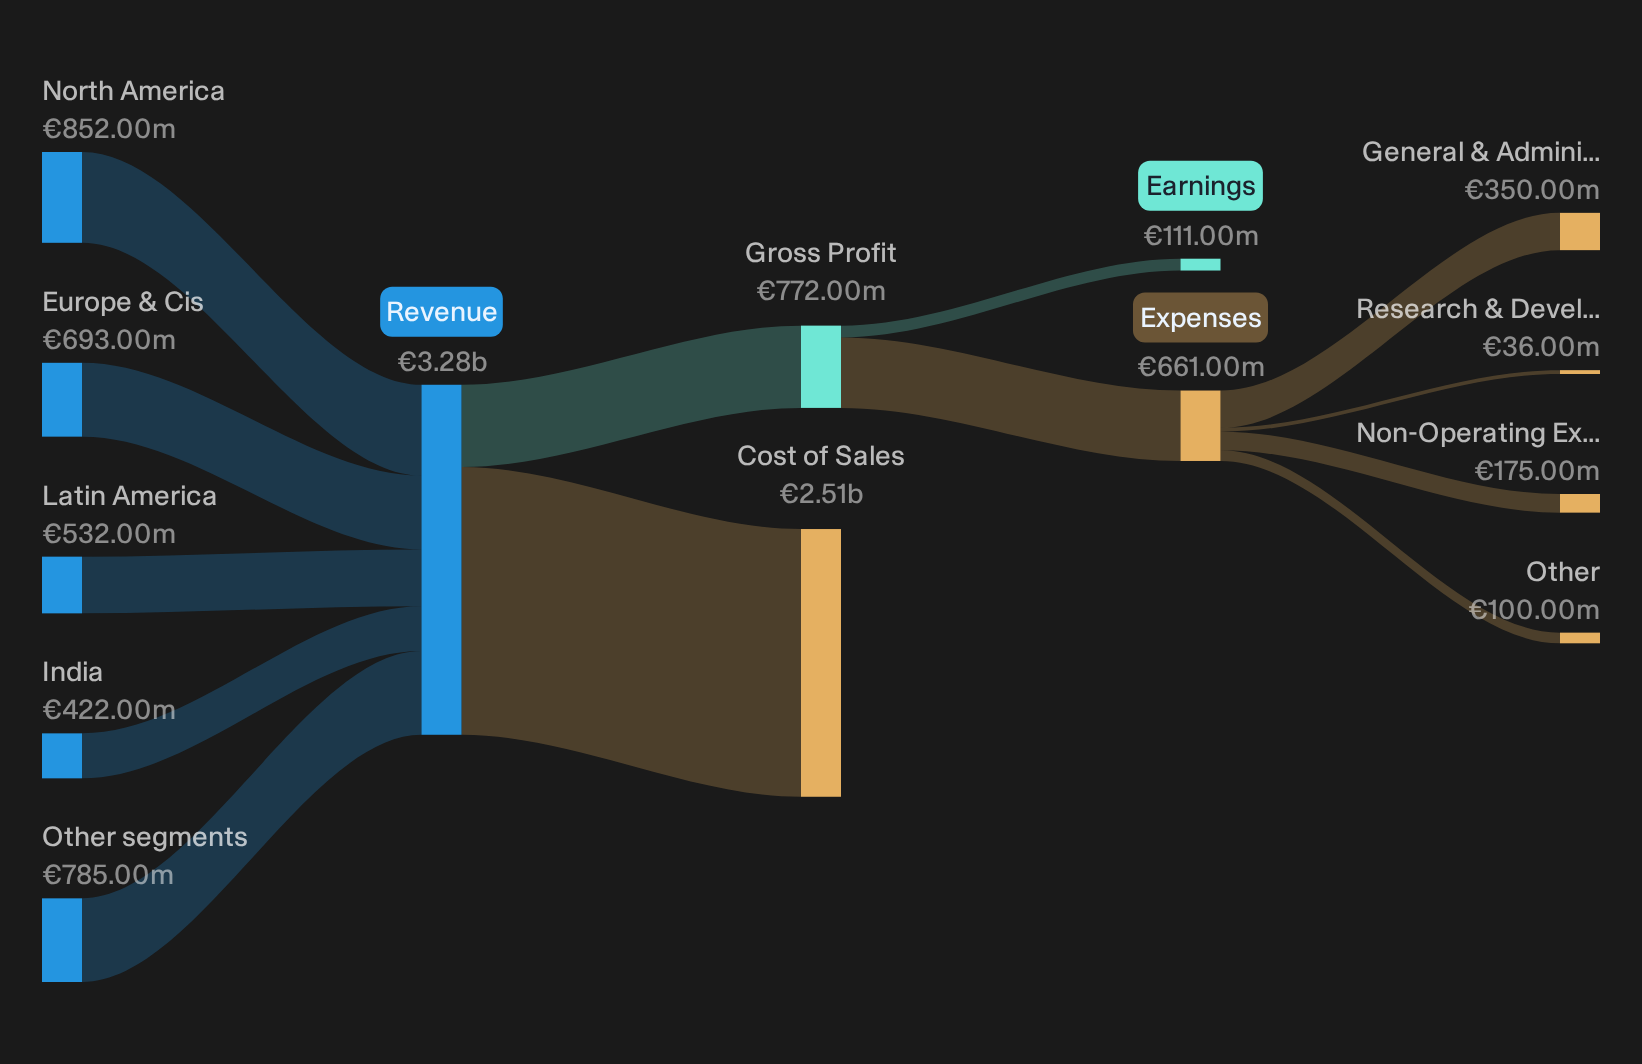
Operations: RHI Magnesita generates about €852 million from North America, €693 million from Europe & CIS, €532 million from Latin America and €422 million from India, with additional contributions from China & East Asia and the Middle East, Türkiye & Africa.
Market Cap: £1.32b
RHI Magnesita is relevant to this steel disruption theme because reliable linings and maintenance are essential whenever furnaces remain in operation, regardless of who owns the steel assets.
"The continued investment in local production capacity and recycling in the U.S. (including the Resco integration and the BPI joint venture) positions the company to benefit from regional supply chain localization and increasing trade barriers, supporting higher market share, premium pricing, and improved margins in North America."
What happens to RHI Magnesita’s earnings power if a single assumption about customer pricing tolerance in those high heat operations starts to crack?
If that pricing assumption really is the fault line, the full narrative for RHI Magnesita maps how RHI Magnesita’s furnace economics could decouple from steel volatility and where upside or strain might concentrate.
Vesuvius (LSE:VSVS)
Overview: Vesuvius provides molten metal flow engineering and refractory solutions that keep steel and foundry plants running reliably, directly linking it to steel-sector disruption.
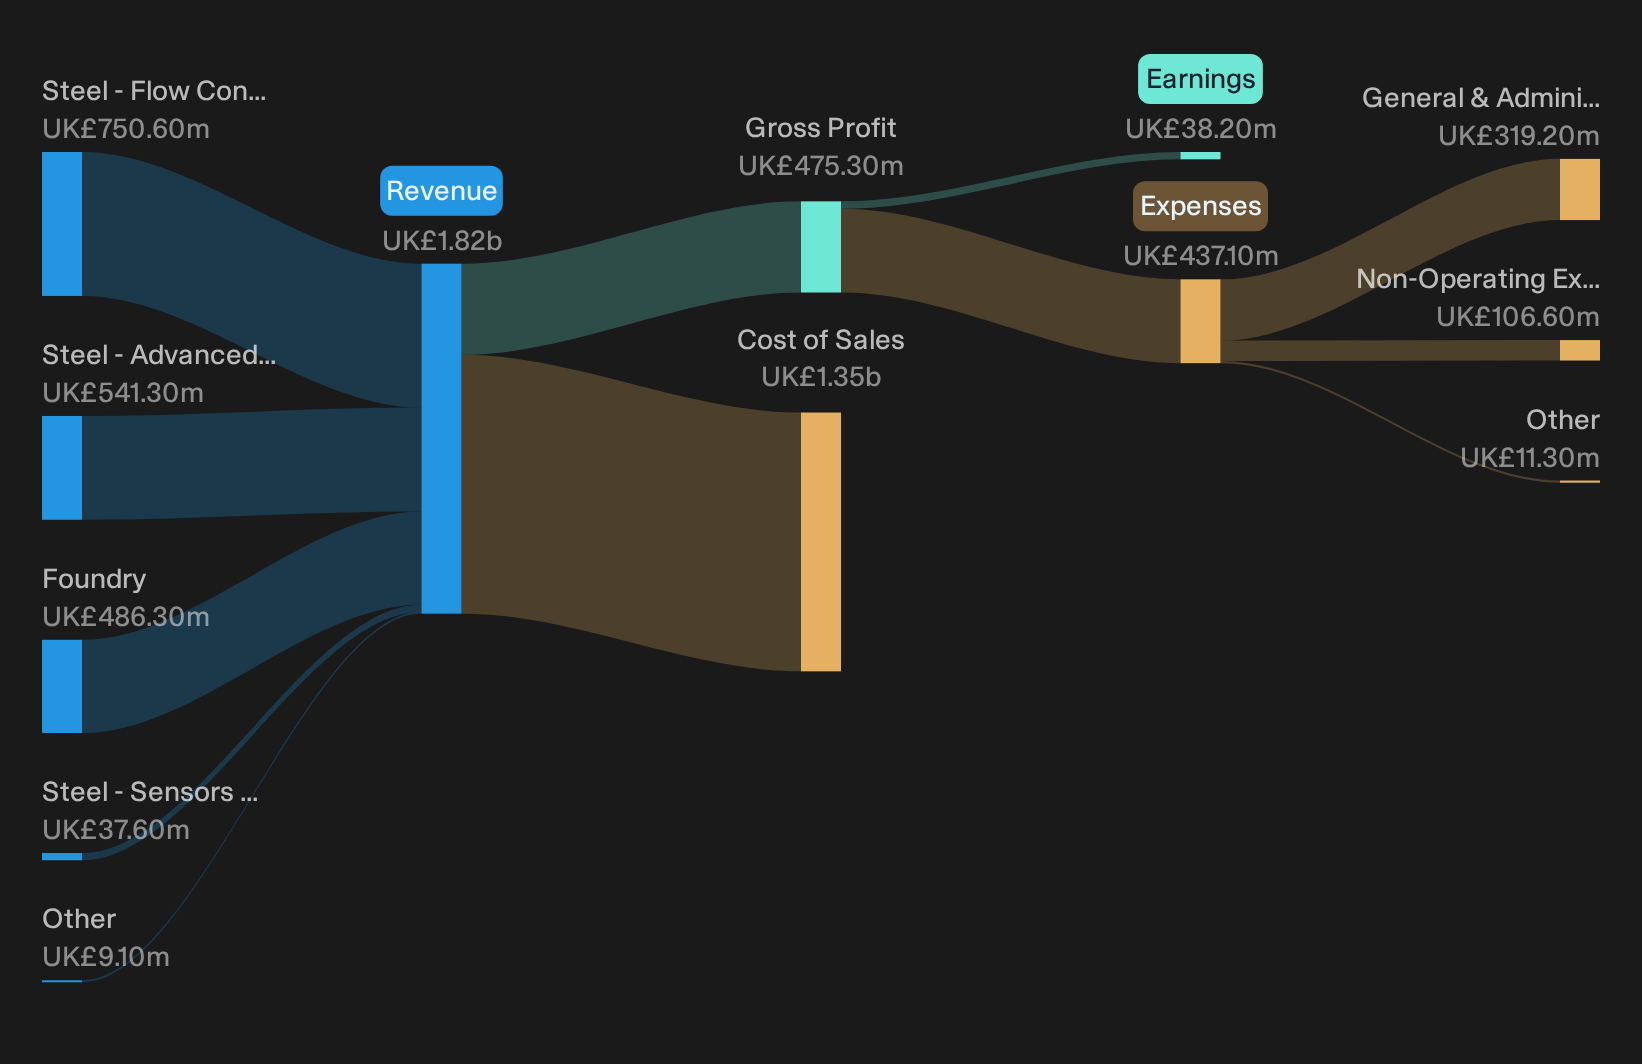
Operations: Vesuvius generates £750.6 million from Steel Flow Control, £541.3 million from Steel Advanced Refractories, £486.3 million from Foundry and £37.6 million from Steel Sensors & Probes.
Market Cap: £908 million
Vesuvius matters in this screen because when steelmakers and foundries worry about capacity, cost overruns or outages, they often turn to more reliable molten metal handling and refractory solutions rather than risk unplanned downtime.
"The expansion into higher-growth, non-ferrous foundry segments, particularly aluminum products linked to the automotive and renewable sectors, diversifies Vesuvius's revenue base and taps into long-term demand from electric vehicle manufacturing and renewables infrastructure, supporting future revenue growth and improving business resilience."
What happens to Vesuvius’s margins if a single unseen cost or pricing pressure starts to bite just as that diversification gathers pace?
When that cost pressure bites, the full narrative for Vesuvius shows where Vesuvius could be accelerating, masking risk, or quietly reshaping its steel exposure.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Slow money gets caught chasing breakouts after momentum is already flying. Scan under the radar for now, while it matters, and get in early.
- Spot income workhorses with yields that might hold up when others are dropping by scanning the 1 dividend fortresses built to filter for resilience and cash strength.
- Track fast-moving automation and factory winners before they leave the pack by using the curated 95 robotics and automation stocks focused on real businesses, not hype.
- Position ahead of infrastructure upgrades by reviewing the hand-picked 37 power grid technology and infrastructure stocks that zeroes in on grid hardware, software and maintenance specialists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com