


3 British Penny Stocks To Own In September 2026
The UK government’s new corporate governance reforms put transparency, stronger shareholder rights and tighter board oversight in the spotlight. That is a direct tailwind for smaller British companies that already keep balance sheets clean, avoid heavy dilution and have insiders heavily invested alongside you. This article highlights three such low‑priced UK stocks that have risen over the past year and sit on analyst growth forecasts that many investors are still ignoring.
These three examples are just a starting sample, and the full screen surfaced 9 more low priced UK companies with clean balance sheets, insider alignment and growth forecasts that are not covered below but share similarly tight governance stories.
To identify those additional opportunities, head straight into the Elite Penny Stocks screener to filter, analyze, and focus on the highest conviction penny stock ideas that fit your criteria.
Franchise Brands (AIM:FRAN)
Franchise Brands is a £300.8 million franchising group whose strongest link to the Elite Penny Stocks theme is Filta International, a recurring B2B cooking oil filtration and fryer management service with franchise roll out potential. The group remains diversified, with £64 million from Pirtek, £44.6 million from Water & Waste Services and £36.5 million from Filta, alongside smaller B2C and Azura units.
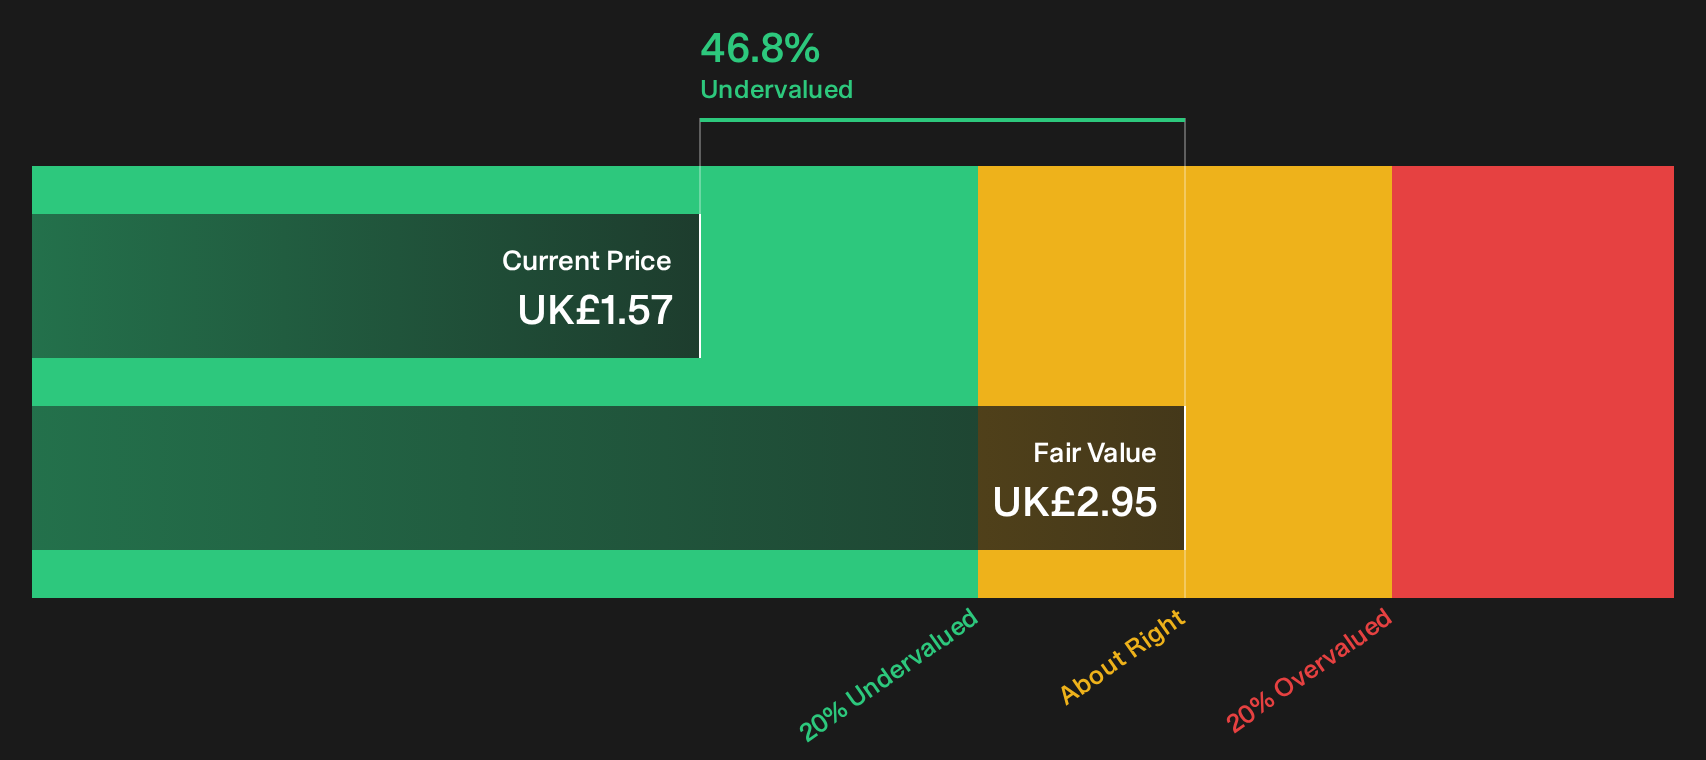
Franchise Brands has the kind of profile this screener is built for. Earnings rose 39.1% last year and are forecast to keep growing, while the share price trades about 46.8% below one fair value estimate despite a richer P/E. For you as an investor, the real question is how much operating leverage can flow through margins if one unseen pressure breaks in its favor.
If you want to see how that potential operating leverage is modeled in detail, go straight to the DCF valuation analysis for Franchise Brands to see what the current pricing might be missing.
Afentra (AIM:AET)
Afentra is a £207.2 million upstream oil and gas group focused on African assets, with its 45% interest in producing Block 3/05 and 40% operated stake in exploration Block 3/24 in offshore Angola anchoring the Elite Penny Stocks theme through production cash flow and asset backed growth potential.
Afentra plugs directly into the Elite Penny Stocks theme because its Angolan upstream assets back the share price with producing barrels and near term growth potential, even as the group remains loss making and has used equity funding. Investors who care about solid assets, upside forecasts and insider aligned governance will likely watch what happens when those Angolan fields move from current operations into sustained production.
When those Angolan fields start to show their true earning power, the analysis report for Afentra can help you see how Afentra’s risk and reward profile could be shifting.

Diaceutics (AIM:DXRX)
Diaceutics runs DXRX, a precision medicine diagnostics commercialization platform that uses tools like DXRX Signal and Physician or Lab Mapping to help drug makers find eligible patients in real time. The business generated £38.4 million from Medical Labs & Research and has a market value of about £140.1 million.
Diaceutics ties into the Elite Penny Stocks theme through its DXRX platform, with forecast earnings growth of about 87% a year, recent profitability, and shares trading roughly 39% below one fair value estimate. The real test is how far margins can move if a quiet shift in biomarker testing demand plays in its favor.
If that shift in biomarker testing demand accelerates, the analyst forecasts for Diaceutics explain how Diaceutics forecasts and valuation expectations could be decoupling from current pricing.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not wait. Breakout moves, early momentum and quiet winners can be identified quickly once attention hits. Scan these under the radar ideas before the crowd and consider acting while they remain less widely followed.
- Track income streams that could stay resilient while others wobble by scanning a curated pool of 1 dividend fortresses built for investors who care about consistency as well as yield.
- Look for fast growing automation suppliers before headlines catch up by running your filters across 95 robotics and automation stocks selected for real-world exposure to robots and industrial efficiency.
- Explore the next infrastructure build-out cycle by screening 37 power grid technology and infrastructure stocks that connect directly to grid upgrades, transmission demand and long term electrification themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com