


Marvell Technology (MRVL) Expands AI Chip Capacity, Is The Upside Already Priced In?
Marvell Technology (MRVL) is back in the spotlight after expanding its multi year agreement with GlobalFoundries to boost silicon germanium chip capacity for high speed optical links inside AI focused data centers.
For context, Marvell Technology’s share price has climbed 6.1% over the past week and 11.5% over the past month, even after a 90 day share price return that is down 22.5%, while total shareholder return over five years sits at about 2.9x. Recent catalysts include the expanded GlobalFoundries capacity deal for SiGe chips used in AI data centers, the Azure Payment HSM v2 launch with Microsoft and Utimaco, and a run of AI focused conference appearances. These developments have kept investors focused on both growth potential and execution risk as the stock trades around US$240.76.
Scan how other AI infrastructure plays are reacting to the same trends shaping Marvell Technology by running the hand picked 89 AI infrastructure stocks alongside MRVL on your watchlist.
After a sharp year to date run and a recent pullback, Marvell Technology now trades close to US$240, while fair value estimates cluster nearer US$140 to the low US$290s. Where does that wide gap really resolve?
Most Popular Narrative: 72% Overvalued
According to the most followed Marvell Technology narrative, the share price of $240.76 sits far above an implied fair value of $140. That gap reflects a belief that the market is already baking in a very optimistic AI infrastructure ramp and leaving little room for disappointment.
Marvell has built something genuinely rare in semiconductors, a full-stack platform that coverscustom chip design, high-speed optical interconnect, silicon photonics, and memory switching, all converging on the single biggest infrastructure build-out of the current decade.
NVIDIA''s $2B investment is not a customer relationship. It is a vote of confidence from theworld''s most informed AI infrastructure buyer that Marvell''s technology platform is the rightfoundation for the next generation of AI factories. Google''s parallel conversations reinforcethe same conclusion from a different ecosystem vector.
See why 65 investors see Marvell Technology as 72% overvalued.
Result: Fair Value of $140 (OVERVALUED)
Still, two pressure points could flip this Marvell Technology story fast if they go wrong: Amazon Trainium share loss and any sharp pullback in hyperscaler AI capex.
Find out about the key risks to this Marvell Technology narrative.
Another View: Marvell Technology Through The DCF Lens
The popular community narrative pins Marvell Technology at a fair value of about $140, well below the current share price near $240.76. Our DCF model presents a different perspective. On that framework, the stock trades roughly 14% below an estimated future cash flow value of $281.35, which suggests undervaluation instead of excess optimism. Which story do you trust more: the crowd or the cash flows?
For investors who want to see how that cash flow view is built from the ground up, including the moving pieces behind the fair value range, Look into how the SWS DCF model arrives at its fair value..
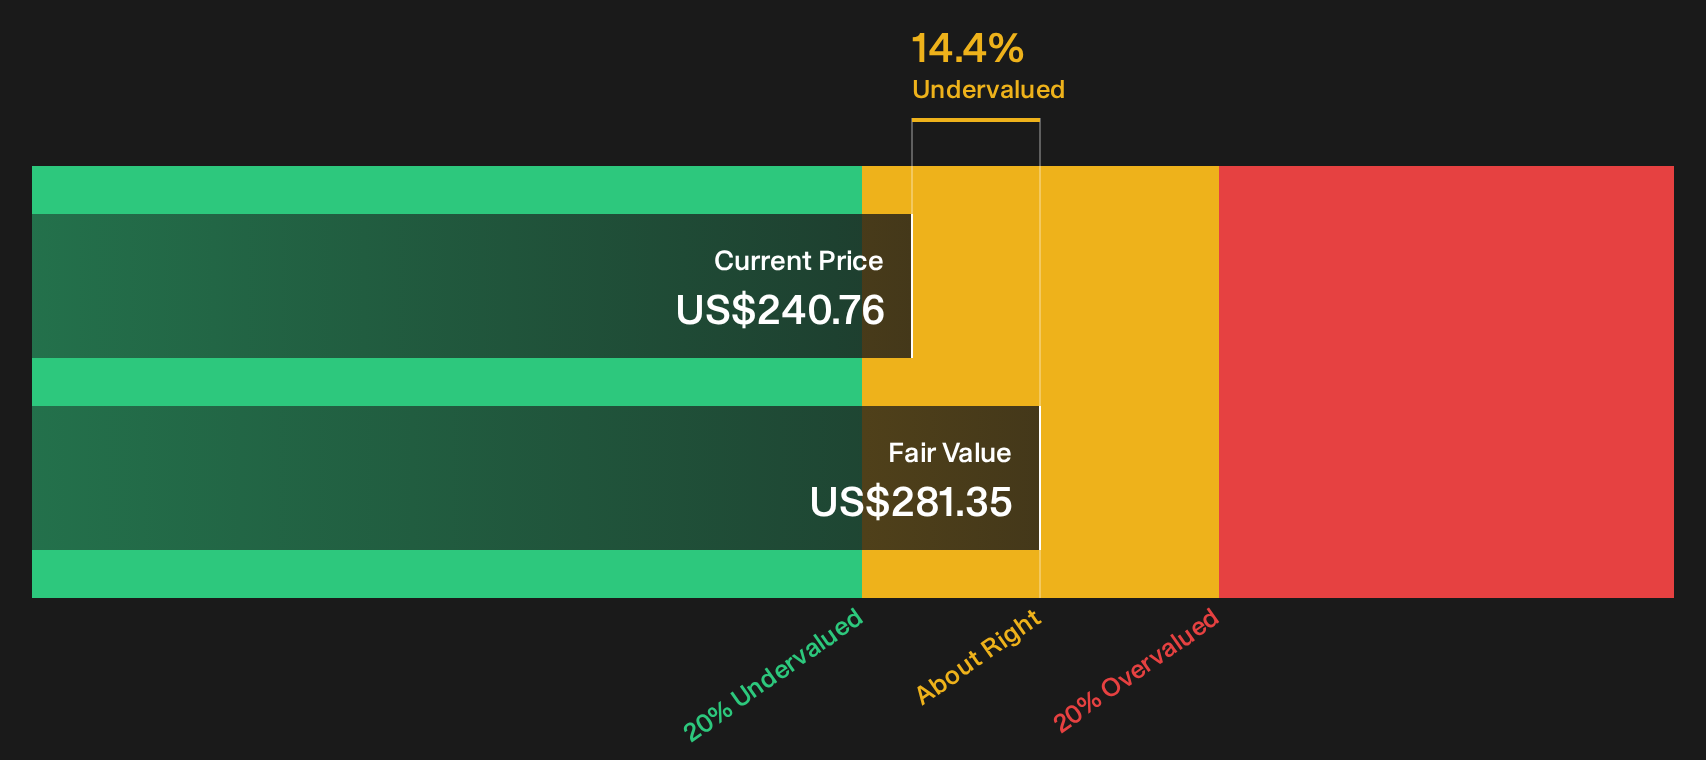
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marvell Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Marvell Technology can be hard to read, so consider acting promptly, reviewing the data yourself, and weighing both the upside and the risk flagged in the 3 key rewards and 2 important warning signs.
Looking for more Marvell Technology sized ideas?
If you only focus on Marvell Technology, you could miss opportunities where the risk reward trade off looks even cleaner across quality, value, and income.
- Hunt for potential mispriced opportunities by checking companies in the 29 high quality undervalued stocks that combine appealing prices with solid underlying metrics.
- Strengthen the foundation of your portfolio by reviewing the list of solid balance sheet and fundamentals (23 results) that highlight businesses with sturdier financial footing.
- Put your cash to work with income candidates by scanning the 6 dividend fortresses offering higher yields that may complement a growth focused position like MRVL.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com