


Pegasystems (PEGA) Stock Looks Undervalued On Future Cash Flow
Pegasystems has had a mixed share price journey, with the stock up 70.7% over the past three years but still carrying some sharp drawdowns more recently. That swing in sentiment puts the focus squarely on one question for investors today: whether the current US$36.07 price is supported by the cash the business is expected to generate.
- The 70.7% gain over three years means anyone holding Pegasystems for that period has already seen substantial value creation at the share price level, which raises the stakes for whether underlying cash flows can keep backing that move.
- The company’s model depends heavily on turning software sales and services into reliable recurring cash generation, so the durability and timing of those inflows may support or undermine the case for today’s valuation.
- If you'd rather focus on earnings, this one's for you. See what Pegasystems's 18.3x P/E says about the price.
For investors, the debate is whether Pegasystems' current share price can be justified by its projected cash flows when assessed against an intrinsic value estimate based on a Discounted Cash Flow model.
If you want to pressure test Pegasystems against other opportunities where valuation meets fundamentals, compare it with 29 high quality undervalued stocks
Does Pegasystems Look Undervalued on Cash Flow?
The Discounted Cash Flow model looks at the cash Pegasystems is expected to generate for shareholders and discounts it back to today. Over the latest twelve months the business produced about $500.5m of free cash flow, and the projections used in the model assume this pool of cash keeps growing rather than shrinking.
Those estimates reach into the early 2030s and point to steadily higher annual free cash flow in $. On that basis, the DCF output suggests Pegasystems' intrinsic value sits substantially above the current share price of $36.07, which implies the market price does not fully reflect the cash the company is modeled to produce. Find out what Pegasystems could be worth using our Discounted Cash Flow (DCF) estimate.
The Pegasystems Narrative: What Would Justify Today's Price?
Narratives pick up where the Pegasystems valuation puzzle leaves off and explain which paths for revenue growth, profitability and earnings would need to occur for the stock to be worth significantly more or materially less than today’s price. Each narrative connects its figures to a clear view of how Pegasystems' growth profile, margin trajectory and risk picture might change, giving you specific reference points to revisit as new information becomes available.
Views on Pegasystems now split between investors who see AI tools and cloud migrations setting up a rebound and those who think execution issues and competitive pressure keep risk skewed the other way.
Bull case: 16% undervalued
"Strong ACV growth, reflecting client shifts to Pega Cloud services, could lead to increased recurring revenue streams and greater financial stability…"
Discover why this Narrative puts Pegasystems at 16% undervalued.
Bear case: 44% overvalued
"The rapid proliferation of low-code and no-code automation platforms threatens to erode Pegasystems' legacy differentiation, allowing new competitors to undercut on price and ease of use…"
Explore why this Narrative puts Pegasystems at 44% overvalued.
One more Pegasystems check that sits outside the cash flow story
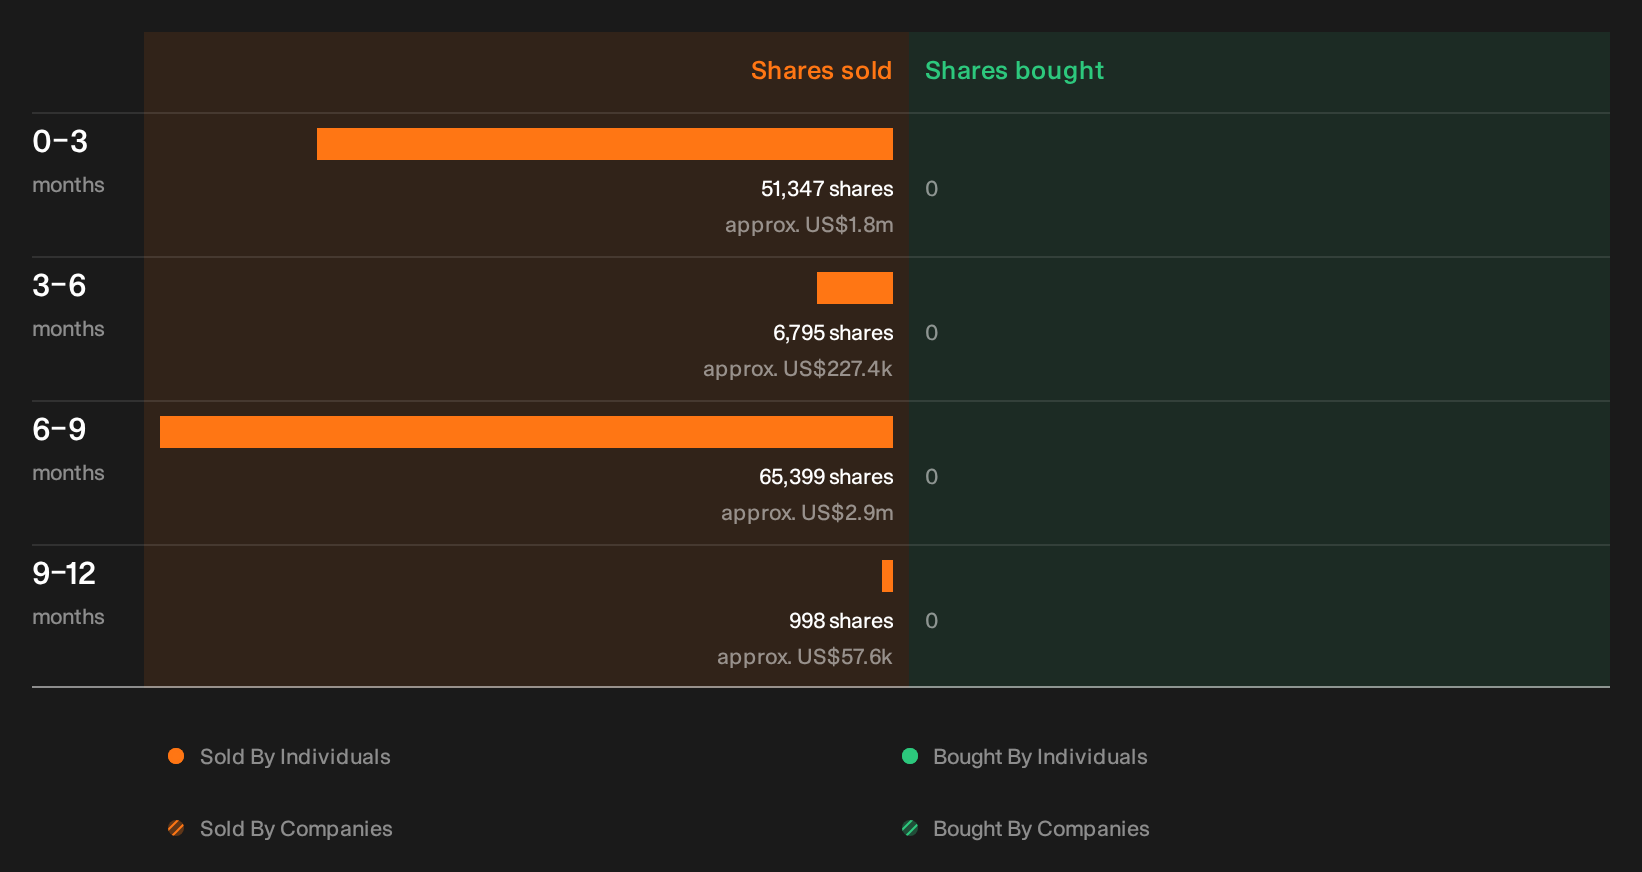
Price and cash projections tell only part of the Pegasystems story, because recent trades by company insiders have also been flagged and the specific sellers, volumes and possible readthroughs still need your closer look. See the recent insider selling flagged for Pegasystems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com