


Mitsui Kinzoku Company And 2 Japanese Quality Stocks
Japan just lifted interest rates to a 31 year high, and higher borrowing costs can hit weaker balance sheets hardest. If you want exposure to Japanese stocks without taking on fragile finances, this is a moment to focus on companies with strong cash positions and modest debt. This article breaks down three relatively low risk Japanese leaders that score well in our quality screens and may appeal to cautious investors.
The three stocks profiled below are just a sample, as the full Low Risk Leaders screen currently flags 18 more Japanese companies with similar balance sheet strength and cautious risk profiles that are not covered in this article. To see the complete picture, identify your own favourites, and analyze them side by side, head straight into the Low Risk Leaders screener.
Mitsui Kinzoku Company (TSE:5706)
Overview: Mitsui Kinzoku Company produces high grade copper foil, capacitor materials, metals and auto parts, supplying foundational components for electronics and EV batteries.
Operations: Mitsui Kinzoku Company generates about ¥401b from Metals and ¥358b from Functional Materials, with smaller contributions from other activities and adjustments.
Market Cap: ¥1.3t
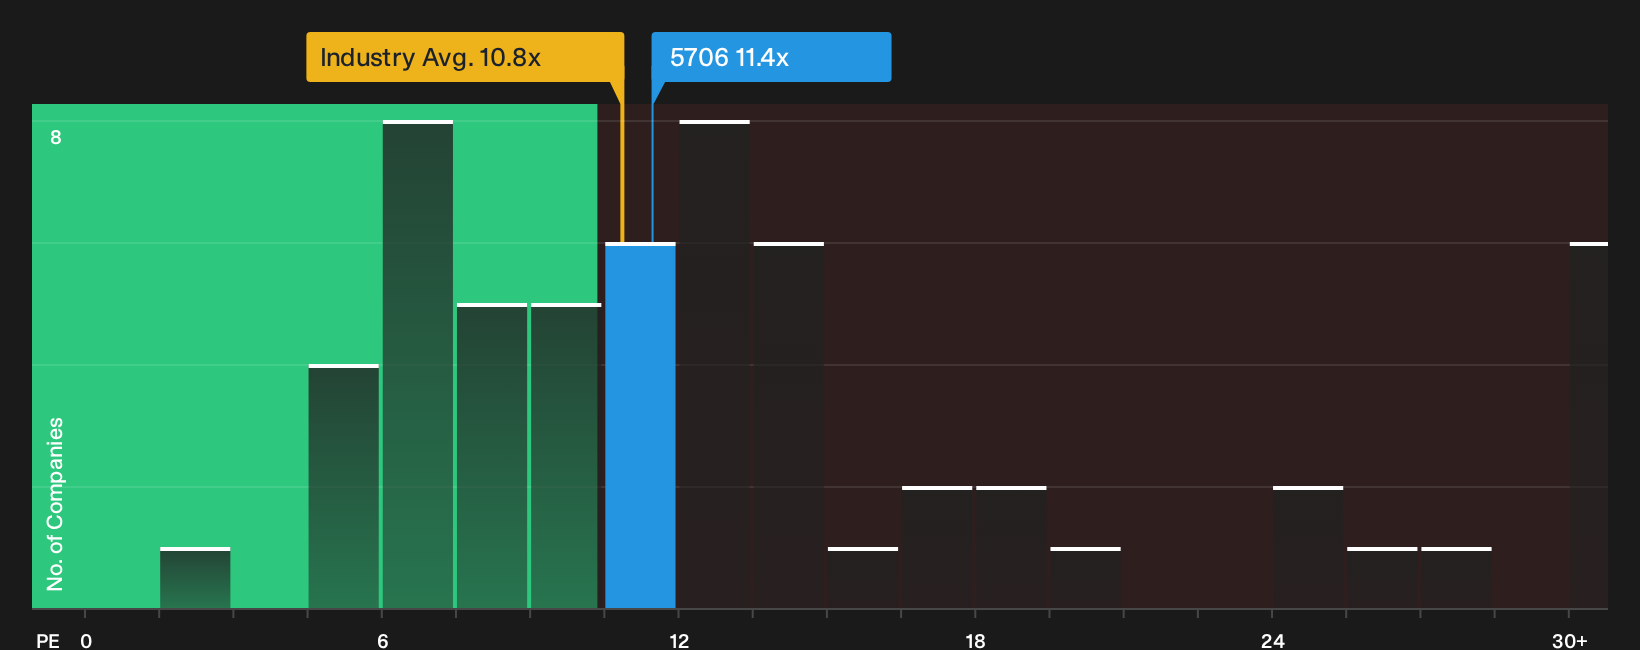
Mitsui Kinzoku Company combines an 11.4x P/E with a 27% ROE and 14.4% net margin, which aligns with a Low Risk Leaders screen focused on sturdy balance sheets and earnings quality. Copper foil and capacitor materials connect that financial profile to electronics and EV demand, although one unseen funding pressure still needs to remain contained for margins to stay comfortable.
That funding overhang is exactly why the 3 key rewards and 1 important major warning sign could be useful if you want to see what might tighten or release the pressure next.
Kioxia Holdings (TSE:285A)
Overview: Kioxia Holdings develops and sells NAND flash memory and SSD products that power data storage for cloud, enterprise, and consumer devices.
Operations: Kioxia generates approximately ¥3.8t from its Memory Business segment, covering NAND flash, SSDs, and related storage products and services.
Market Cap: ¥29.9t
Kioxia Holdings fits the Low Risk Leaders theme through its focus on NAND memory and SSDs that support long term demand from cloud and enterprise storage. This positioning is backed by very large recent earnings and profit figures that point to a robust financial base. For cautious investors who still want exposure to data growth, a key consideration is how consistently memory pricing discipline can hold.
That pricing discipline question is exactly where the 3 key rewards and 1 important major warning sign can help you see what might accelerate, or abruptly stall, the momentum of Kioxia Holdings.

Recruit Holdings (TSE:6098)
Overview: Recruit Holdings runs global online hiring platforms plus staffing and marketing services that link employers, job seekers, and everyday consumers.
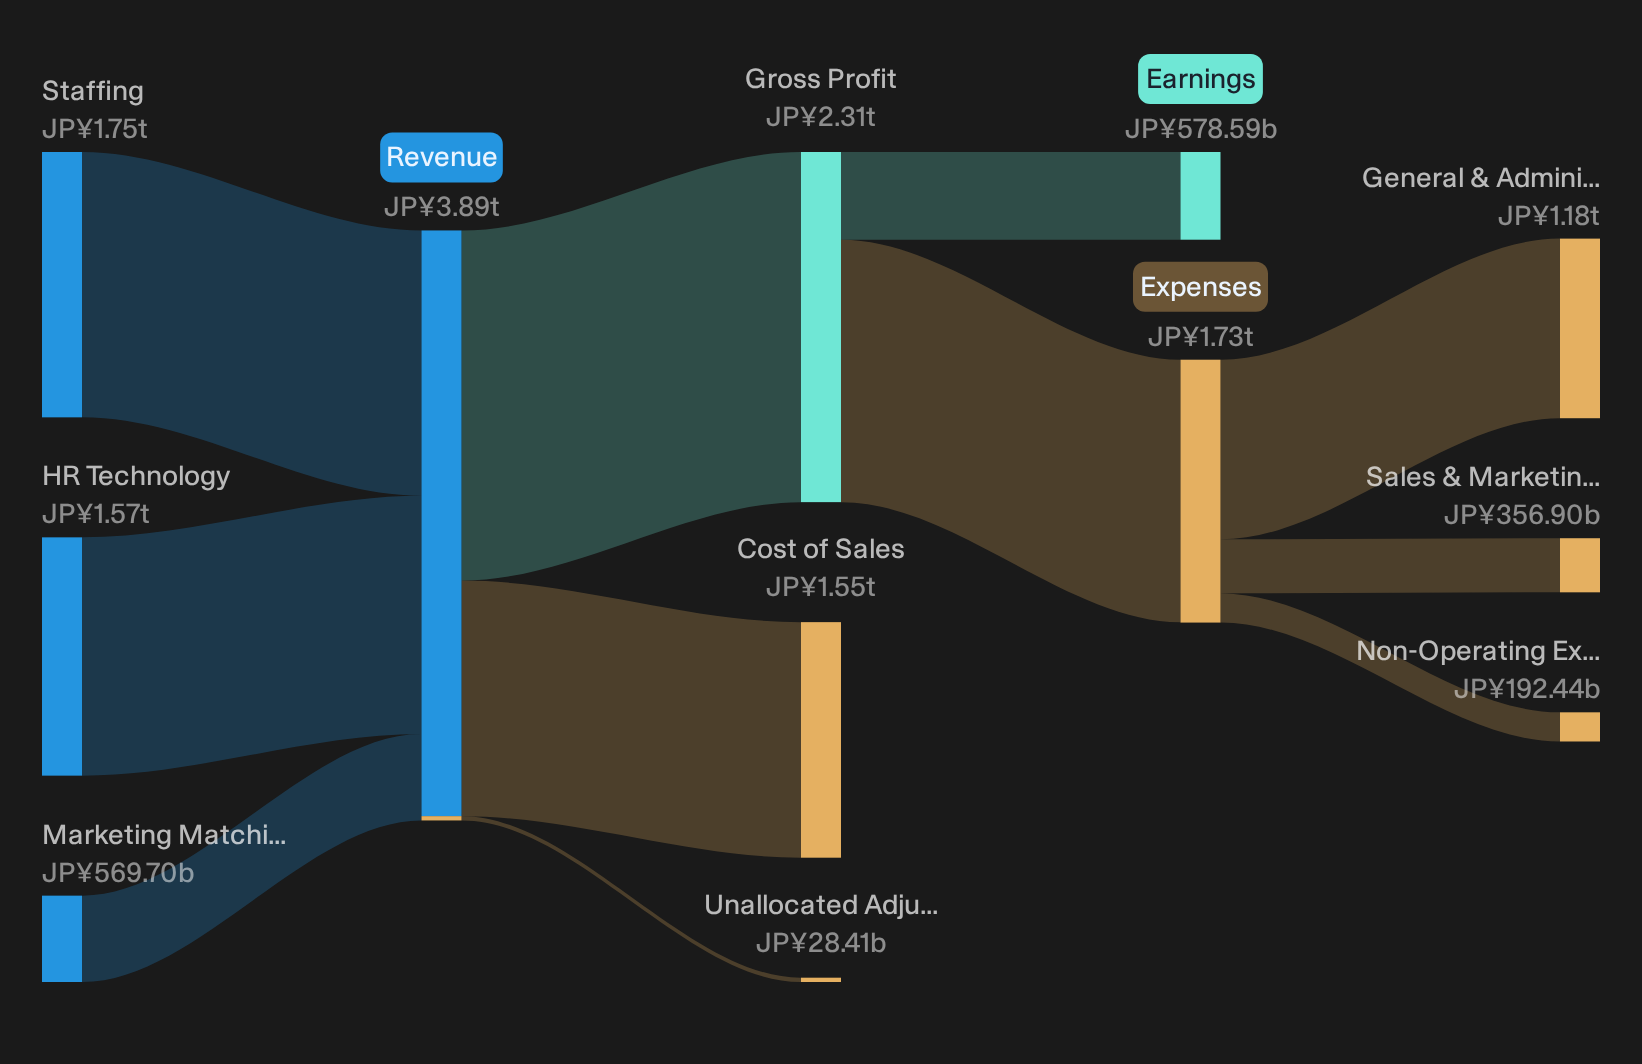
Operations: Recruit Holdings generates about ¥1.75t from Staffing, ¥1.57t from HR Technology, and ¥570b from Marketing Matching Technologies.
Market Cap: ¥24.2t
For a Low Risk Leaders screen built around sturdy foundations, Recruit Holdings offers something different. HR Technology platforms such as Indeed give the group a recurring, data rich cash engine that can underpin a more diversified staffing and marketing services portfolio.
"Recruit Holdings' unique access to large volumes of proprietary matching and conversational data, combined with advanced vertical AI development for specialized HR processes, positions the company to create best-in-class, defensible user experiences that will attract and lock in both employers and job seekers globally, supporting multi-year engagement growth and significant revenue upside."
What happens to that foundation level appeal depends heavily on how one unresolved pressure on profitability plays out over the next few years.
If that profitability pressure is what you keep circling back to, read the full narrative for Recruit Holdings to see how Recruit Holdings could turn it into accelerating engagement and earnings power.
Seeking Fresh Alternatives Before They Fly
New ideas tend to be recognized first. By the time every screen lights up, the easy edge can be gone. Scan curated lists while they are still under the radar and consider acting while they remain less widely followed.
- Explore resilient momentum opportunities before they become crowded by scanning a curated group of resilient stocks with low risk scores through the 21 resilient stocks with low risk scores.
- Identify potential breakout yield candidates early by tracking a hand picked pool of high payout candidates in the 14 dividend fortresses.
- Review developments in the AI build out by examining a focused lineup of picks in the 89 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com