


Agnico Eagle Mines (AEM) Climbed, But What Is Drawing Fresh Attention?
Recent move in Agnico Eagle Mines stock
Agnico Eagle Mines (AEM) gained 2.97% in its latest session, outpacing the S&P 500, after projections pointed to a 13.43% year over year rise in next quarter EPS.
The recent 1-month share price return of 7.72% and 90-day share price return of 20.83% indicate momentum in Agnico Eagle Mines, with the 1-year total shareholder return of 31.59% and very large 3- and 5-year total shareholder returns highlighting a longer period of strong compounding.
Look beyond Agnico Eagle Mines and explore other gold producers that may be approaching potential breakouts with our curated list of 36 elite gold producer stocks.
Agnico Eagle Mines now carries a strong recent track record and a fresh price pop. Is most of the easy upside gone, or do the current valuation markers still argue for more room to run?
Most Popular Narrative: 100% Undervalued
Agnico Eagle Mines last closed at $201.37, while the most followed narrative on the stock pegs fair value at $123,914 per share. This large difference frames the whole debate around whether the current rally is only a small slice of the story.
With gold hovering near record highs, a massive structural shift is quietly playing out in the Abitibi greenstone belt that the broader market has completely failed to price in.
If you are holding Agnico Eagle ($AEM) or hunting for the ultimate asymmetric micro-cap play, you need to look at the cold engineering reality currently facing the Canadian Malartic complex, and the tiny junior right next door that holds the key to fixing it: Renforth Resources (CSE: RFR | OTCQB: RFHRF).
See why 27 investors see Agnico Eagle Mines as 100% undervalued.
According to lenny67, who authored the widely followed narrative, the opportunity in Agnico Eagle Mines hinges less on short term share price moves and more on how the Canadian Malartic complex is managed over the coming years, including how mill capacity and nearby deposits are handled.
The same narrative applies a discount rate of 8.30% to value Agnico Eagle Mines. This rate is used to bring projected future cash flows and outcomes back into today's dollars. It is central to arriving at the fair value estimate of $123,914, and helps explain why the model highlights a very large undervaluation compared with the current market price.
For investors, the key takeaway is that this community driven framework is tying Agnico Eagle Mines’ worth to long term assets and potential regional catalysts, rather than to the recent 1 year or 5 year share price performance alone.
Result: Fair Value of $123,914 (UNDERVALUED)
Still, the thesis leans heavily on one user’s aggressive fair value model and on future decisions around the Canadian Malartic complex that Agnico Eagle Mines has not confirmed.
Find out about the key risks to this Agnico Eagle Mines narrative.
Another View: What Other Valuation Models Say About Agnico Eagle Mines
The community narrative puts Agnico Eagle Mines at a fair value of $123,914 per share, which is far above the current $201.37 share price. A more traditional model tells a very different story. The SWS DCF model estimates the value of future cash flows at $149.37 per share, so at today’s price the stock screens as overvalued by that yardstick.
This gap matters because it shows how sensitive outcomes are to the cash flow and discount rate assumptions you choose. One framework argues the market is missing a very large opportunity. Another flags limited upside on current numbers. Which version of “fair” do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
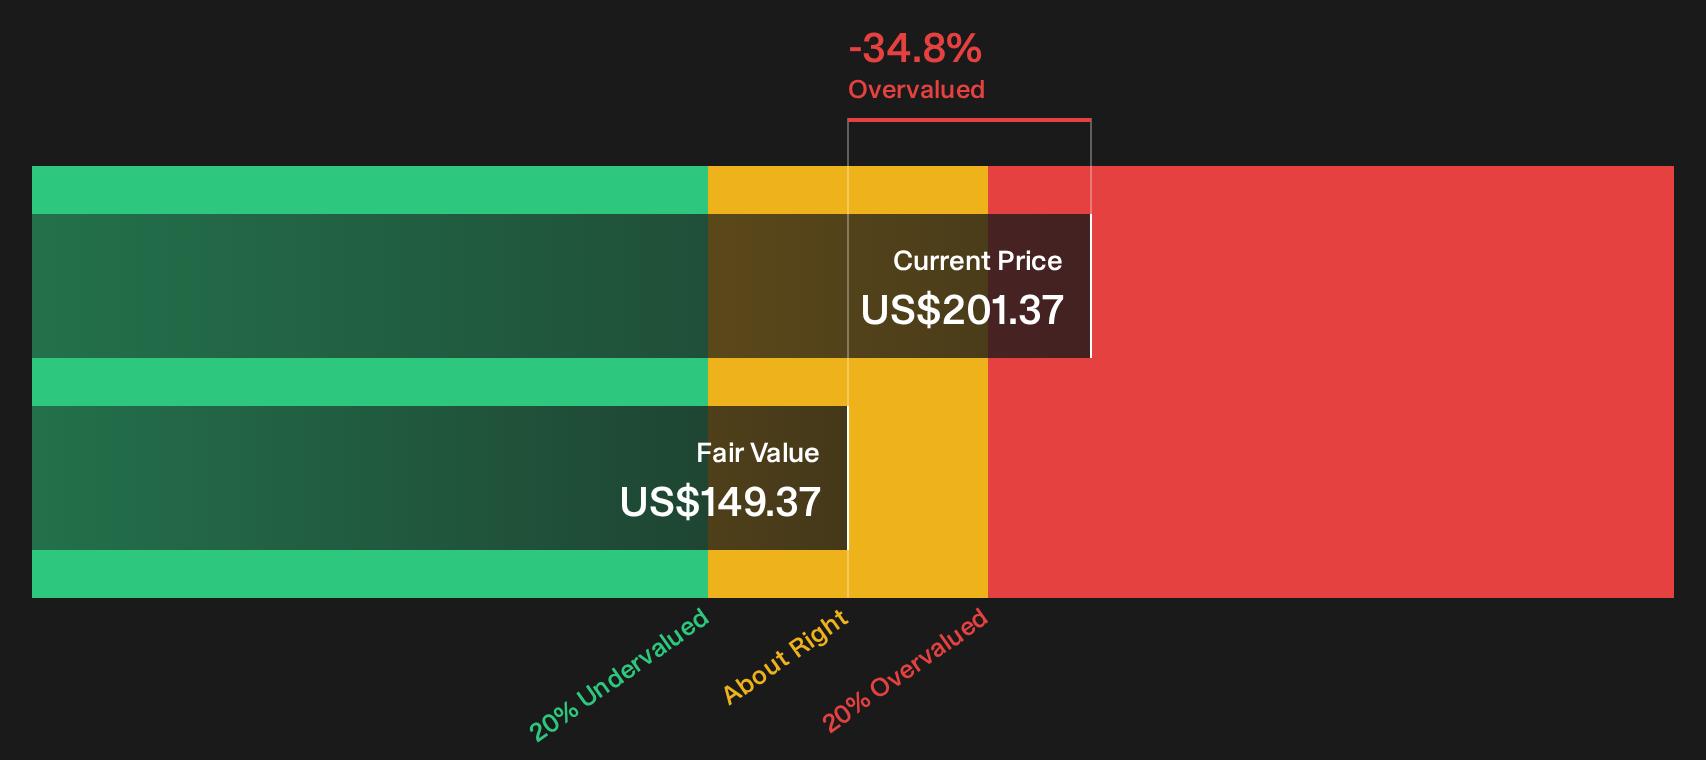
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Agnico Eagle Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Agnico Eagle Mines can cut both ways, so move quickly, pull up the data, and weigh the 3 key rewards and 1 important warning sign against your own expectations.
Looking for more investment ideas beyond Agnico Eagle Mines?
If Agnico Eagle Mines has sharpened your focus on opportunity and risk, do not stop here. Broader idea hunting can reshape your portfolio’s balance and potential.
- Target higher potential upside by scanning 16 high quality undiscovered gems that pair strong fundamentals with limited mainstream attention.
- Build a steadier foundation by reviewing a list of solid balance sheet and fundamentals (23 results) that can support resilient performance across different market conditions.
- Dial down volatility by sourcing 30 resilient stocks with low risk scores that score well on financial strength and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com