


Does Third Point Stake Change The Bull Case For TTM Technologies Stock (TTMI)?
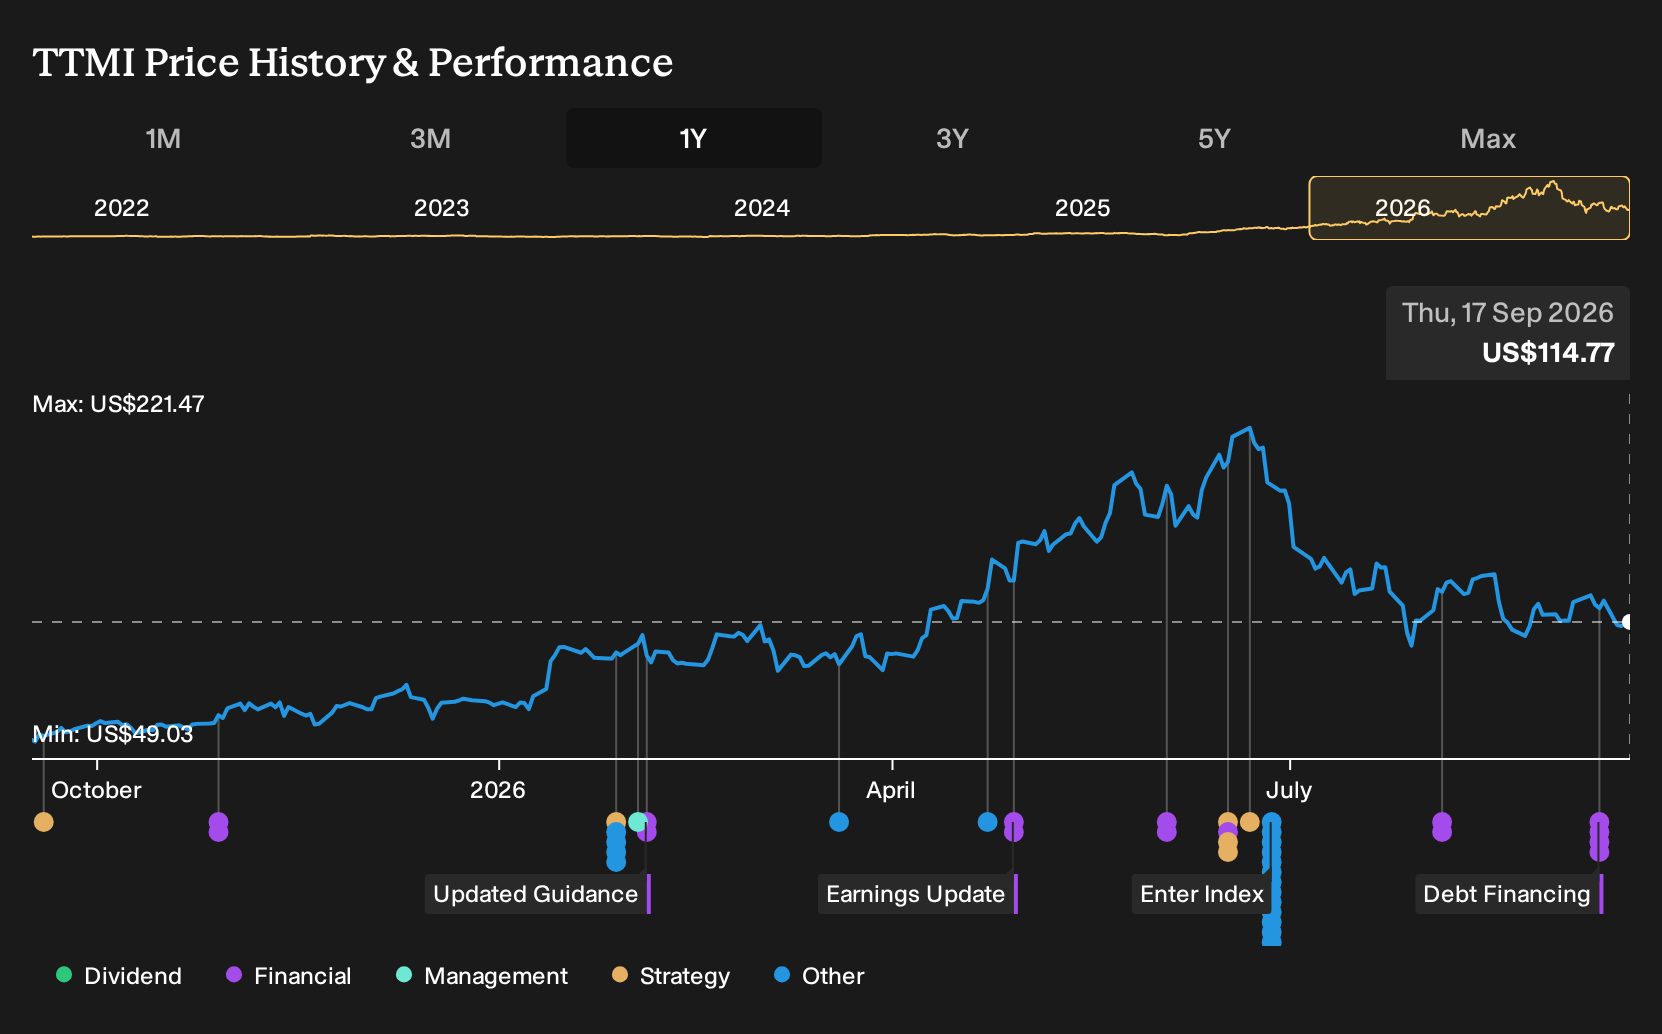
- TTM Technologies has completed a private offering of US$500 million in 6.750% senior unsecured notes due 2034, alongside plans for additional term loan financing. Together, these funding sources are intended to support the proposed acquisitions of Epiq Solutions and Swiss Technology Group and cover related corporate uses.
- Activist investor Dan Loeb's Third Point has taken a stake in TTM Technologies, which raises questions about potential shifts in capital allocation, acquisition priorities, and the pace of the company's higher cost capacity buildout.
- The next step is to assess how TTM Technologies' investment narrative could be shaped by Third Point's new activist stake in the business.
Scan the activist-backed electronics space for other potential breakouts by reviewing our hand picked list of 89 AI infrastructure stocks as AI and data center demand reshapes interconnect suppliers.
TTM Technologies Investment Narrative Recap
For TTM Technologies, you need to believe the heavy spend on advanced PCB and RF capacity in places like Wisconsin, Penang, and Syracuse will translate into durable demand from AI data centers and aerospace and defense programs. The near term swing factor is execution on these ramps, especially lifting margins while absorbing higher domestic operating costs.
The biggest immediate risk remains underutilized high cost plants and slower customer qualifications, which can keep pressure on profitability and cash generation. The latest financing and trade show activity do not change that equation in a material way. They mostly reinforce that TTM is committing hard capital and engineering focus to this same direction.
The most relevant update here is the US$500 million in 6.750% senior notes due 2034, alongside planned term loan facilities, earmarked mainly for the Epiq Solutions and Swiss Technology Group deals. This funding stack increases financial leverage and makes the success of these transactions more important to the overall TTM Technologies story.
For you as a holder or potential holder, the key question is whether Epiq Solutions and STG help TTM move faster into higher value engineered systems that fit AI infrastructure and defense demand. The catalyst is clean integration and visible contribution to RF and mission systems, while the risk is higher interest costs and more capital tied up if these assets do not scale as expected.
What Analysts Are Baking Into The TTM Technologies Story
TTM Technologies' current analyst playbook relies on a sharp ramp in both revenue and profitability over the next few years. Consensus models indicate revenue expanding at about 23.2% a year for the next 3 years, with earnings today of US$195.3 million expected to reach US$709.3 million by 2029, which is an increase of roughly US$514 million in profit. That forecast year of 2029 also assumes a P/E of 40.8x on those earnings and a move in net margin from 6.3% to 12.2% as the higher value RF and mission systems mix gains traction.
Uncover how TTM Technologies' fair value indicates a potential 85% upside to its current price that could narrow quickly if sentiment around TTM Technologies improves.
Exploring Other Perspectives
One alternate angle to watch is how bullish analysts treat the new debt load. Before this news, the most optimistic group already penciled in revenue of about US$5.9b and earnings of roughly US$735.1 million by 2029 for TTM Technologies. You can see how opinions diverge widely, and these conference and financing updates may push those narratives to shift.
Explore 4 other TTM Technologies fair value estimates, including one that suggests up to 92% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TTM Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TTM Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TTM Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TTM Technologies?
Once you have a view on TTM Technologies, it can help to compare that thesis with other companies that share similar qualities such as cash strength, income potential, or low risk profiles. The Simply Wall St Screener lets you move from a single ticker to a broader watchlist in a few focused steps.
- If capital preservation is near the top of your list, start with a basket of resilient businesses by reviewing 30 resilient stocks with low risk scores that aim to keep volatility in check.
- If dependable income is what you are after, look at companies with higher yields and stable payout histories through our curated set of 6 dividend fortresses.
- If you prefer to hunt for mispriced opportunities, scan a targeted group of potentially underappreciated companies via the Simply Wall St collection of 29 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com