


How Aurora Launch At PDF Solutions (PDFS) Has Changed Its Investment Story
- PDF Solutions introduced Exensio Aurora, a new Exensio analytics architecture built to handle petabyte scale semiconductor manufacturing data and to securely deploy agentic AI across factories and supply chains. A beta release is planned for September 2026, with public demos at its CONNECT 2026 event.
- The platform’s focus on server-side analytics, a semiconductor specific data model, and workflow based AI agents speaks directly to rising complexity in 3D architectures, advanced packaging, and globally dispersed production, where most manufacturing data currently goes largely unused.
- We will look at how PDF Solutions' investment narrative aligns with Exensio Aurora's petabyte scale, AI ready architecture for manufacturing data.
Scan how PDF Solutions is leaning into AI ready chip manufacturing data, then size up other potential beneficiaries across our hand picked 89 AI infrastructure stocks shaping the data plumbing behind next generation fabs.
PDF Solutions Investment Narrative Recap
To own PDF Solutions, you need to believe that fabs will keep leaning on specialized manufacturing data platforms rather than generic cloud tools, and that Exensio can stay central to how they run production. The near term hinge is whether existing customers expand their usage of Exensio and Sapience fast enough to justify heavy R&D and capex.
The Exensio Aurora launch looks important for the story but may not move the immediate needle until real deployments show up. The biggest current risk remains execution on the transition to richer, SaaS style recurring revenue while managing spending, especially with customer concentration and geopolitical exposure around China still in the background.
The Exensio Aurora architecture is the announcement that matters most here because it sits directly on top of PDF Solutions’ core Exensio platform. It targets petabyte scale analytics, workflow centric AI agents, and a manufacturing specific data house, all meant to handle 3D architectures, advanced packaging and more distributed production.
For you as a shareholder, the key question is whether Aurora helps deepen existing relationships and supports cross selling into areas like secureWISE and Sapience, without stretching delivery teams or inflating costs. If Aurora adoption is slow or customers build more tools in house, the upside from these catalysts becomes harder to realise.
PDF Solutions' narrative projects $384.2 million in revenue and $86.6 million in earnings by 2029. This projection is based on an assumed 18.4% yearly revenue growth rate and an earnings increase of about $79.4 million from $7.2 million today.
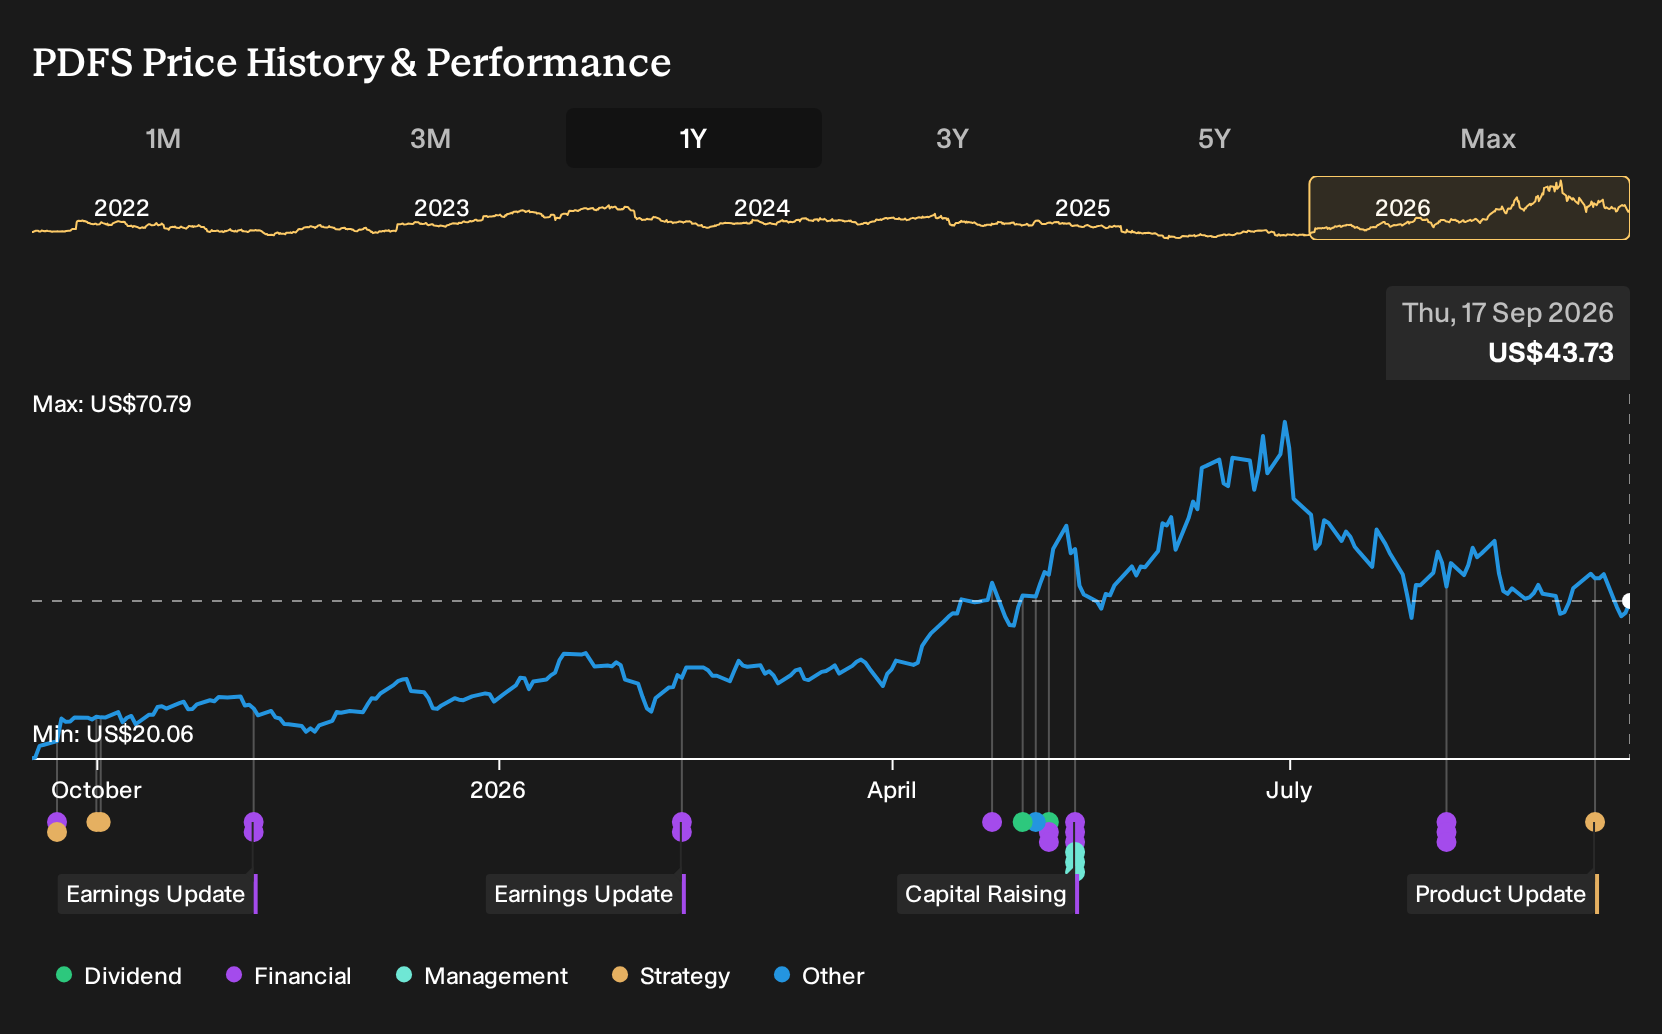
Uncover why PDF Solutions' fair value indicates a 36% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on PDF Solutions focuses on rising data privacy rules. The most cautious analysts worry that stricter rules could cap SaaS scale and keep margins lower than hoped. Their models still pencil in about $399.4 million of revenue and $83.6 million of earnings by 2029, yet they use a lower $51.5 price target. These estimates all predate the Exensio Aurora news, so opinions may shift as more details emerge on both stories.
Explore 3 other PDF Solutions fair value estimates, including one that suggests as much as 73% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PDF Solutions research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PDF Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PDF Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond PDF Solutions?
If the Exensio Aurora story has you thinking about where else manufacturing data, resilient balance sheets, or mispriced quality might matter, it can help to scan a broader watchlist using the Simply Wall St Screener.
- For investors hunting for growth potential at lower entry prices, review a curated set of 7 elite penny stocks with strong financials that already show stronger financial underpinnings than many peers.
- If valuation discipline is the priority, focus on a hand picked pool of companies trading below their assessed worth through the 29 high quality undervalued stocks so you can see which ideas warrant a deeper look.
- For a calmer ride through market swings, start with a 30 resilient stocks with low risk scores and filter for businesses that pair sturdier fundamentals with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com