


Is ICU Medical (ICUI) Cheap After Its Veterinary IV Set Recall?
ICU Medical (ICUI) is in the spotlight after voluntarily recalling 1,721,800 veterinary IV sets with drip chambers that may contain black specks, an issue regulators classify as a Class II event.
The recall comes after a strong run for ICU Medical, with the share price up 8.93% over 90 days and the 1-year total shareholder return at 14.95%. However, momentum has recently cooled, with a 30-day share price return down 16.79% and short-term weakness around the latest insider sales.
Scan beyond ICU Medical and compare this recall story with other health-focused businesses on our hand picked list of list of solid balance sheet and fundamentals (23 results)
ICU Medical has delivered a solid 1 year run, yet the sharp pullback over the past month and the discount to analyst targets tell a different story. Has most of the upside already played out, or not yet?
Most Popular Narrative: 20% Undervalued
ICU Medical last closed at $152.91 while the most followed narrative anchors fair value at $191.50. The current recall therefore sits against a backdrop of a stock that this framework treats as trading at a discount and heavily tied to pump performance and cash generation.
Rapidly progressing software and innovation pipeline, including integration of legacy ICU and Smiths platforms, and upcoming launches of interconnected cloud-based infusion pump solutions, positions the company for increased recurring revenues and improved operating leverage as technology refresh cycles take effect. Anticipated long-term benefit to net margins and earnings growth.
See why 2 investors see ICU Medical as 20% undervalued.
Result: Fair Value of $191.50 (UNDERVALUED)
Still, ICU Medical faces pressure from ongoing FDA Class II recalls and higher structural tariff costs. Either of these factors could challenge the bullish margin and cash flow narrative.
Find out about the key risks to this ICU Medical narrative.
Another View: ICU Medical On Earnings Versus Peers
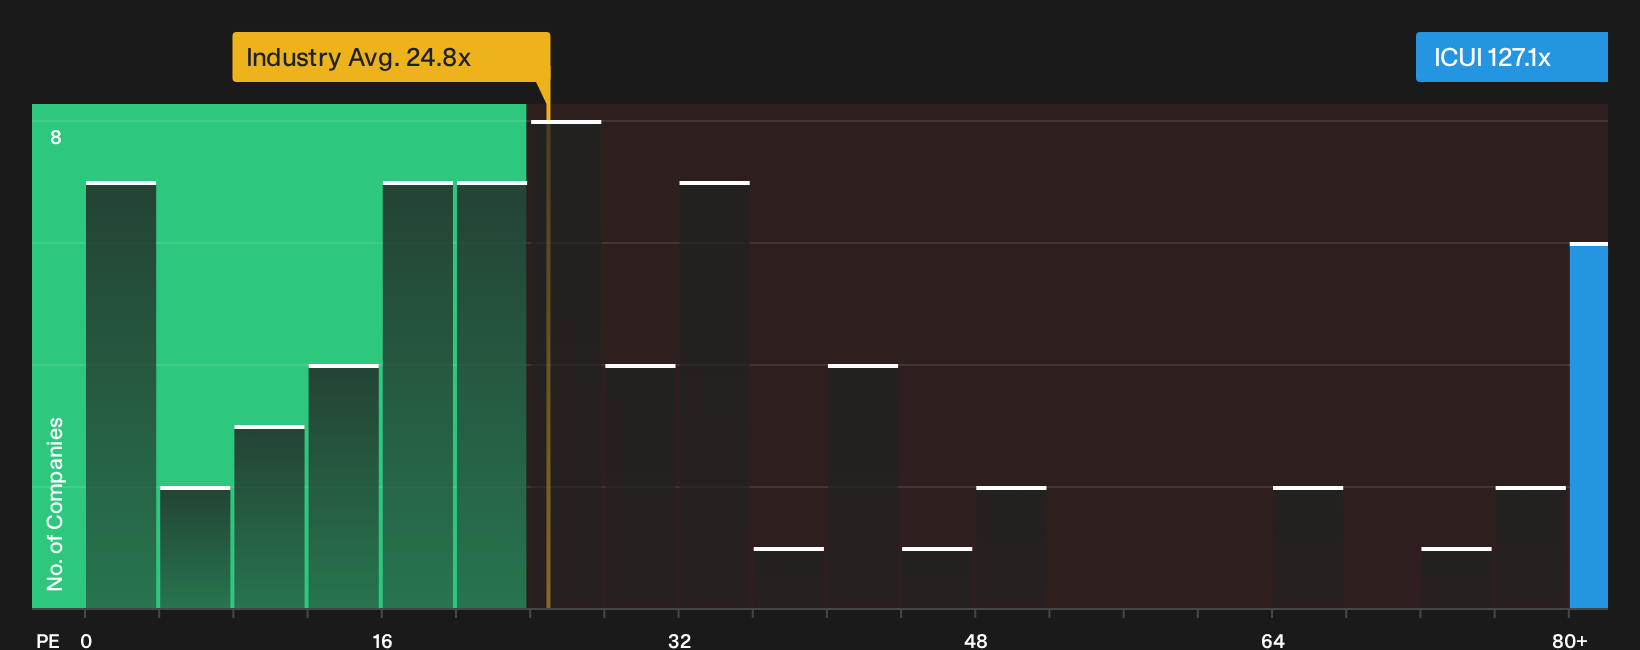
The earlier fair value work paints ICU Medical as undervalued, yet the earnings multiple tells a very different story. ICUI trades on a P/E of 127.1x, while peers average 34.8x and the fair ratio sits at 33.6x. That gap points to meaningful valuation risk if expectations reset. Investors may want to consider how comfortable they are with paying this kind of premium for future profit growth.
To see how those earnings-based comparisons stack up in detail, including where the ratio might move over time, take a look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on ICU Medical after this recall and valuation gap story. Act quickly on your own homework by weighing both sides of the ledger with 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond ICU Medical?
If ICU Medical has sharpened your thinking, do not stop here. Broaden your watchlist with targeted ideas that match your preferred balance of risk and potential reward.
- Chase underpriced quality by scanning a focused pool of businesses on our screener for 29 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night positions by filtering for companies on the 30 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking potential future leaders hiding in plain sight through our screener of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com