


Lloyds Banking Group (LSE:LLOY) Could Be 7% Below Fair Value As Accelerate 2030 Draws Focus
Lloyds Banking Group stock reacts to Accelerate 2030 focus at Barclays conference
Lloyds Banking Group (LSE:LLOY) heads into its Barclays Global Financial Services Conference appearance with investors focused on its Accelerate 2030 plan, technology spending and capital return ambitions.
The bank is targeting mid single digit income growth, a cost income ratio below 45%, and around 20% return on tangible equity by 2030, supported by about £13b earmarked for technology, AI and simplification.
Lloyds Banking Group’s latest share price of £1.122 comes after a 0.85% 1 day share price return and a 2.84% 7 day share price return, while the 13.06% year to date share price return and very large 5 year total shareholder return of 216.98% indicate that momentum has been building over time rather than fading around the Accelerate 2030 narrative.
Scan Lloyds Banking Group alongside other UK banks that are pushing hard into technology and AI driven efficiency upgrades, with our hand picked 8 high quality undervalued stocks poised for their next chapter.
Lloyds Banking Group has already delivered a very large 5 year shareholder return off the back of this reset. The question now is whether that recent momentum justifies buying at today’s price or waiting for a cheaper entry.
Most Popular Narrative: 6.5% Undervalued
Lloyds Banking Group most followed narrative points to a fair value of £1.20 per share, slightly above the latest close of £1.12. This puts the focus on whether Accelerate 2030 and AI spending can sustain that valuation over time.
Operational leverage from cost discipline, ongoing investment in AI and data analytics, and successful execution of cross-division growth initiatives, particularly in bancassurance, insurance, and fee-generating "capital-lite" businesses, are expected to support strong capital generation, improved net margins, and resilient ROE as Lloyds transitions more of its earnings base away from low-growth, commoditized lending activities.
See why 167 investors see Lloyds Banking Group as 7% undervalued.
Result: Fair Value of £1.20 (UNDERVALUED)
Still, the Lloyds Banking Group story can change quickly if UK economic weakness affects credit quality or if fintech competition erodes pricing power and fees.
Find out about the key risks to this Lloyds Banking Group narrative.
Another view on Lloyds Banking Group valuation
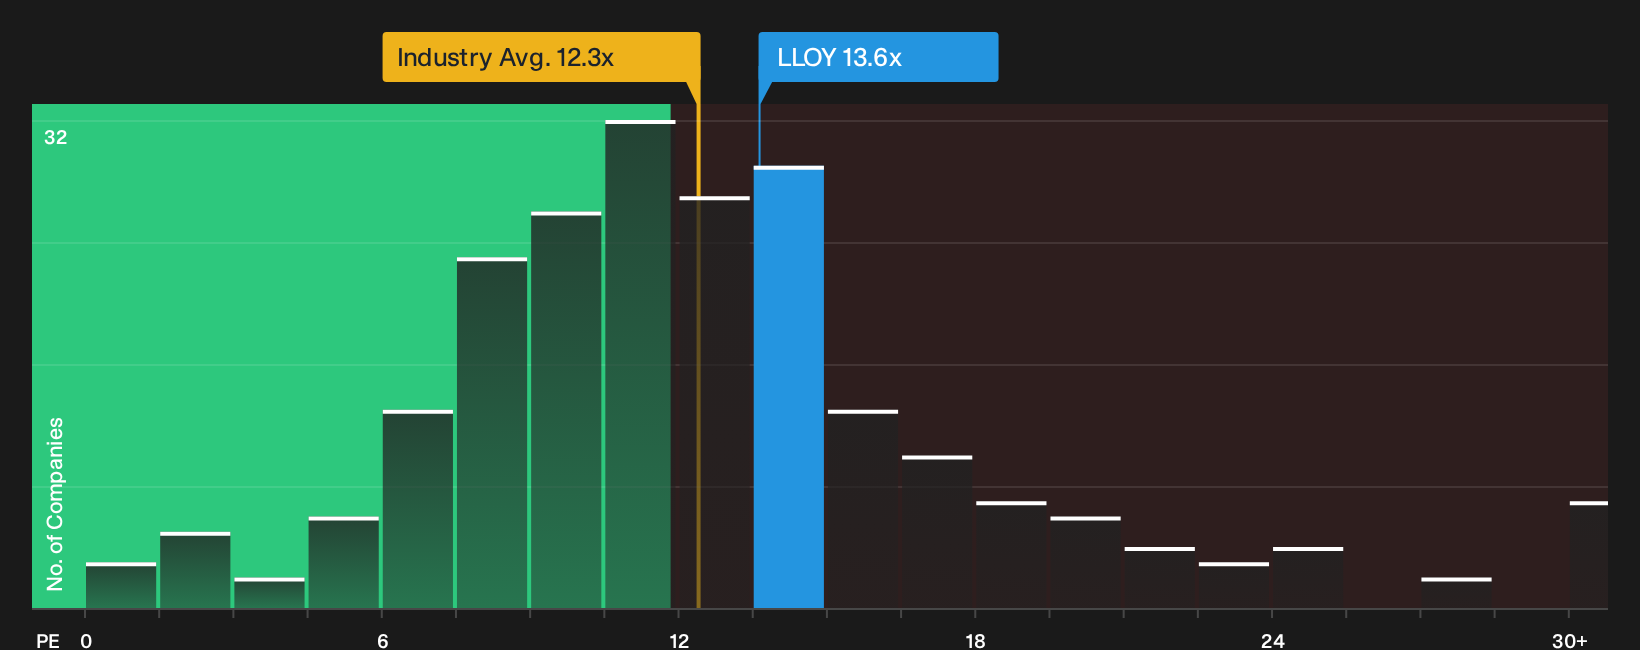
On simple earnings multiples, Lloyds Banking Group looks less generous than the DCF based fair value suggests. The shares trade on a P/E of 13.6x compared with 12.3x for the wider European banks group and 12.4x for peers, while the fair ratio sits lower again at 10.3x.
If the market edges closer to that fair ratio instead of the richer current multiple, any DCF upside could be squeezed. The key question is whether you think Lloyds Banking Group has enough earnings quality and balance sheet strength to keep justifying the premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the tone of this Lloyds Banking Group story feels mixed, that is the point. Both risks and upsides are in play right now, so move quickly, review the key data, and weigh the 3 key rewards and 3 important warning signs.
Looking for more Lloyds Banking Group sized opportunities?
Do not stop with Lloyds Banking Group. Broaden your watchlist with a few focused idea lists that surface different types of opportunities before the crowd gets there.
- Target potential mispricing early by scanning a focused pool of undervalued candidates with relatively strong fundamentals through the 8 high quality undervalued stocks.
- Build more resilient income by zeroing in on companies screened as 1 dividend fortresses that combine higher yields with an emphasis on durability.
- Sleep better at night by filtering for 4 resilient stocks with low risk scores that aim to keep business and balance sheet red flags to a minimum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com