


Can Mission Produce (AVO) Justify Its Valuation On Higher Avocado Volumes And Synergies?
Mission Produce (AVO) just paired a sharp jump in third quarter revenue with new avocado production guidance and an updated synergy target from its Calavo deal, giving investors fresh numbers to reassess the stock.
The fresh production guidance and synergy update land after a choppy stretch for Mission Produce’s stock, with the share price down 5.9% over the past week and 4.7% over the past month. The stock still shows a 90-day share price return of 8.4% and a 3-year total shareholder return of 28.1%. Together, these figures indicate momentum that has cooled recently but remains intact over a longer horizon as investors weigh higher avocado volumes against recent losses and buybacks.
Scan how Mission Produce’s avocado surge compares with other food producers by checking a curated list of list of solid balance sheet and fundamentals (23 results) that may handle volume swings and pricing pressure differently.
Mission Produce now trades well below the average analyst target after a choppy pullback, while fresh guidance and synergies reshape the earnings picture. Where does fair value really sit within that spread?
Preferred Price-to-Sales of 0.8x for Mission Produce: Is it justified?
Mission Produce trades on a P/S ratio of 0.8x, which sets the bar higher than both its own fair ratio estimate and the wider food sector. For anyone weighing the latest guidance against the share price near $12.46, that premium multiple is an important part of the story.
The P/S ratio compares the company’s market value to its annual revenue. For a business like Mission Produce, which generated $1,338.5m in sales and operates in low margin fresh produce, investors often use P/S as a quick gauge of how much they are paying for each dollar of top line.
Mission Produce is flagged as expensive on this measure compared with the US Food industry average P/S of 0.6x, and it also screens as rich versus a peer group average of 0.4x. The fair P/S ratio estimate sits at 0.6x, which means the current valuation reflects higher expectations than that benchmark level and could move closer to it if sentiment or forecasts change.
Explore the SWS fair ratio for Mission Produce.
Result: Price-to-sales of 0.8x (OVERVALUED)
Still, Mission Produce faces real pressure if avocado volumes soften again or if integration from the Calavo deal drags longer than the current synergy plan assumes.
Find out about the key risks to this Mission Produce narrative.
Another view on Mission Produce’s valuation
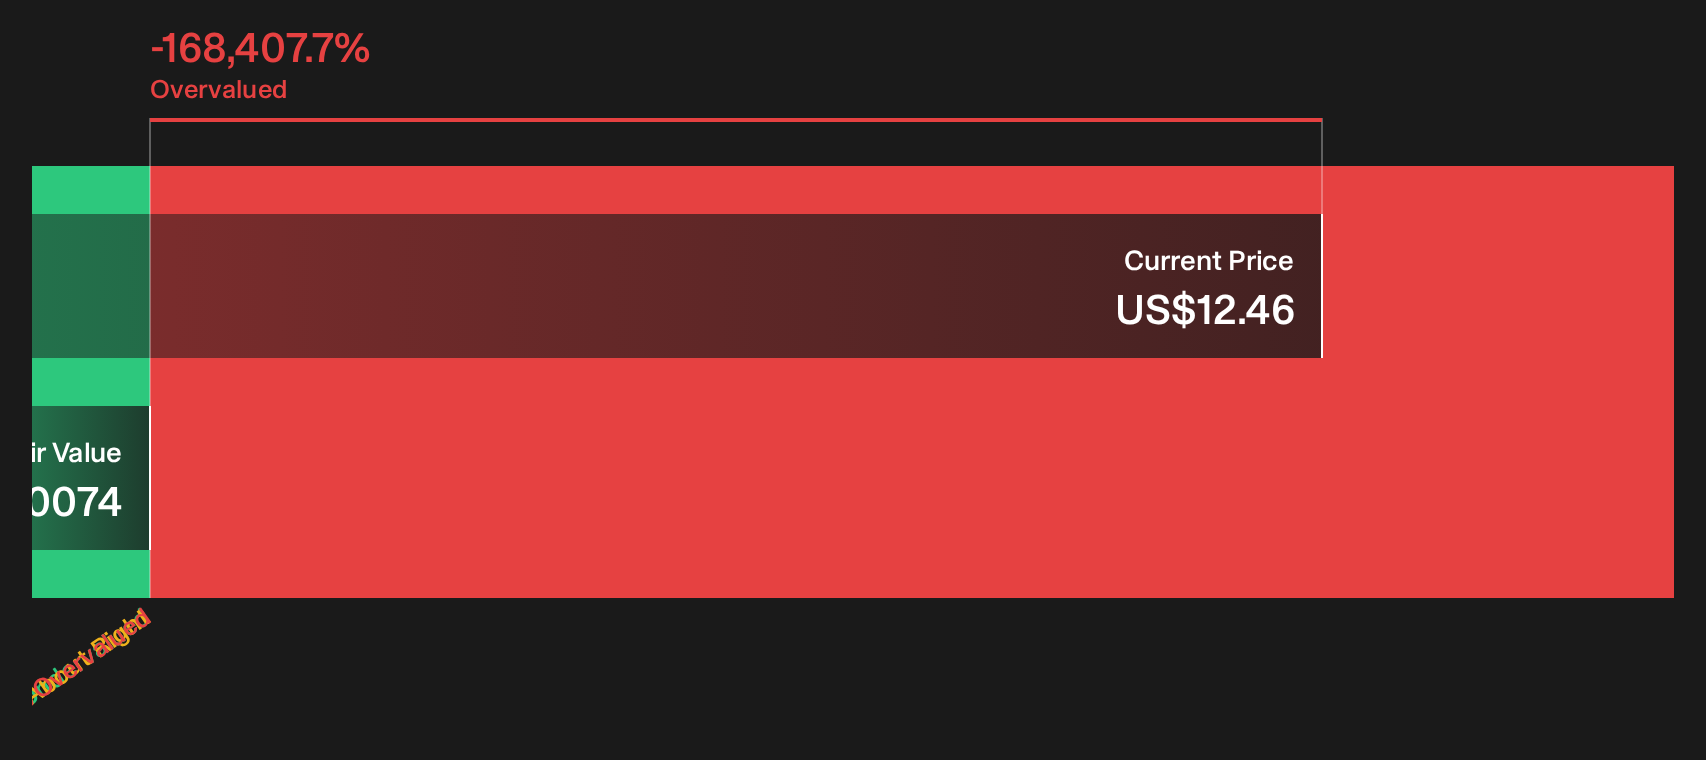
The SWS DCF model paints a far harsher picture for Mission Produce than the current P/S discussion. On that framework, the future cash flow value sits near $0.01 per share while the stock trades around $12.46. That gap points to meaningful valuation risk if optimistic earnings forecasts do not materialise. The question for investors is which signal should carry more weight.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mission Produce for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity, you need to see the full risk and reward picture for yourself and move quickly while the data is fresh. To pressure test your own take on Mission Produce, start with the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Mission Produce?
If Mission Produce has you thinking differently about valuation and risk, do not stop here. Fresh ideas often show up where few investors are looking.
- Target steadier compounding by scanning a 30 resilient stocks with low risk scores that focuses on businesses with resilience front and center.
- Hunt for priced-in pessimism by reviewing a 29 high quality undervalued stocks that filters for quality fundamentals at restrained valuations.
- Get ahead of the crowd by tracking a 16 high quality undiscovered gems that highlights under-the-radar companies with solid financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com