


Booz Allen Hamilton (BAH) Stock Could Be Cheap On Current Earnings
Booz Allen Hamilton Holding has seen mixed share performance in recent years, and that uneven record puts fresh focus on whether the current price reflects what its earnings can reasonably support. With the stock moving around, the key issue is how much of the consulting group’s profit power is already embedded in today’s valuation.
- Over the past 3 years the share price has fallen 22.0%, which raises the question of whether the current market value still lines up with the business’s earnings profile.
- The company relies heavily on converting consulting contracts into steady profits, so the durability of client demand and cost discipline can shape how much investors are prepared to pay for each dollar of earnings.
- There is a second opinion on Booz Allen Hamilton Holding worth weighing. See what analysts think Booz Allen Hamilton Holding's shares could be worth.
The issue now is whether Booz Allen Hamilton Holding’s current share price is appropriately supported by the earnings it generates today and what investors expect from those profits over time.
If you want to stress test this same earnings question beyond Booz Allen Hamilton Holding, it can help to line it up against 29 high quality undervalued stocks.
Does Booz Allen Hamilton Holding Look Undervalued on Earnings?
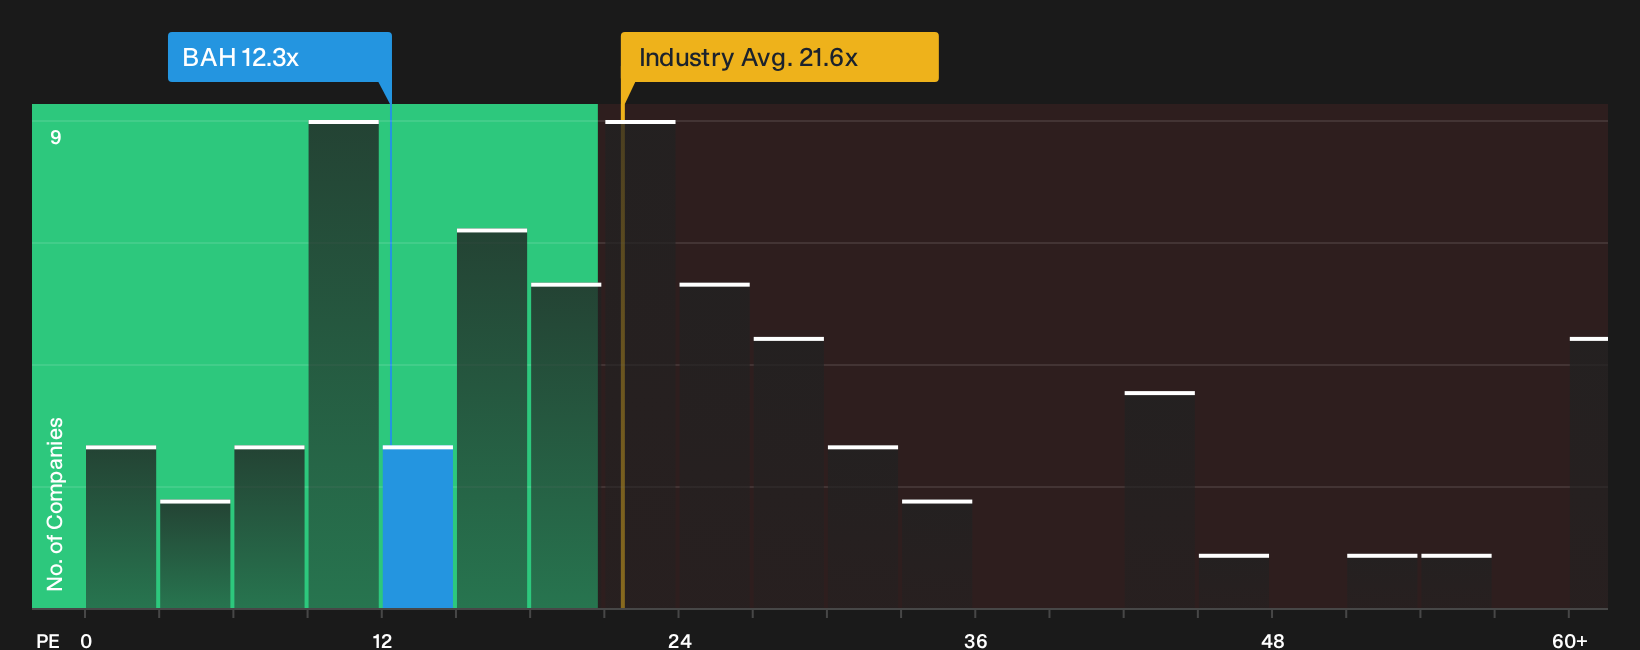
The P/E ratio is a useful lens for Booz Allen Hamilton Holding because earnings are a central anchor for how investors tend to assess consulting groups. On this measure, the stock trades on about 12.3x earnings, which is well below the Professional Services sector average near 21.6x and also sits under the wider peer group on roughly 26.1x. That gap indicates the market is currently paying less for each dollar of Booz Allen Hamilton Holding’s profit than it is for comparable businesses.
The fair P/E level implied by the valuation work here, which blends the company’s profitability profile, sector, size and risk traits, comes out higher than where the shares trade today. As a result, the current 12.3x multiple appears undervalued relative to that more tailored yardstick, and the difference between the two figures is what the detailed valuation output is designed to spell out for you. Explore the numbers behind Booz Allen Hamilton Holding's P/E valuation.
The Booz Allen Hamilton Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Booz Allen Hamilton Holding valuation puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each narrative links a specific fair value estimate to a clear storyline about Booz Allen Hamilton Holding's potential catalysts and key risks, so you can track over time which version of events is actually unfolding on the Community page.
Community views on Booz Allen Hamilton Holding split between those who see upside from defense tech and cash returns and those who focus on contract risk and automation pressure.
Bull case: 8% undervalued
"Expanding outcome-based and fixed-price contracting, especially for proprietary software and tech-enabled offerings like Thunderdome, could improve margins and increase earnings..."
Discover why this Narrative puts Booz Allen Hamilton Holding at 8% undervalued.
Bear case: 14% overvalued
"Client preference is rapidly moving toward outcome-based, fixed-price contracts rather than traditional time-and-materials billing, which will intensify price competition and compress industry-wide margins..."
Explore why this Narrative puts Booz Allen Hamilton Holding at 14% overvalued.
An unresolved question for Booz Allen Hamilton Holding investors
Price and earnings only tell part of the Booz Allen Hamilton Holding story, because separate risk checks have flagged potential trouble spots that deserve a closer look before any firm view is formed. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com