


WisdomTree (WT) Stock Looks Pricey Despite Its 303% Five Year Run
WisdomTree has turned into a very different stock over the past few years, and the recent share price level raises a straightforward question. Are investors paying a price that its current earnings can reasonably support, or has sentiment moved ahead of the underlying profit engine?
- Over the past 5 years, WisdomTree has delivered a share price return of about 302.7%, which puts a lot of pressure on its earnings to justify where the stock now trades.
- Record assets under management of about $174b and more than $12b of net inflows year to date suggest the business can sustain expectations for earnings that depend heavily on fee-based revenue, while the Digital Assets segment passing $1b of AUM may influence how durable those profits look.
- There is a second opinion on WisdomTree worth weighing. See what analysts think WisdomTree's shares could be worth.
The issue now is whether today’s valuation is adequately explained by WisdomTree’s earnings, once you line it up against the Fair Ratio benchmark.
To see how WisdomTree’s earnings-driven story compares with other potential opportunities built on fee and cash flow resilience, scan the solid balance sheet and fundamentals stocks screener (23 results).
Has WisdomTree Run Too Far on Earnings?
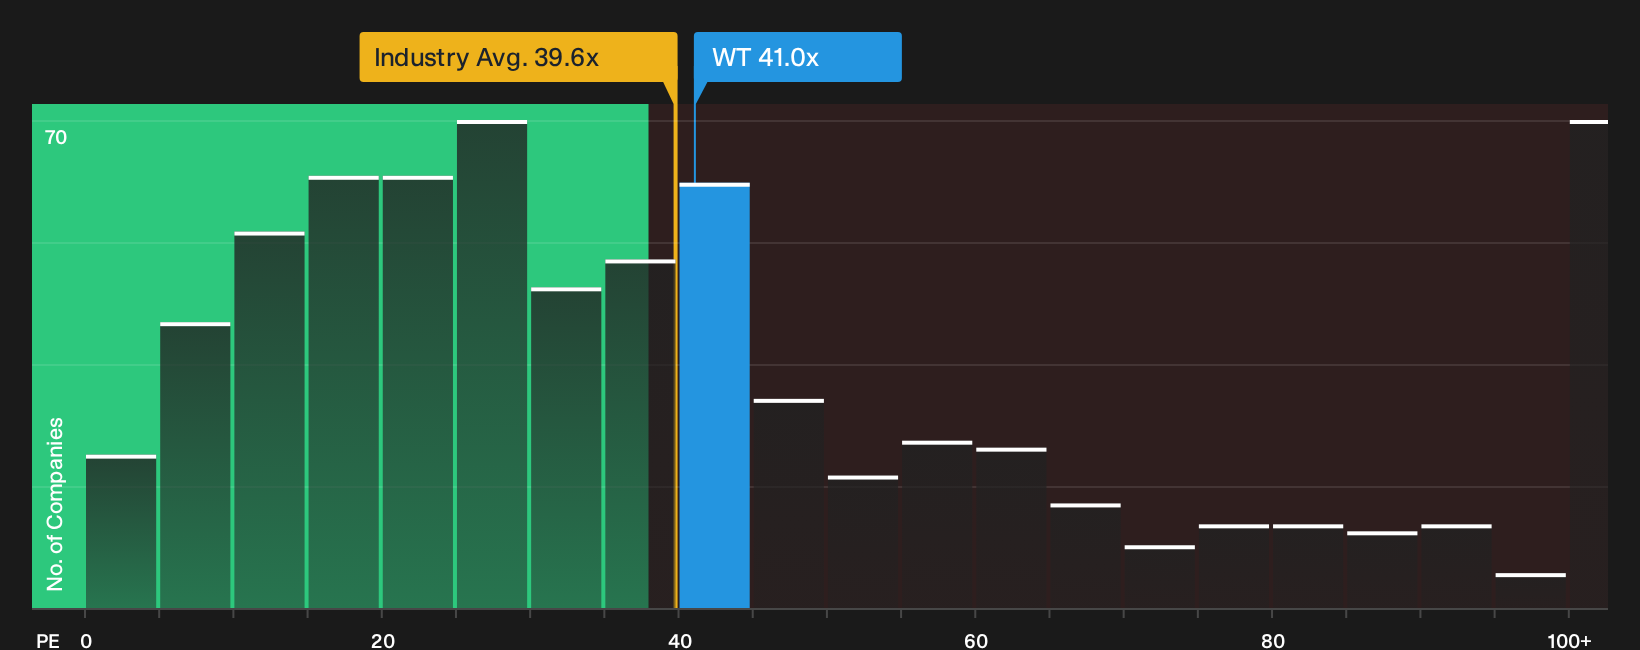
The P/E ratio fits WisdomTree because earnings are the core reference point for how this asset manager is being priced. The stock trades on about 41.0x earnings, which is above the Capital Markets industry average of roughly 39.6x and well ahead of the peer group near 18.0x. That gap suggests investors are paying a premium for each dollar of WisdomTree’s profit compared with many other listed platforms in the same space.
The Fair Ratio framework, which blends factors such as growth profile, profitability, size and risk, points to a lower earnings multiple than where WisdomTree currently trades. As a result, the shares screen overvalued on this metric. Record AUM of about $174b and over $12b of net inflows year to date help explain why investors are comfortable granting that premium. However, the current P/E still reflects a generous view of how durable those earnings are. To see how the current multiple compares with the Fair Ratio and with peers in more detail, review. Explore the numbers behind WisdomTree's P/E valuation.
The WisdomTree Narrative: What Would Justify Today's Price?
Narratives on WisdomTree pick up from that valuation puzzle and spell out which earnings, margin and growth assumptions would need to hold for the shares to be worth significantly more or less than the current price, so you can see the implied story rather than just a single number. Each one treats fair value as a thesis about how the business might evolve over time that you can revisit as fresh data arrives. They sit on Simply Wall St's Community page.
Community views on WisdomTree are split between those who see optionality in its newer products and those who think the earnings multiple already prices that in.
Bull case: 5% undervalued
"WisdomTree's early investments in blockchain, tokenization, and stablecoin-powered digital asset infrastructure are enabling new product and revenue streams such as tokenized funds..."
Discover why this Narrative puts WisdomTree at 5% undervalued.
Bear case: 22% overvalued
"The high capital outlays for expansion into digital assets, blockchain solutions, and tokenization initiatives introduce substantial execution and regulatory risk..."
Explore why this Narrative puts WisdomTree at 22% overvalued.
One more WisdomTree check that belongs next to the earnings multiple
Price and profit only tell part of the story for WisdomTree, because Simply Wall St's broader review has also surfaced company specific red flags that some investors might want to weigh before deciding what the valuation really means. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com