


Will Earnings Miss Change Watsco Stock Narrative
- Watsco reported Q2 revenues of US$2.10b, which were 2.1% higher year on year but below analyst expectations, alongside a significant earnings per share shortfall versus consensus.
- The weak earnings print came as management pointed to a more conventional operating backdrop, where scale, OEM partnerships, and technology investments are expected to matter more for long term value creation.
- Investors will now assess how Watsco's investment narrative could be reshaped by the recent earnings miss versus analyst expectations.
Scan how investors are reassessing earnings-driven stories like Watsco by comparing it with our curated list of 29 high quality undervalued stocks that have stronger recent sentiment behind them.
Watsco Investment Narrative Recap
To own Watsco, investors need to be comfortable with a distributor that is in the middle of a major product transition to A2L and higher efficiency systems, while dealing with tariffs, OEM pricing, and refrigerant supply risks. The recent Q2 miss and share price drop put more focus on execution, but the core thesis around scale, OEM ties, and technology remains operationally intact.
In the near term, the key swing factor is whether replacement demand and A2L adoption translate into cleaner inventory management and stable gross margins. The biggest risk is that OEM pricing, tariffs, or refrigerant shortages disrupt that transition and push customers toward cheaper, lower margin equipment, which would pressure earnings quality.
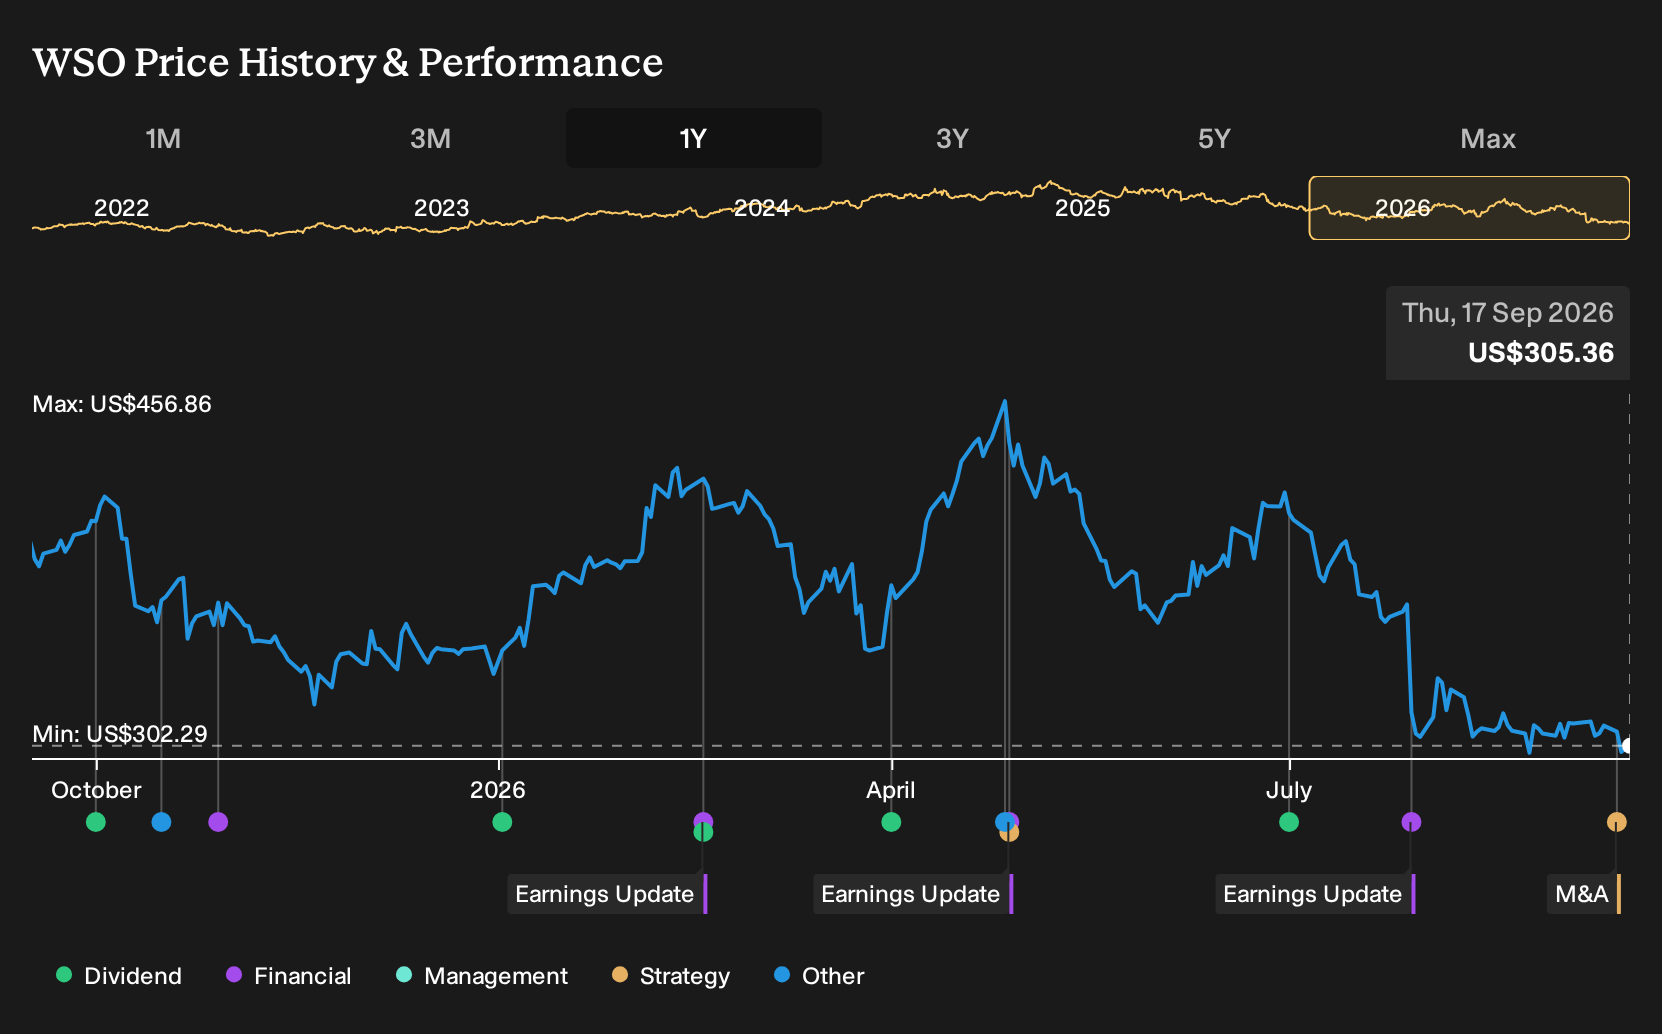
The upcoming appearance at Morgan Stanley's 14th Annual Laguna Conference on 16 September 2026 gives Watsco a platform to reset the story after a weak Q2 and a roughly 17.4% share price decline since that report. Investors will likely listen closely to Rick Gomez to understand how management sees A2L rollout, OEM collaboration, and technology investments affecting operations over the next few quarters.
For a holder, the key question is whether commentary at that conference adds clarity on the most immediate catalysts, such as pricing discipline with OEMs and the ability to keep product flowing despite tariff and refrigerant risks. Any concrete operational detail on inventory, working capital, and customer mix could matter more in the short term than broad, long-term optimism.
Watsco's current analyst narrative points to US$8.9b in revenue and US$686.8m in earnings by 2029, based on an assumed 7.1% yearly revenue growth rate and an earnings increase of about US$243.3m from the US$443.5m reported today.
Uncover how Watsco's fair value indicates a 24% potential upside to its current price before sentiment closes that gap.
Exploring Other Perspectives
One alternative view on Watsco leans hard into tariff risk. Before this Q2 miss and the Laguna conference slot were on the table, the most cautious analysts were only pencilling in about US$8.4b of revenue and US$567.1m of earnings by 2029. That is a much cooler story. Use it as a reminder that forecasts span a wide range and could shift again after fresh commentary.
Explore 3 other Watsco fair value estimates, including one that suggests it could be worth just $379.20!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Watsco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Watsco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Watsco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Watsco?
If the Watsco story has you rethinking where earnings power and balance sheet strength really matter, it can help to scan a broader field of opportunities using the Simply Wall St Screener.
- For investors who care most about valuation support and quality fundamentals, consider reviewing our curated set of 29 high quality undervalued stocks that currently line up well on both metrics.
- If capital preservation and steadier risk profiles are higher on your checklist, focus your search on companies in the 30 resilient stocks with low risk scores that score well on financial strength and volatility measures.
- When you want to get ahead of the crowd and research less followed opportunities with solid fundamentals, spend time with the 16 high quality undiscovered gems that might not yet be widely tracked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com