


United Natural Foods (UNFI) Stock May Look Pricey On Its 141% Run
United Natural Foods has delivered a strong share price run over the past few years, and that kind of move naturally pushes investors to ask whether the current US$46.30 price is still in line with what its earnings can support. With the stock now reflecting a long stretch of gains, the key issue is whether those profits and their trajectory justify where the market has taken the valuation.
- Over the past 3 years the stock has returned about 140.5%, which puts a lot of weight on the question of how its current earnings stack up against that move.
- Recent profit beats and management’s confidence in future earnings potential can support expectations for stronger profitability, which feeds directly into how much investors may be willing to pay for each dollar of income.
- Your read on United Natural Foods is one view; the desks covering it have another. See what analysts think United Natural Foods's shares could be worth.
The stock’s next move may depend on whether today’s valuation can be squared with what United Natural Foods is currently earning and what those profits reasonably point to over time.
If you are weighing whether United Natural Foods' 140.5% three year return lines up with its earnings, it can help to compare that same question across 29 high quality undervalued stocks.
Does United Natural Foods Look Pricey on Earnings?
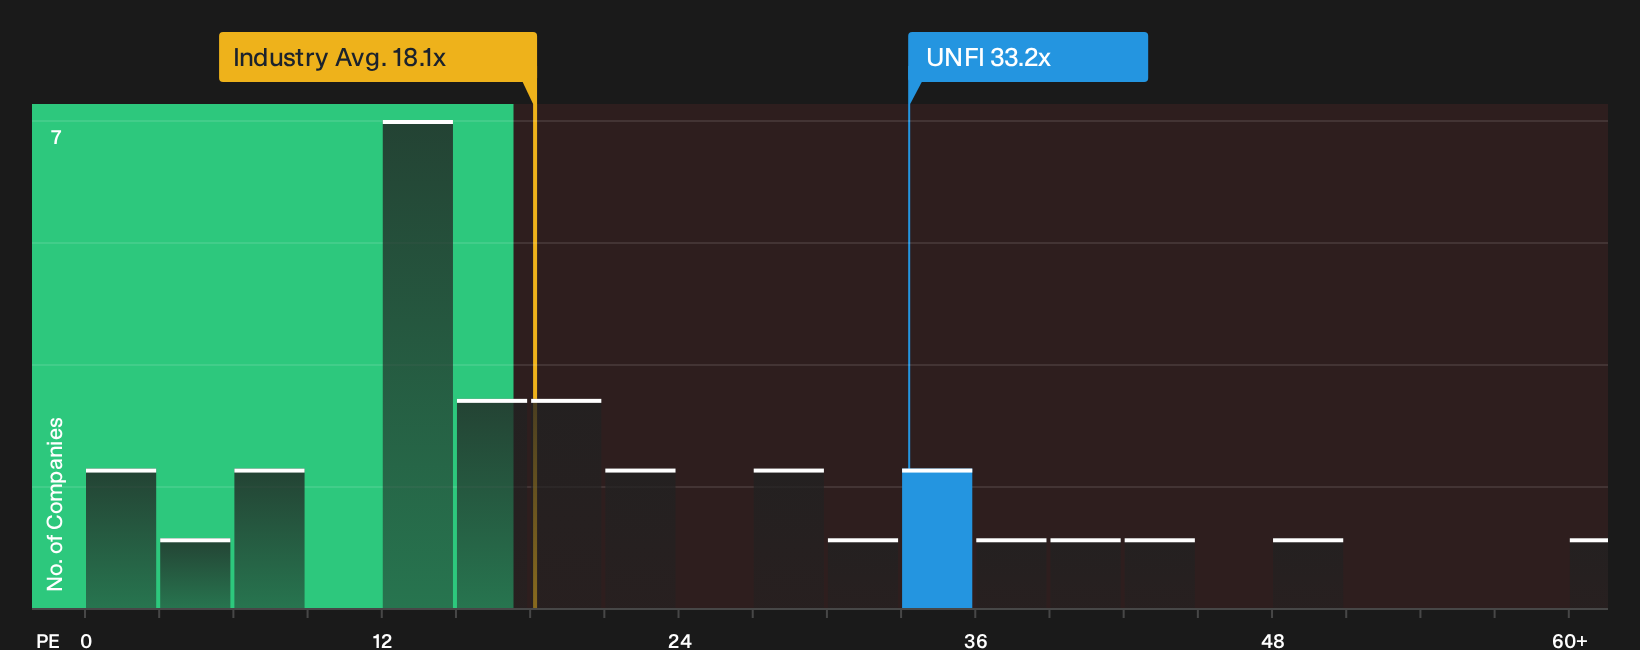
A P/E multiple suits United Natural Foods because earnings are front and centre in how investors are framing the story after recent guidance. At roughly 33.2x earnings, United Natural Foods trades above the Consumer Retailing industry average of about 18.1x, and also above the peer group on roughly 28.9x, which means buyers today are paying a higher price for each dollar of current profit than the sector generally commands.
Because the latest fair value model suggests a lower P/E would be typical for a business with United Natural Foods' mix of growth profile, margins and risk, the current 33.2x level screens as overvalued on this yardstick. Despite the stronger recent earnings reports and raised 2027 guidance, that richer multiple already bakes in a lot of optimism compared with both peers and what the tailored model implies. Any assessment now comes down to how confident you are that the recent operational progress can sustain that kind of premium. Explore the numbers behind United Natural Foods's P/E valuation.
The United Natural Foods Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St build on the United Natural Foods valuation puzzle by explaining which paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or meaningfully less than today’s price, and they appear on the Community page. Each scenario presents fair value as a thesis about how United Natural Foods' business might evolve that you can track over time rather than as a one-off snapshot.
Community views on United Natural Foods are split between those who see meaningful upside and those who think recent gains already reflect the good news.
Bull case: 24% undervalued
"The accelerating expansion of higher-margin private and exclusive brands, combined with enhanced digital supply chain integration and automation, is likely to materially boost gross margins..."
Discover why this Narrative puts United Natural Foods at 24% undervalued.
Bear case: 8% overvalued
"The accelerating trend of food brands and producers bypassing traditional wholesale distributors through direct-to-consumer channels and integrated e-commerce delivery options threatens to structurally erode wholesale volumes..."
Explore why this Narrative puts United Natural Foods at 8% overvalued.
For United Natural Foods, price is only one piece of the decision
Before you decide how to treat United Natural Foods in your portfolio, it can be worth asking who is actually steering the ship and how their incentives line up with yours. See who runs United Natural Foods and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com