


3 Japanese Financial Stocks Retail Investors Are Watching for Higher Rates
Japan’s gentle inflation pulse, a Bank of Japan policy rate now at 1.25%, and a weaker yen have turned the country’s long sleepy financial sector into a live interest rate story. Higher yields can reshape how banks lend, how insurers invest and how investors think about income. This article breaks down three Japanese financial stocks from our screener that look especially exposed to these shifts, and explains what that could mean for your portfolio.
The three stocks below are a curated sample, and the full screen surfaced 14 more Japanese financial companies with equally compelling interest rate stories that are not covered here. If you want to identify and analyze the highest conviction ideas for your own watchlist, head straight into the Japanese Financials Benefiting from Rising Interest Rates screener.
JAPAN POST BANK (TSE:7182)
Japan Post Bank is one of the purest plays on Japan’s shift to higher interest rates, given its nationwide deposit base and sizable investment book that both respond directly to changes in yields.
JAPAN POST BANK runs a retail focused franchise of savings accounts, payments, loans and pensions, anchored by banking services that generated about ¥1.9t in revenue, with its entire top line coming from Japan. The business carries a market value of roughly ¥11.7t.
"Restructuring of the yen interest rate portfolio into Japanese government bonds with yields that are currently described as relatively high, together with ongoing redemptions of JGBs that carried yields around 0%, is described as supporting interest income and profit growth over the next several years, which is directly linked to revenue and earnings."
The outcome of that reinvestment effort as it coincides with a steadily higher policy rate could be a crucial factor for future margins and payouts.
That reinvestment hinge is exactly where the story gets interesting, and the full narrative for JAPAN POST BANK outlines how rising yields, capital allocation and payout potential could all be pulling in the same direction.

Sumitomo Mitsui Financial Group (TSE:8316)
Sumitomo Mitsui Financial Group is a large Tokyo based financial group that sits right in the sweet spot of Japan’s rate story, running wholesale, retail, global and markets units that together generated about ¥1.63t from retail, ¥1.58t from global, ¥1.35t from wholesale and ¥0.77t from markets, on a market value of roughly ¥25.9t.
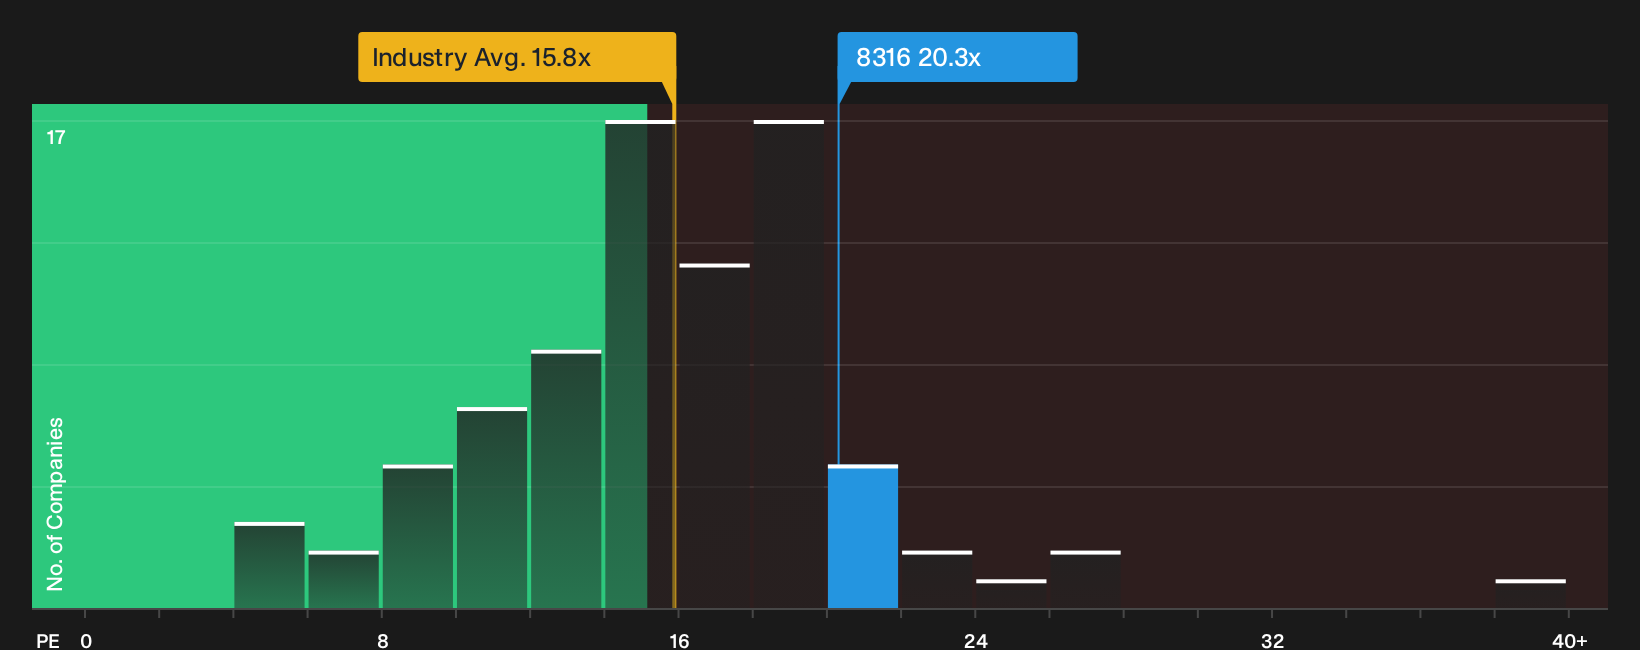
As rates climb and Japan moves away from decades of near zero money, Sumitomo Mitsui Financial Group gives you a full scale lender and securities house whose earnings are closely tied to net interest margins and a sizeable interest earning balance sheet. Income investors may focus on the dividend profile and buybacks. The key question is what happens when one unseen pressure meets that premium P/E and newer board structure.
When that tension between unseen pressure and a premium P/E matters most, readers are heading to the 4 key rewards and 1 important warning sign to see what might be hiding in plain sight.
Yamaguchi Financial Group (TSE:8418)
Yamaguchi Financial Group is a regional Japanese banking group built around a broad lending and deposit franchise, supported by securities, cards, insurance and consulting services. It generated about ¥234.9b from banking in Japan and carries a market value of roughly ¥656b.
Yamaguchi Financial Group ties straight into the rising rate theme, with its regional loan and deposit engine feeding off higher domestic yields, a 2.82% dividend yield and earnings growth forecasts that outpace the wider market. What happens to that appeal if a single key assumption about its profitability mix shifts?
If that profitability mix really is the swing factor, the 3 key rewards and 1 important warning sign could show where Yamaguchi Financial Group’s appeal accelerates or quietly stalls.

Seeking Alternatives Before The Crowd
Fresh ideas do not stay under the radar for long. By the time momentum is flying, the easy entry can be gone. Scan these picks while it matters and consider them early.
- Identify sturdy cash generators before they catch a bid by running the curated 17 high quality undervalued stocks that filters for quality balance sheets and meaningful free cash flow.
- Follow structural demand shifts by tracking infrastructure and hardware behind AI with the focused 89 AI infrastructure stocks curated for companies supplying the picks and shovels of this trend.
- Explore the potential for a metals squeeze by reviewing the targeted 16 top copper producer stocks built to surface producers tied to long term electrification trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com